

Matador Resources closed its acquisition of EnCap-backed Paloma Permian on October 1, 2026, for $1.255 billion in cash, subject to customary post-closing adjustments. The deal, announced in July at a headline consideration of $1.275 billion, is already beating the company’s own underwriting on the producing wells, while adding a large block of high-quality undeveloped inventory in the core of the Delaware Basin.
The Deal and the Money
Paloma Permian LLC was a portfolio company of EnCap Investments. Matador agreed in late July 2026 to buy the assets for cash, with an effective date of June 1. The transaction closed October 1 at $1.255 billion after adjustments.
Key value metrics disclosed at announcement include roughly 55 million barrels of oil equivalent (BOE) of proved reserves and a PV-10 of about $816 million as of May 31, 2026, using $70 per barrel oil and $3 per MMBtu gas, adjusted for differentials and fees. Oil made up the majority of the reserve base (reports cite roughly 67 percent oil in the proved volumes).
Matador is funding the purchase with cash on hand and borrowings under its reserve-based lending facility. Management has said it expects to repay approximately $350–400 million on that facility after the fourth-quarter closings (Paloma plus the related Ridge Runner transaction), depending on commodity prices. The company has guided to roughly $1 billion of adjusted free cash flow for full-year 2026 and has targeted a return of corporate leverage closer to 1.0x within 12 to 18 months of closing.
Where the Wells Are and What They Target
The assets sit in Eddy and Lea Counties, New Mexico—the two highest-producing counties in the United States in recent years and the heart of Matador’s Delaware Basin position. The package adds approximately 16,500 net acres (16,235 net undeveloped acres at announcement), the majority held by production.
Development inventory is the main prize. Matador counts more than 156 net locations normalized to two-mile laterals across nine or more potential benches, primarily in the Bone Spring and Wolfcamp formations. Fifty-nine drilling permits are already approved. The company expects to start drilling operations on up to 25 wells on the Paloma acreage by year-end 2027 and will outline fourth-quarter plans with its third-quarter earnings release in early November.
Together with the pending Ridge Runner Resources II acreage deal (also EnCap-backed and expected to close later in October) and acreage from the May 2026 federal lease sale, Matador’s Delaware Basin position is set to reach approximately 240,000 net acres in the fourth quarter of 2026. That is nearly 20 percent above the roughly 203,000 net acres the company held in October 2025. Ridge Runner is focused more on the emerging Woodford, where Matador has separately reported encouraging results from its Rae’s Creek exploratory well in southeast Lea County; Paloma itself is weighted to Bone Spring and Wolfcamp.
Production Already Ahead of Underwriting
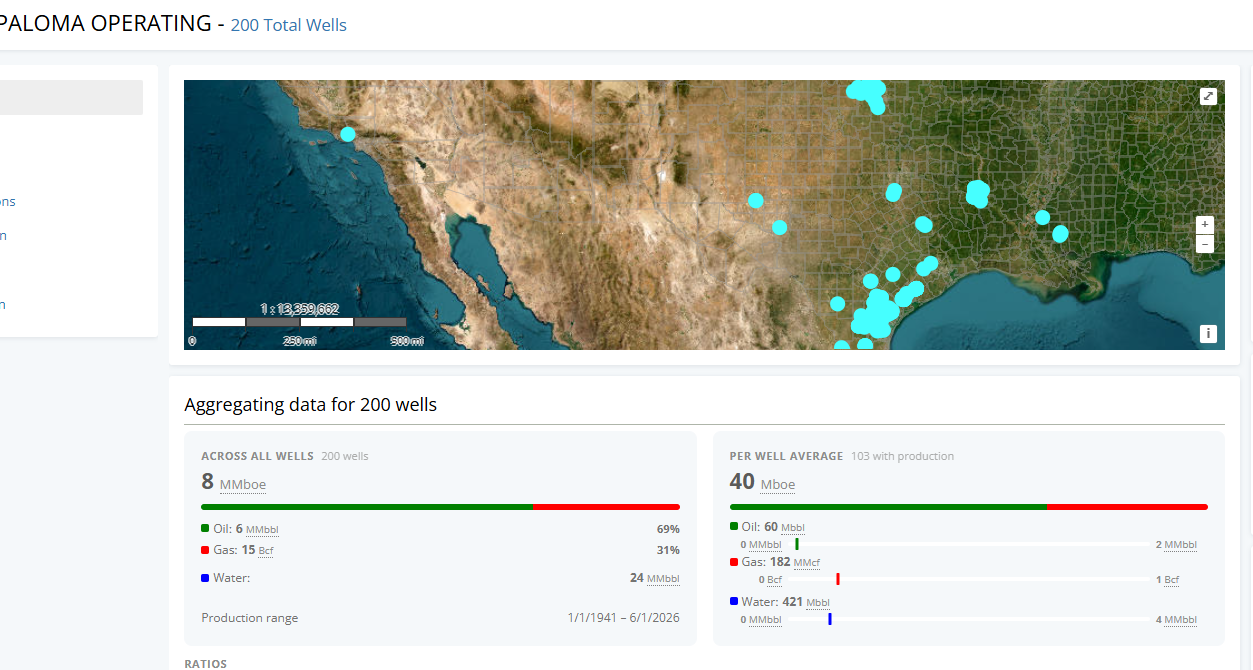
At announcement, third-quarter 2026 production from the assets was estimated at about 11,100 BOE per day (57 percent oil), within a range of roughly 10,600–11,600 BOE/d. Later company commentary put associated volumes near 12,200 BOE/d in the third quarter (about 55 percent oil).
More important for the thesis: since the June 1 effective date, production tied to the acquisition has outperformed Matador’s underwriting estimates by approximately 10 percent. Management attributes the beat largely to Paloma’s newest wells in Eddy County. Founder, Chairman, and CEO Joseph Wm. Foran noted that while most of the current value is in the undeveloped locations, the early well performance is encouraging. He also described the acreage as holding some of the highest hydrocarbon resources per acre in the Lower 48 and highlighted upside for upstream capital efficiency plus greater utilization of Matador’s wholly owned midstream system and its 51 percent-owned San Mateo Midstream joint venture.
What It Means for Investors and Stakeholders
For equity holders, the transaction extends high-quality Delaware Basin inventory at a time when premium locations are scarcer and valuations on undeveloped acreage remain firm. The early 10 percent production beat provides initial support for the underwriting assumptions that justified the price. Integration is expected to follow the pattern of prior Matador–EnCap deals: efficient absorption into the operating plan, incremental free cash flow, and contribution to planned debt reduction.
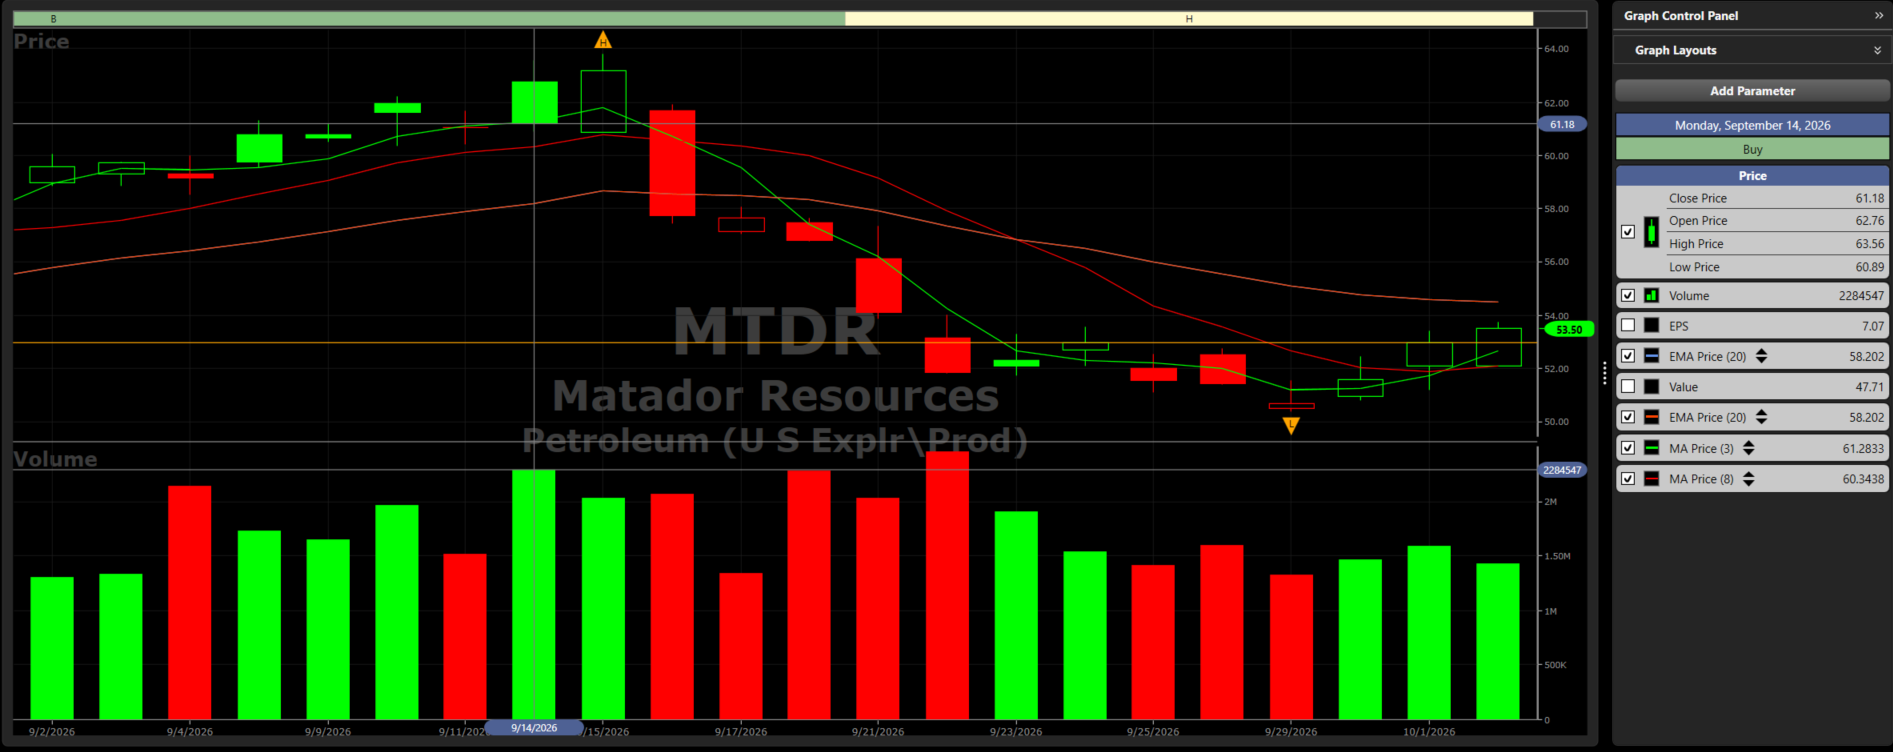
Near-term cash priorities are clear. Management intends to use post-closing cash flow to pay down the credit facility by several hundred million dollars and keep leverage on a path toward 1.0x. Matador continues to return capital via a dividend (recently $1.50 per share annually, roughly a 2.8 percent yield at prices near $53–54) alongside debt reduction. As of early October 2026 the stock traded around $53.50, implying a market capitalization near $6.6 billion; analyst consensus remained a Strong Buy with average price targets in the $70 area, though those targets predate full integration results.
Midstream stakeholders also stand to benefit. Incremental volumes from the new acreage support throughput on Matador’s owned gathering and processing and on San Mateo, improving fixed-cost absorption and flow assurance. Land and royalty owners in Eddy and Lea Counties see a well-capitalized operator with permits in hand and a stated plan to drill dozens of wells over the next 15 months. Employees and field contractors gain from the continuity of an established Delaware Basin program rather than a standalone private-equity exit.
Risks remain the usual ones for a cash acquisition of this size: commodity-price sensitivity on the pace of debt paydown, execution on the multi-bench development program, and the timing of Ridge Runner’s close. The company has flagged that average 12-month cumulative oil production on the newer federal-lease and Paloma-related assets is expected to run 20–30 percent above its historical corporate average, which, if realized, would further support the inventory quality case.
Overall, the Paloma close converts a July announcement into operated acreage and wells that are already exceeding the production case used to underwrite a $1.3 billion check. For Matador investors, the combination of a production beat, permitted locations, and a clear debt-reduction path is the near-term scorecard; the longer-term scorecard is whether the 156-plus net Bone Spring and Wolfcamp locations deliver the resource density management has highlighted.
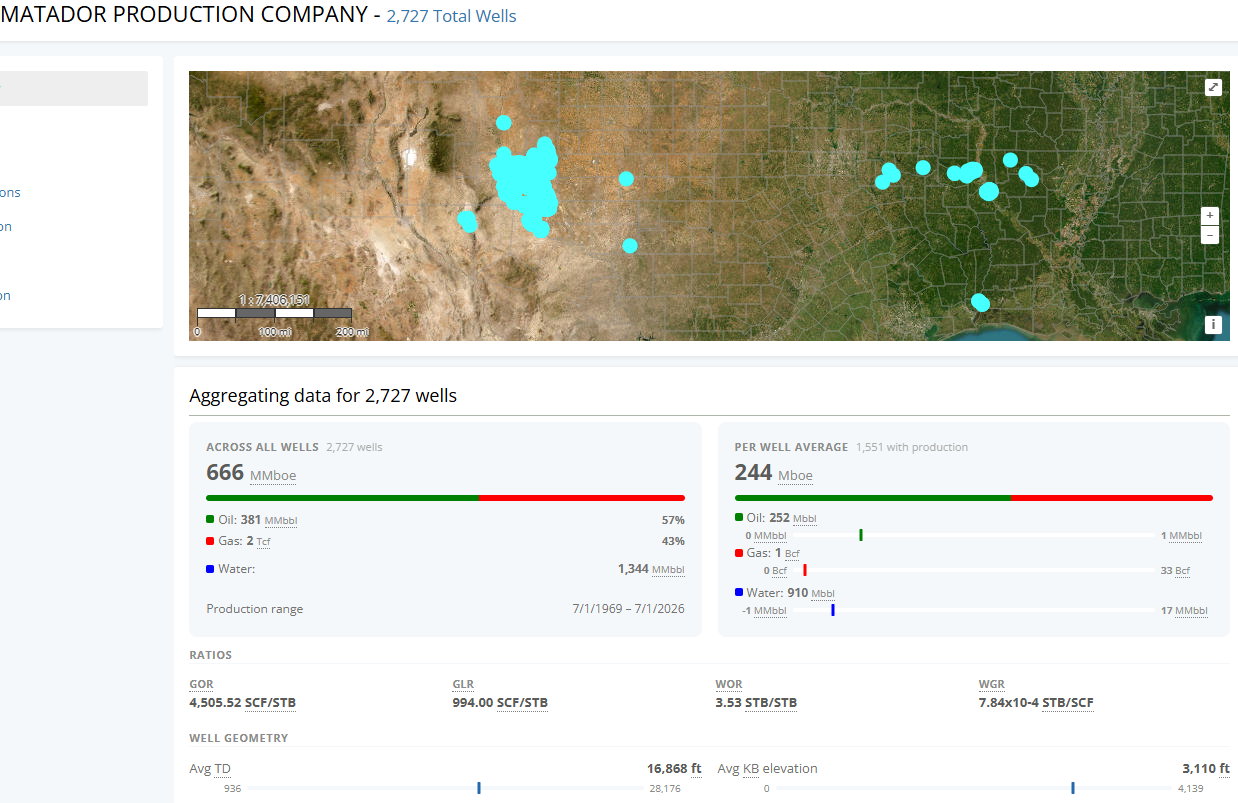
On a side note – we love WellDatabase and use their tools often.
Making Appendices Great Again
Check out the World’s Greatest Podcast Show Notes at EnergyNewsBeat.co or EnergyNewsBeat.com.
Appendix: Sources
- Matador Resources Company press release, “Matador Resources Company Closes Paloma Acquisition and Provides Additional Integration Details,” October 1, 2026.
https://www.matadorresources.com/news-releases/news-release-details/matador-resources-company-closes-paloma-acquisition-and-provides - Business Wire distribution of the closing release.
https://www.businesswire.com/news/home/20261001380429/en/ - Matador SEC Exhibit 99.1 (July 23, 2026 announcement details, reserves, PV-10, financing).
https://www.sec.gov/Archives/edgar/data/1520006/000110465926086469/tm2621144d1_ex99-1.htm - Reuters, “Matador to buy Paloma Permian for $1.28 billion, bolsters Delaware Basin presence,” July 23, 2026.
https://www.reuters.com/business/energy/matador-resources-buy-paloma-permian-13-billion-2026-07-23/ - Oil & Gas Journal, “Matador outlines drilling plans with Paloma acquisition now closed.”
https://www.ogj.com/general-interest/companies/news/55409182/matador-outlines-drilling-plans-with-paloma-acquisition-now-closed - World Oil, “Matador closes $1.26-billion Paloma acquisition, adds 156 Delaware basin drilling locations,” October 1, 2026.
https://worldoil.com/news/2026/10/1/matador-closes-1-26-billion-paloma-acquisition-adds-156-delaware-basin-drilling-locations/ - Hart Energy, “Matador’s $1.3B Paloma Deal Already Beating Expectations,” October 2, 2026.
https://www.hartenergy.com/energy-market-transactions/acquisitions-and-divestitures/he-matador-closes-paloma-deal/ - Rigzone / Bloomberg, “Matador Buys Permian Assets for $1.3B,” July 23, 2026.
https://www.rigzone.com/news/wire/matador_buys_permian_assets_for_13b-23-jul-2026-184202-article/ - OilPrice.com, “Matador Expands Delaware Basin With $1.28 Billion Paloma Acquisition,” July 23, 2026.
https://oilprice.com/Company-News/Matador-Expands-Delaware-Basin-With-128-Billion-Paloma-Acquisition.html - Dallas Morning News, “Dallas energy producer grows oil and gas profile with 2 deals,” July 28, 2026.
https://www.dallasnews.com/business/energy/article/dallas-energy-producer-grows-oil-gas-profile-2-22362330.php - Drilling Contractor, “Matador adds 156 net Delaware Basin locations as Paloma deal closes,” October 2, 2026.
https://drillingcontractor.org/matador-adds-156-net-delaware-basin-locations-as-paloma-deal-closes-80201 - Matador Q2 2026 results release (inventory and production commentary related to the pending deals), August 2026.
https://www.nasdaq.com/press-release/matador-resources-company-reports-second-quarter-2026-results-and-increases-full-year
Market data referenced (share price, market capitalization, dividend, analyst targets) drawn from public quote pages as of early October 2026, including StockAn
