
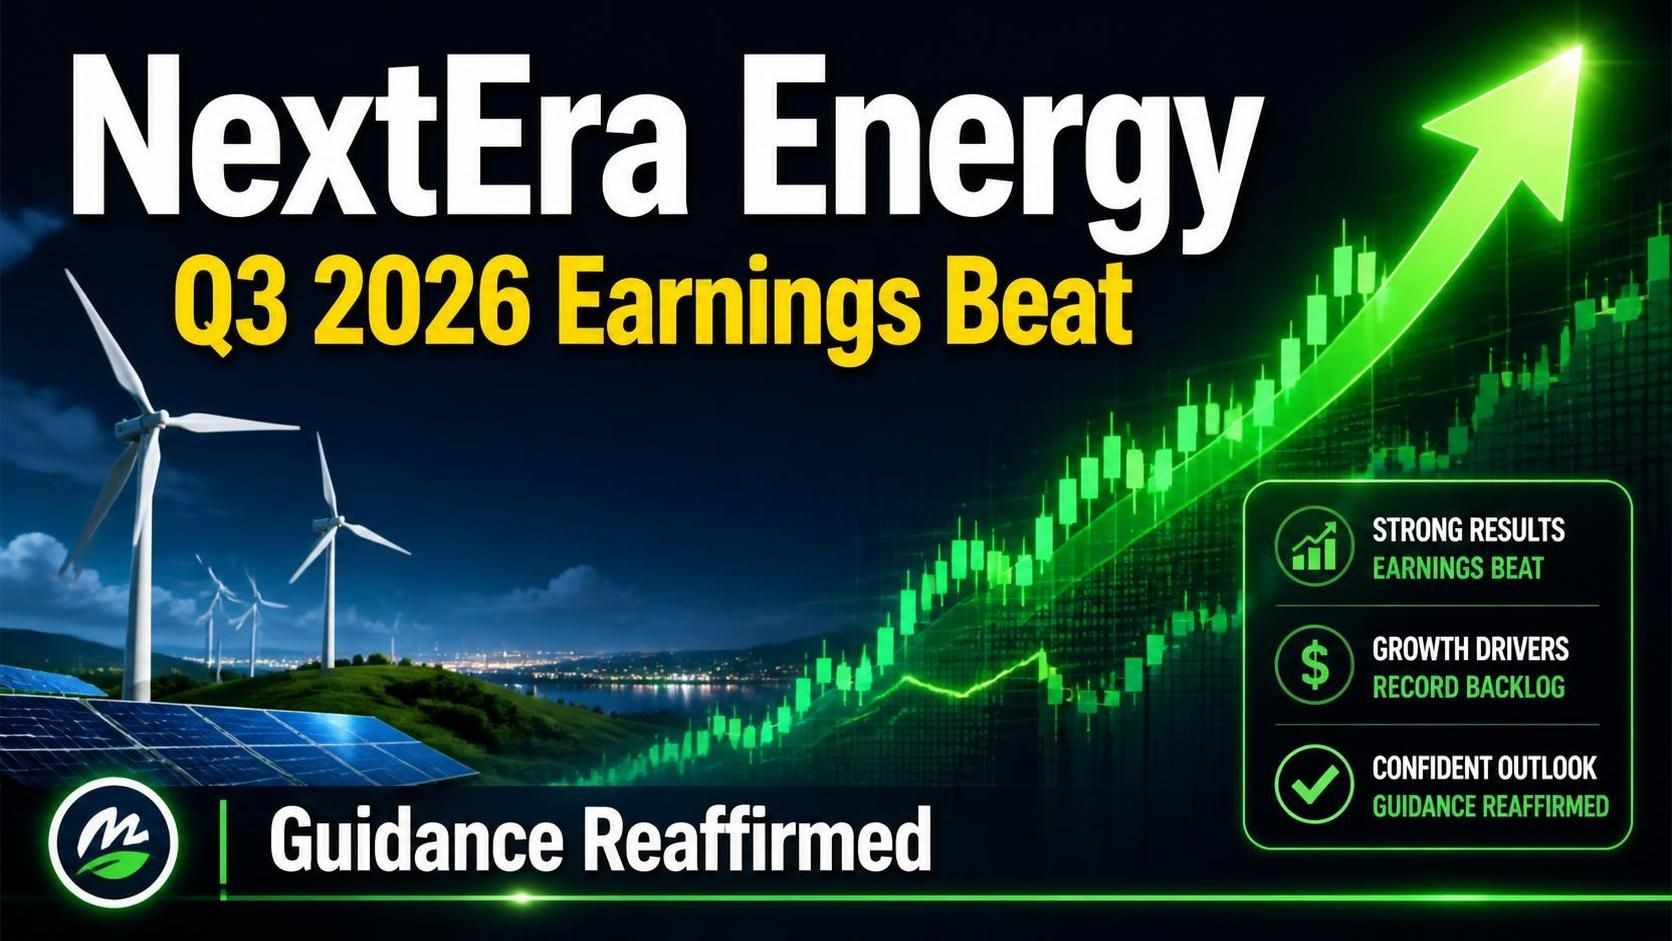
NextEra Energy, Inc. (NYSE: NEE) reported third-quarter 2026 results on October 21, 2026, showing adjusted earnings growth of 9.7% year-over-year, a beat on profit estimates, and continued expansion of its renewables and storage development pipeline. GAAP results were boosted by non-cash hedge gains, while revenue came in below expectations. Management reaffirmed full-year adjusted EPS guidance and long-term growth targets, highlighting execution at Florida Power & Light (FPL) and NextEra Energy Resources (NEER), alongside progress on large-load demand (including data centers/AI), federal hub projects, nuclear restarts, and the pending Dominion Energy combination.Investor.nexteraenergy
Key Financial Results
On a GAAP basis, NextEra reported net income attributable to the company of $4.775 billion, or $2.28 per share, compared with $2.438 billion, or $1.18 per share, in Q3 2025. Adjusted earnings were $2.592 billion, or $1.24 per share, versus $2.348 billion, or $1.13 per share a year earlier (a 9.7% increase). Operating revenues rose 1.6% to $8.090 billion from $7.966 billion.Investor.nexteraenergy
- FPL (the regulated utility serving roughly 12 million people in Florida): Net income of $1.62 billion, or $0.77 per share, up from $1.463 billion, or $0.71 per share. Regulatory capital employed grew approximately 9.2% year-over-year on disciplined capital investments of about $2.4 billion in the quarter (full-year 2026 expected near $12 billion). Retail sales rose 2.8% (1.4% weather-normalized) on customer growth. Non-fuel O&M costs remain more than 70% below the industry average on a $/MWh basis; reliability is top-decile (more than 60% better than the national average); and customer satisfaction ranks in the top decile.Investor.nexteraenergy
- NextEra Energy Resources: GAAP net income of $1.491 billion, or $0.71 per share (vs. $1.275 billion/$0.62); adjusted earnings of $1.247 billion, or $0.59 per share (up about 13% from $1.102 billion/$0.53). Growth reflected new investments (including federal hubs) and more normalized wind resources (approximately 101% of the long-term average versus 90% in Q3 2025).Investor.nexteraenergy
Nine-month 2026 adjusted EPS rose 9.5% year-over-year. GAAP results were significantly elevated by roughly $3 billion in after-tax gains from non-qualifying hedges and other items (reconciliation provided in the release; adjusted figures exclude non-qualifying hedges, certain XPLR gains, unrealized nuclear decommissioning equity securities movements, OTTI, and merger-related expenses).Investor.nexteraenergy
Growth Drivers: Backlog, Storage, Large Loads, and Hubs
NEER added 3.7 gigawatts (GW) of renewables and storage to its backlog in the quarter—including 2.4 GW of battery storage—bringing the total to approximately 36.7 GW after placing 1.8 GW into service since the Q2 call. This marked the fourth consecutive quarter of additions above 3.5 GW and roughly 15 GW added over the past 12 months. The company has completed more than two-thirds of the midpoint of its 2026–2029 development expectations.Investor.nexteraenergy
Additional highlights include:
- Agreements for three federal hub projects totaling about 16.5 GW (two in Texas, one in Pennsylvania), with $5.7 billion in initial funding secured year-to-date. NextEra expects to develop, build, and operate these for fees without investing capital.
- A development pipeline of about 30 hubs (targeting 40 by year-end) and progress on a partnership for gas-fired generation plus storage at the DOE Paducah site.
- Advancement of more than 20 GW of large-load projects (heavily gas-fired) to meet rising demand from data centers and other users.
- Duane Arnold nuclear restart on track for no later than Q1 2029 (DOE loan closed); Point Beach nuclear output under a long-term PPA extending into the 2050s.
- Regulated/transmission capital up approximately 25% to about $12.7 billion since December 2025; joint venture with Chesapeake for a South Florida gas pipeline.Investor.nexteraenergy
CEO John Ketchum stated: “NextEra Energy delivered strong third-quarter results, with adjusted earnings per share increasing 9.7% year-over-year, reflecting continued strong financial and operational performance at both FPL and NextEra Energy Resources.” He reiterated the company’s positioning for multi-year growth.Investor.nexteraenergy
Guidance, Outlook, and Dominion Combination
NextEra maintained 2026 adjusted EPS guidance of $3.92–$4.02 and is targeting the high end of the range (even factoring expected weaker Q4 wind resource of 90–95% of the long-term average due to El Niño). Long-term expectations are unchanged: adjusted EPS compound annual growth rate of 8% or more through 2032 and targeting the same rate from 2032 through 2035, all off a 2025 adjusted EPS base of $3.71. Average annual operating cash flow growth from 2025–2032 is expected to meet or exceed the adjusted EPS growth rate. Dividend growth is targeted at roughly 10% annually through 2026 (off the 2024 base) and 6% annually from 2026–2028.Investor.nexteraenergy
On the pending combination with Dominion Energy (shareholder approval secured in September 2026), the companies continue to expect closing in the second half of 2027 pending state and federal reviews (procedural schedules advancing in Virginia, South Carolina, and North Carolina). NextEra has outlined additional Virginia commitments, including doubled residential bill credits (to four years), $100 million in shareholder-funded bill assistance through 2038, workforce development funding, a Virginia supplier program, and job commitments. The combined company is expected to support roughly 11% regulatory capital growth through 2032 and 9%+ adjusted EPS growth through 2035 off the 2025 base.Investor.nexteraenergy
Forward-looking statements are subject to the usual risks (regulation, weather, markets, interest rates, merger approvals, and execution). No quantitative reconciliation is provided for forward-looking adjusted EPS due to the unknowable nature of certain items.Investor.nexteraenergy
Analyst Reactions and Market Response
The adjusted EPS of $1.24 beat consensus estimates (generally in the $1.18–$1.20 range; some sources cited $1.18 or $1.20). Revenue of $8.09 billion missed estimates (variously reported in the $8.47–$9.08 billion range). The company has a strong recent history of EPS beats but frequent revenue misses.Seeking Alpha
Jefferies highlighted that the 3.7 GW backlog addition exceeded expectations of more than 3 GW and reflected strong demand. Other coverage emphasized solid FPL execution, storage origination momentum, and reaffirmed long-term growth visibility tied to large-load and hub opportunities. Pre-earnings notes from several firms (including Barclays, BMO, BTIG, and Morgan Stanley) had trimmed price targets, often citing higher interest rates as a valuation headwind, while largely maintaining ratings. Consensus remains a Moderate Buy with average targets typically in the mid-to-high $90s (individual targets ranging widely, with some above $100 and a few much lower).Seeking Alpha
Shares closed at $78.28 on October 21, 2026, down about 0.74% (various reports noted a roughly 0.4–0.7% decline on the day), after trading in a range that saw modest pressure despite the EPS beat and guidance reaffirmation. Volume was elevated.247wallst
Implications for Investors
For investors, the quarter reinforces NextEra’s multi-year growth narrative: steady regulated rate-base expansion at FPL, high-visibility renewables/storage backlog growth (especially batteries), and emerging large-load and federal-hub opportunities that capitalize on rising power demand without always requiring full capital deployment. Reaffirmation of the high end of 2026 guidance and the 8%+ long-term adjusted EPS CAGR, plus operating cash flow growing at least as fast, supports the dividend trajectory and capital allocation story. The Dominion combination, if approved, is positioned to accelerate regulated growth and EPS accretion.
Risks and offsets include the revenue miss (partly timing/mix-related), ongoing regulatory and political scrutiny of the Dominion deal (with state reviews still ahead), interest-rate sensitivity (though management has noted hedges that limit near-term EPS impact from rate moves), weather variability in the wind portfolio, and execution on the large development pipeline. Valuation remains elevated relative to some regulated peers given the growth premium, which can amplify volatility around rates or deal news. Overall, the print was constructive for growth-oriented holders focused on execution and the demand backdrop.
Implications for Consumers
FPL continues to emphasize affordability and reliability. Management states that the typical residential bill is approximately 37% below the national average and is projected to increase only about 2% annually through the end of the decade under the current multi-year rate plan. Non-fuel O&M efficiency, smart-grid investments, and grid hardening (which performed well in recent storms) support this positioning and top-decile reliability. Customer growth and capital investments are expected to be recovered in rates, but the framework aims to keep bills relatively low versus national averages even as Florida demand rises.Investor.nexteraenergy
For customers in other jurisdictions (and potentially Dominion customers post-combination), the deal includes commitments such as multi-year bill credits, shareholder-funded assistance, and workforce/supplier programs. Broader benefits from renewables, storage, and nuclear restarts could support long-term reliability and diversify the generation mix, though final rate outcomes depend on regulatory approvals, fuel costs, and capital recovery. Large-load frameworks are designed in some cases to shield existing customers from incremental costs of new industrial/data-center demand.
Check out the World’s Greatest Podcast Show Notes at EnergyNewsBeat.co or EnergyNewsBeat.com. And subscribe to: The Energy News Beat Substack.
Appendix: Sources and Links
- NextEra Energy Q3 2026 News Release (PDF): https://www.investor.nexteraenergy.com/~/media/Files/N/NEE-IR/reports-and-fillings/quarterly-earnings/2026/Q3%202026/2026-1021%20NEEQ32026News%20Release%20vFinal.pdf
- Seeking Alpha: “NextEra Energy tops Q3 earnings estimates, reaffirms full-year guidance” – https://seekingalpha.com/news/4655431-nextera-energy-tops-q3-earnings-estimates-reaffirms-full-year-guidance
- Zacks: “NextEra Energy Q3 Earnings Beat on FPL Strength, Revenues Miss” – https://www.zacks.com/stock/news/3012019/nextera-energy-q3-earnings-beat-on-fpl-strength-revenues-miss
- Markets Daily / earnings call coverage: https://www.themarketsdaily.com/2026/10/21/what-nextera-energy-nee-said-on-its-q3-earnings-call.html
- Motley Fool earnings call transcript summary: https://www.fool.com/earnings/call-transcripts/2026/10/21/nextera-energy-nee-q3-2026-earnings-call-transcript/
- 24/7 Wall St. results and reaction: https://247wallst.com/companies/nee/earnings/
- GuruFocus Q3 highlights: https://www.gurufocus.com/news/9135319/nextera-energy-inc-nee-q3-2026-earnings-call-highlights-adjusted-eps-climbs-97-as-backlog-swells-to-367-gw
- StockTitan 8-K summary: https://www.stocktitan.net/sec-filings/NEE/8-k-nextera-energy-inc-reports-material-event-4e515db776ea.html
- TipRanks earnings call signals: https://www.tipranks.com/news/company-announcements/nextera-energy-earnings-call-signals-strong-growth-path
- MarketScreener / Dow Jones coverage: https://www.marketscreener.com/news/nextera-3q-net-up-co-sees-26-adjusted-eps-at-high-end-of-view-ce785cd9d88af225
- Seeking Alpha earnings call transcript page: https://seekingalpha.com/article/4955945-nextera-energy-inc-nee-q3-2026-earnings-call-transcript
- Analyst rating updates and pre-earnings notes (Barclays, BMO, Morgan Stanley, Jefferies, etc.): Various MarketBeat, TipRanks, and Markets Insider reports from mid-October 2026.
- Stock price data (close $78.28 on Oct. 21, 2026): MarketWatch, StockAnalysis, Macrotrends, and related sources.
- FPL rate plan and bill comparisons (prior settlements and company statements on ~2% annual increases and below-national-average positioning): Company releases and coverage from 2025–2026 rate case materials.
This summary is based on the company’s October 21, 2026 news release and contemporaneous reporting. Investors and consumers should review the full release, SEC filings (including the Form 8-K and any Form S-4/proxy materials related to the Dominion transaction), and official rate case documents for complete details, reconciliations, and risk factors.