
October’s Commodity Markets Outlook lifted Brent to $91 for 2026 and marked European gas up 27%. It also cut Henry Hub, the one energy forecast that fell. The stage of the gas business that Africa’s offshore fields most need is the one stage the Bank’s lending rules still bar.
By Energy News Beat | Oct. 28, 2026 | Commodity Markets Outlook released 8:30 a.m. CT
The World Bank raised the price of energy on Wednesday morning. Its lending rulebook did not move at all. Both facts are official, both are current, and the distance between them is the story.
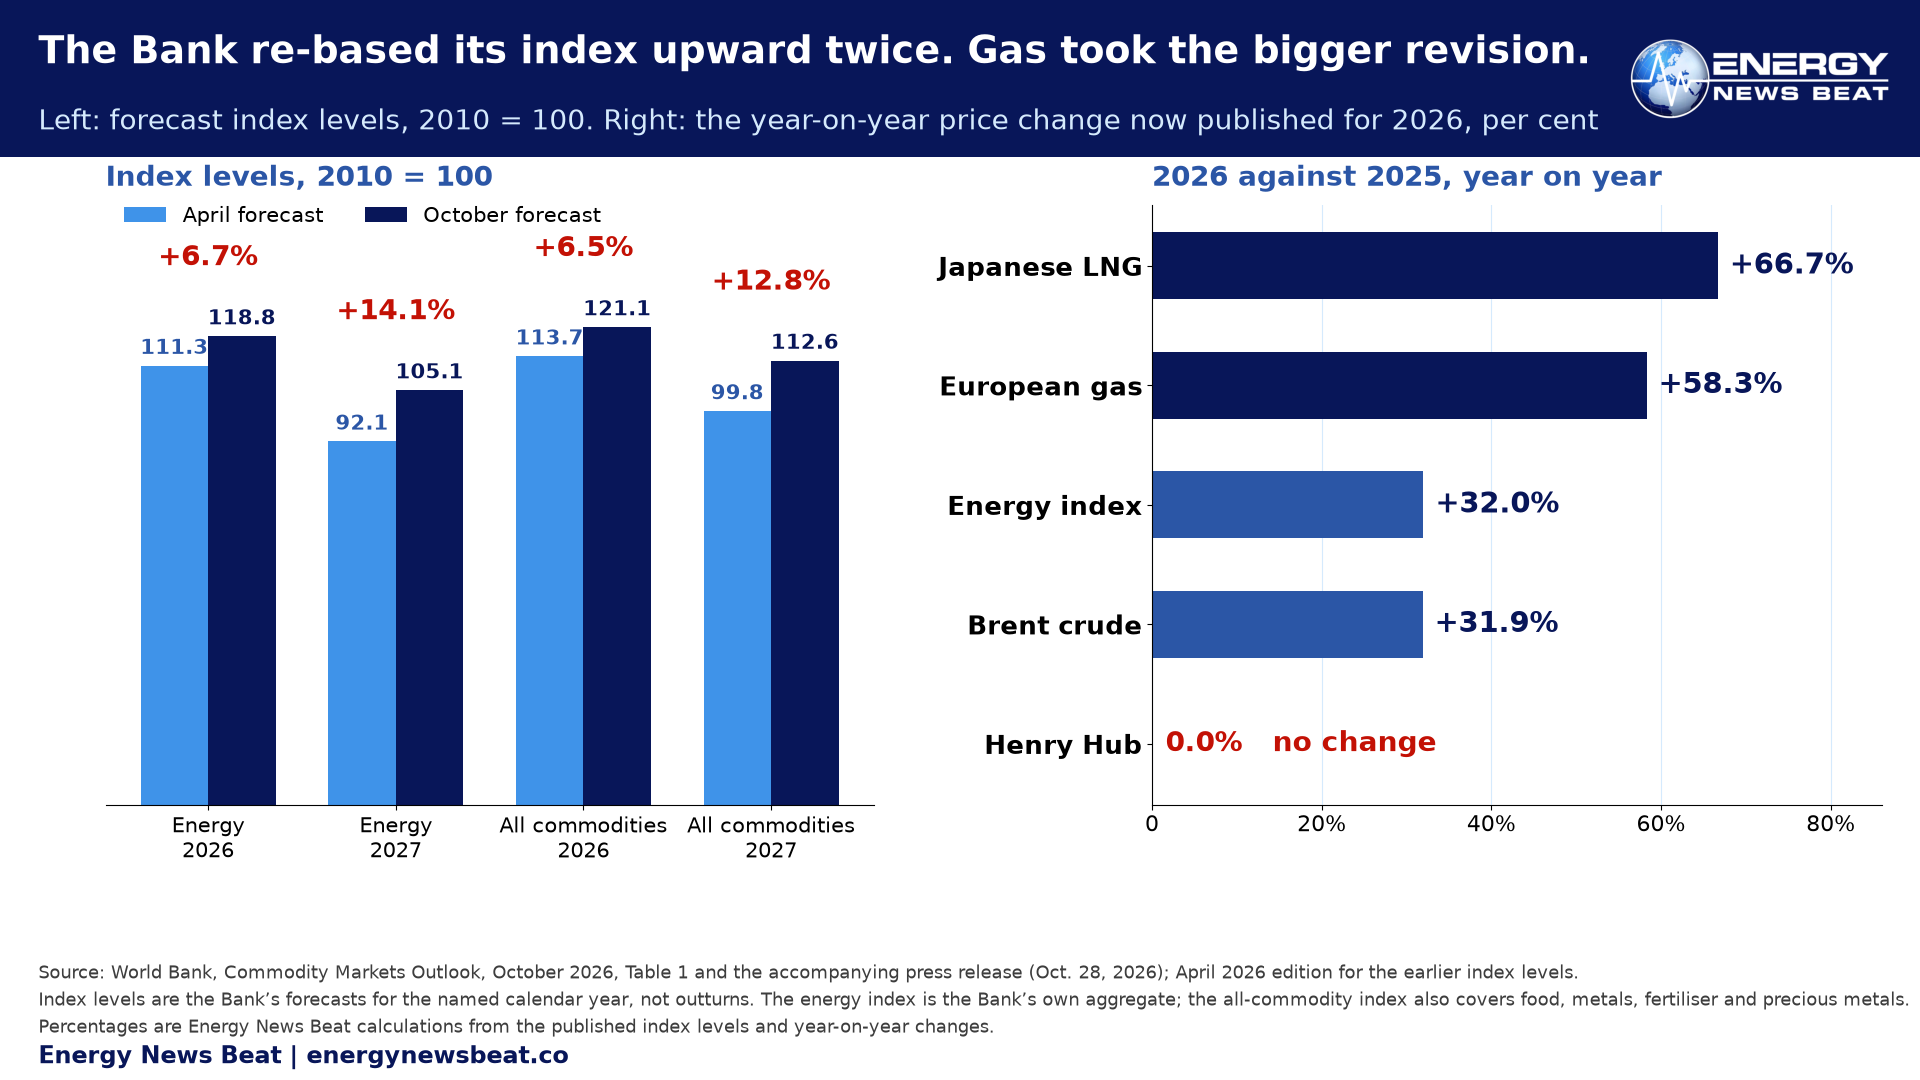
The October Commodity Markets Outlook sees energy 32% higher in 2026 than in 2025, up from the 24% projected in April. Brent goes to $91 a barrel from $86 in the April table, and to $79 for 2027 from $70. European gas to $19 per million Btu from $15, then $17.50 from $12.00. Japanese LNG to $20 from $16, then $18 from $13. The energy index was re-based from 111.3 to 118.8 and from 92.1 to 105.1, lifts of 6.7% and 14.1%.
The whole complex moved: commodities up 23%, food up 10% then 7%, metals up 25% to a new high. “Higher energy costs and trade disruptions are driving up prices across a broad range of commodities, threatening to worsen inflation, food insecurity, and economic growth,” said Ayhan Kose, the Bank’s deputy chief economist. Bloomberg’s headline was “World Bank Raises Commodity Price Outlook Citing War and El Niño”; the article is paywalled, so we cite the report and the headline as a headline.
The one forecast that went down
Henry Hub, the U.S. benchmark, was cut: $3.50 per million Btu for 2026, down from $3.80, and $3.70 for 2027, down from $4.00. That is a 7.9% cut and a 7.5% cut inside a document that raised its energy index by 6.7% and 14.1%. Every other fuel line in Table 1 went up. The U.S. gas line is the only one pointing down.
That is not noise but a forecast of a split market: crude and seaborne gas, the molecules that cross an ocean, priced for disruption; U.S. gas, moved mostly by pipeline inside North America, priced for abundance. Japan at $20 against Henry Hub at $3.50 is that split in one table.
For consumers, the bill starts at the barrel
The revisions that reach a household are the gas ones. European gas at $19 and then $17.50 is a 26.7% and then a 45.8% mark-up on April, the line behind a German heating bill and behind any power bill where gas sets the marginal price. Japanese LNG at $20 and $18, up 25.0% and 38.5%, is Asia’s cost of electricity. Brent at $91 is the pump, the freight surcharge and the fertiliser input at once.
Then the exception. If you heat with gas in the United States, the Bank just told you the thing you buy will be cheaper than it thought in April. Genuinely good news in a bad-news document.
It does not travel. Henry Hub is a pipeline price at a Louisiana interchange; those molecules reach a power plant in Abidjan only after being liquefied, shipped and regasified, each step carrying its own risk premium.
One more number. September Brent spot averaged $116.80 against a $91 full-year forecast, the gap being what is already banked at lower prices plus an assumed de-escalation. The Bank’s adverse case is Brent at $105 for 2027.
For investors, the trade is gas, not crude
- Gas is the bigger half of this revision: European gas for 2027 marked up 45.8%, Japanese LNG 38.5%, Brent 12.9%. Henry Hub is the decoupling signal, since importer risk and exporter margin both live in the widened Henry Hub-to-LNG spread.
- Both halves of the oil balance moved: supply down 5.2% in 2026, “the largest drop in more than four decades outside the 2020 global recession,” and consumption down 2.5%, “the third-largest annual contraction on record, after 2020 and 1980,” per the release.
- The downside case is a number, not a mood: Brent at $105 in 2027 with food 12% above baseline, against $50 billion to $60 billion the Bank says is available through existing instruments. None of this is investment advice.
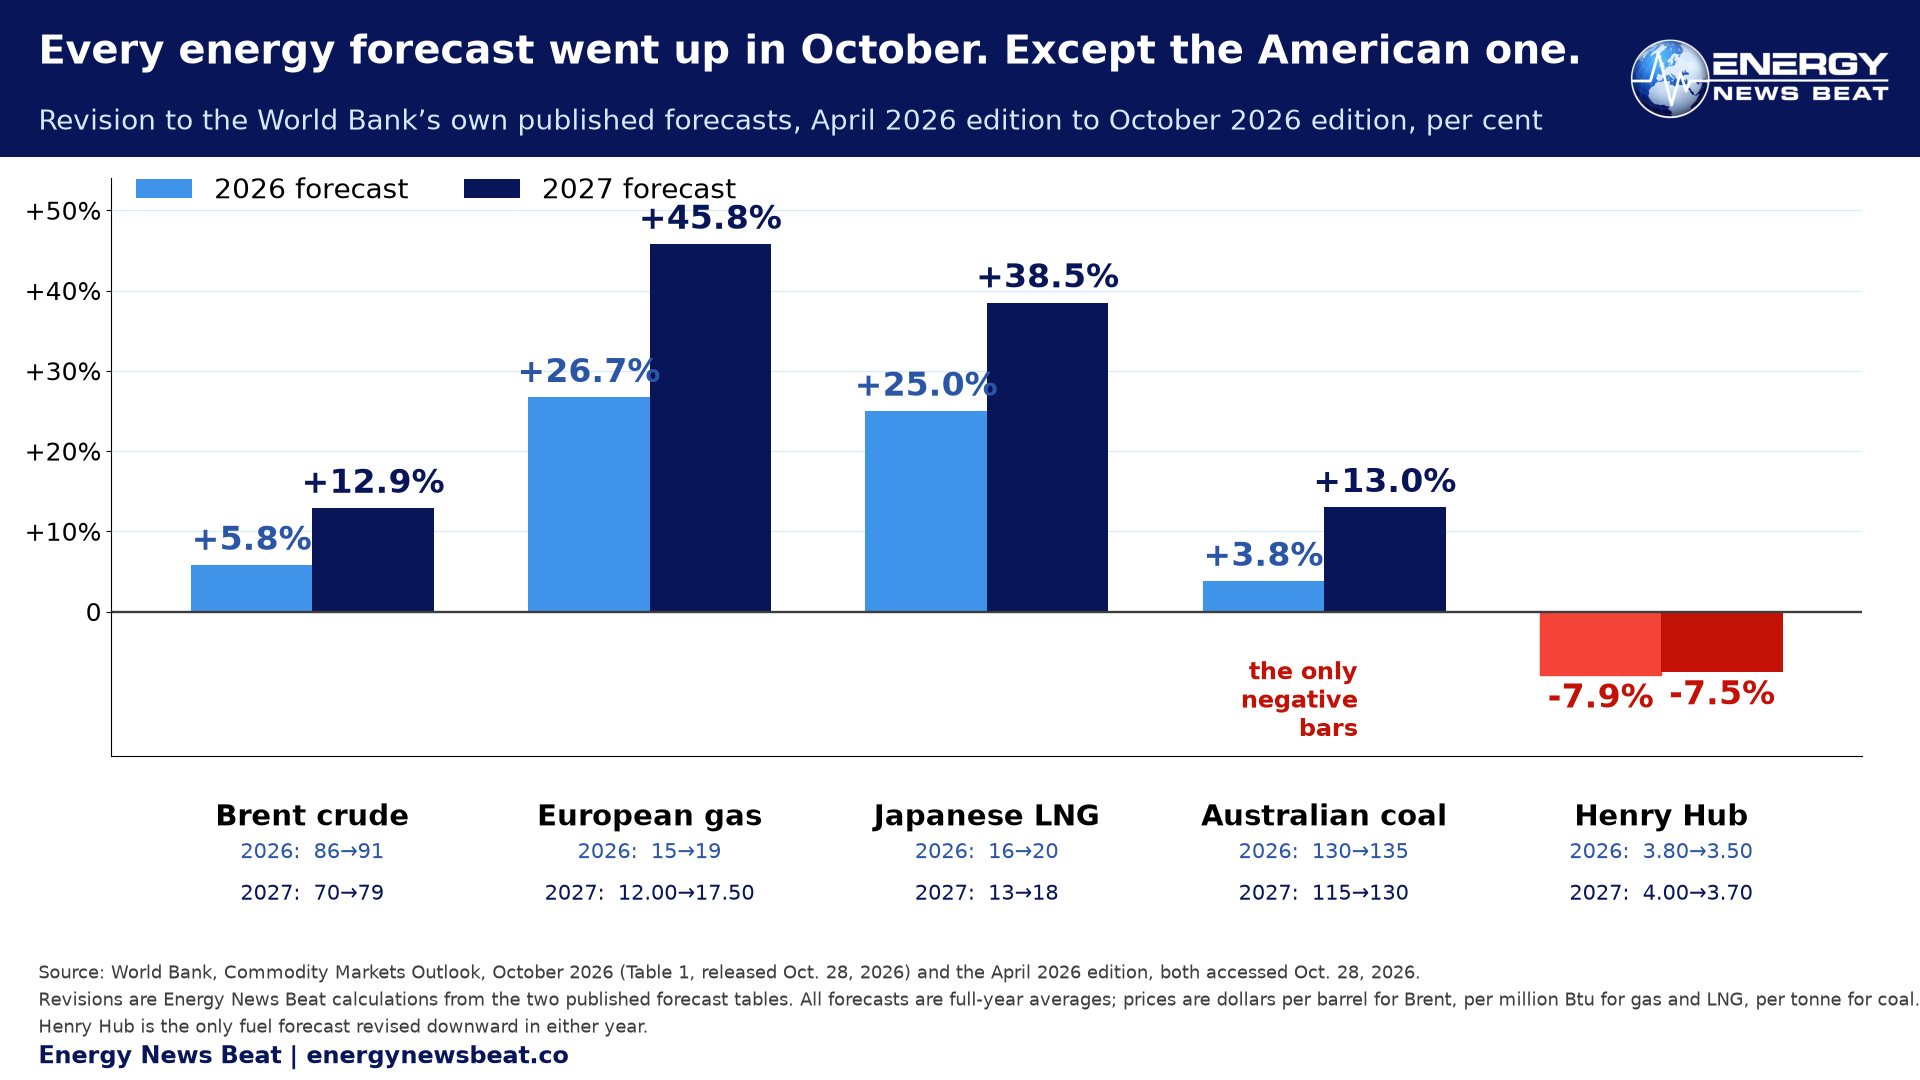
Chart 2. Left: the Bank re-based its index forecasts upward in both years, for energy and for the whole commodity complex, with 2010 equal to 100. Right: the year-on-year price changes the Bank now publishes for 2026, by commodity group. Sources: World Bank, October 2026 and April 2026 forecast tables and the October 2026 press release.
The Bank will fund the pipe and the plant. Not the well.
The rule is older than most of the commentary about it. It dates to December 12, 2017, when the Bank said it would stop financing upstream oil and gas after 2019, and that remains the operative policy. There was no 2025 announcement ending fossil finance. In June 2025 the Board lifted the nuclear ban and stayed split on upstream gas; in June 2026 it extended the Climate Change Action Plan and retired its 45% climate co-financing target and a separate 35% target. Three events, routinely collapsed into one.
The bar is narrow. Upstream means exploration, drilling and operating wells. Oil is out; gas is permitted “in exceptional circumstances … in the poorest countries where there is a clear benefit in terms of energy access for the poor,” where the project fits the country’s Paris commitments. Everything below the wellhead is open, in the Bank’s own words: “We will continue to support and finance midstream and downstream natural gas investments for transport and distribution to consumers and for power generation.” No new coal plant has been financed since 2010, per the Bank’s energy topic page. We could not find one confirmed use of that gas exception, an absence of evidence rather than a documented refusal.
What we did find is the pipe and the plant. PRIME-GAS, approved June 29, 2026, is $140 million of IDA money for Côte d’Ivoire, Benin and Togo to coordinate LNG imports and write Gas Master Plans. It produces no gas. IFC’s Central Térmica de Temane in Mozambique, 450 megawatts for about $624 million, is a gas-fired generating plant, which is the part of the chain the rule never barred. Its fuel comes from the Temane and Pande fields, which IFC has held a stake in since 2006, before the 2019 cutoff.
Set those against the upstream. Tanzania’s Mission 300 compact puts gas and LNG at the center of the plan while its $42 billion LNG project goes unsigned. Mozambique holds about 100 trillion cubic feet and the Bank aims to put $6 billion into the country over five years, and we found no Bank or IFC money in the upstream project itself.
The Bank is not the most pro-gas voice here. Its Mission 300 partner is. Wale Shonibare of the African Development Bank: “When the sun is not shining, what happens? So you need baseload that will be there all the time.” And Mission 300’s own FAQ answers directly: “Does Mission 300 support gas to power generation? Yes.” That is the Bank’s page, not a critic’s paraphrase, and it cuts against the simplest version of this story: the Bank funds the terminal, the pipeline, the plant and the reform program, and declines to fund the well.
The pressure to change that is public. On October 14 Treasury Secretary Scott Bessent told the Bank it “should formally retire its prohibition on financing upstream gas and oil.” Two days later in Bangkok, President Ajay Banga described an approach “balanced by design … gas where appropriate.” No formal change has been announced.
In a September interview on this program, the African Energy Chamber’s executive chairman, NJ Ayuk, made the case that Africa should stop exporting raw resources and instead build refining capacity and use its gas to power data centers. The episode summary records his argument that the World Bank’s refusal to finance fossil fuel projects is ideological rather than a judgment about bankability.
Two speeches in Moscow, and one of them is better
The case was made twice in Moscow on October 27, at the plenary of the 8th Gas Exporting Countries Forum summit. Vladimir Putin, replying to Mohamed Menfi of Libya’s Presidential Council with the presidents of Mozambique and Equatorial Guinea in the room, argued from history: “It was on coal, on hydrocarbons, that the economy of today’s Europe was raised up.” Then, of the advice developing countries now get, “Is that fair?” He said hydrocarbons, not coal, gas and oil separately, and developing countries, not Africa.
The sharper line came from an African head of state in the same room. President Daniel Chapo of Mozambique: “Africa cannot remain a country that gives light to other countries while its own citizens live in darkness.”
The numbers that make the case
655 million people worldwide had no electricity in 2024, more than 560 million of them in sub-Saharan Africa, about 86%. 970 million there cook without clean fuel, heading to a billion by 2027, and household air pollution killed 2.9 million people in 2021, on WHO estimates. Sub-Saharan Africa used 380 kilowatt-hours per person in 2024 against a world average of 3,708, about a tenth, and down from 407.9 in 2019. Per-capita consumption has fallen over the past twenty years while the population roughly doubled, as the International Gas Union and Hawilti put it.
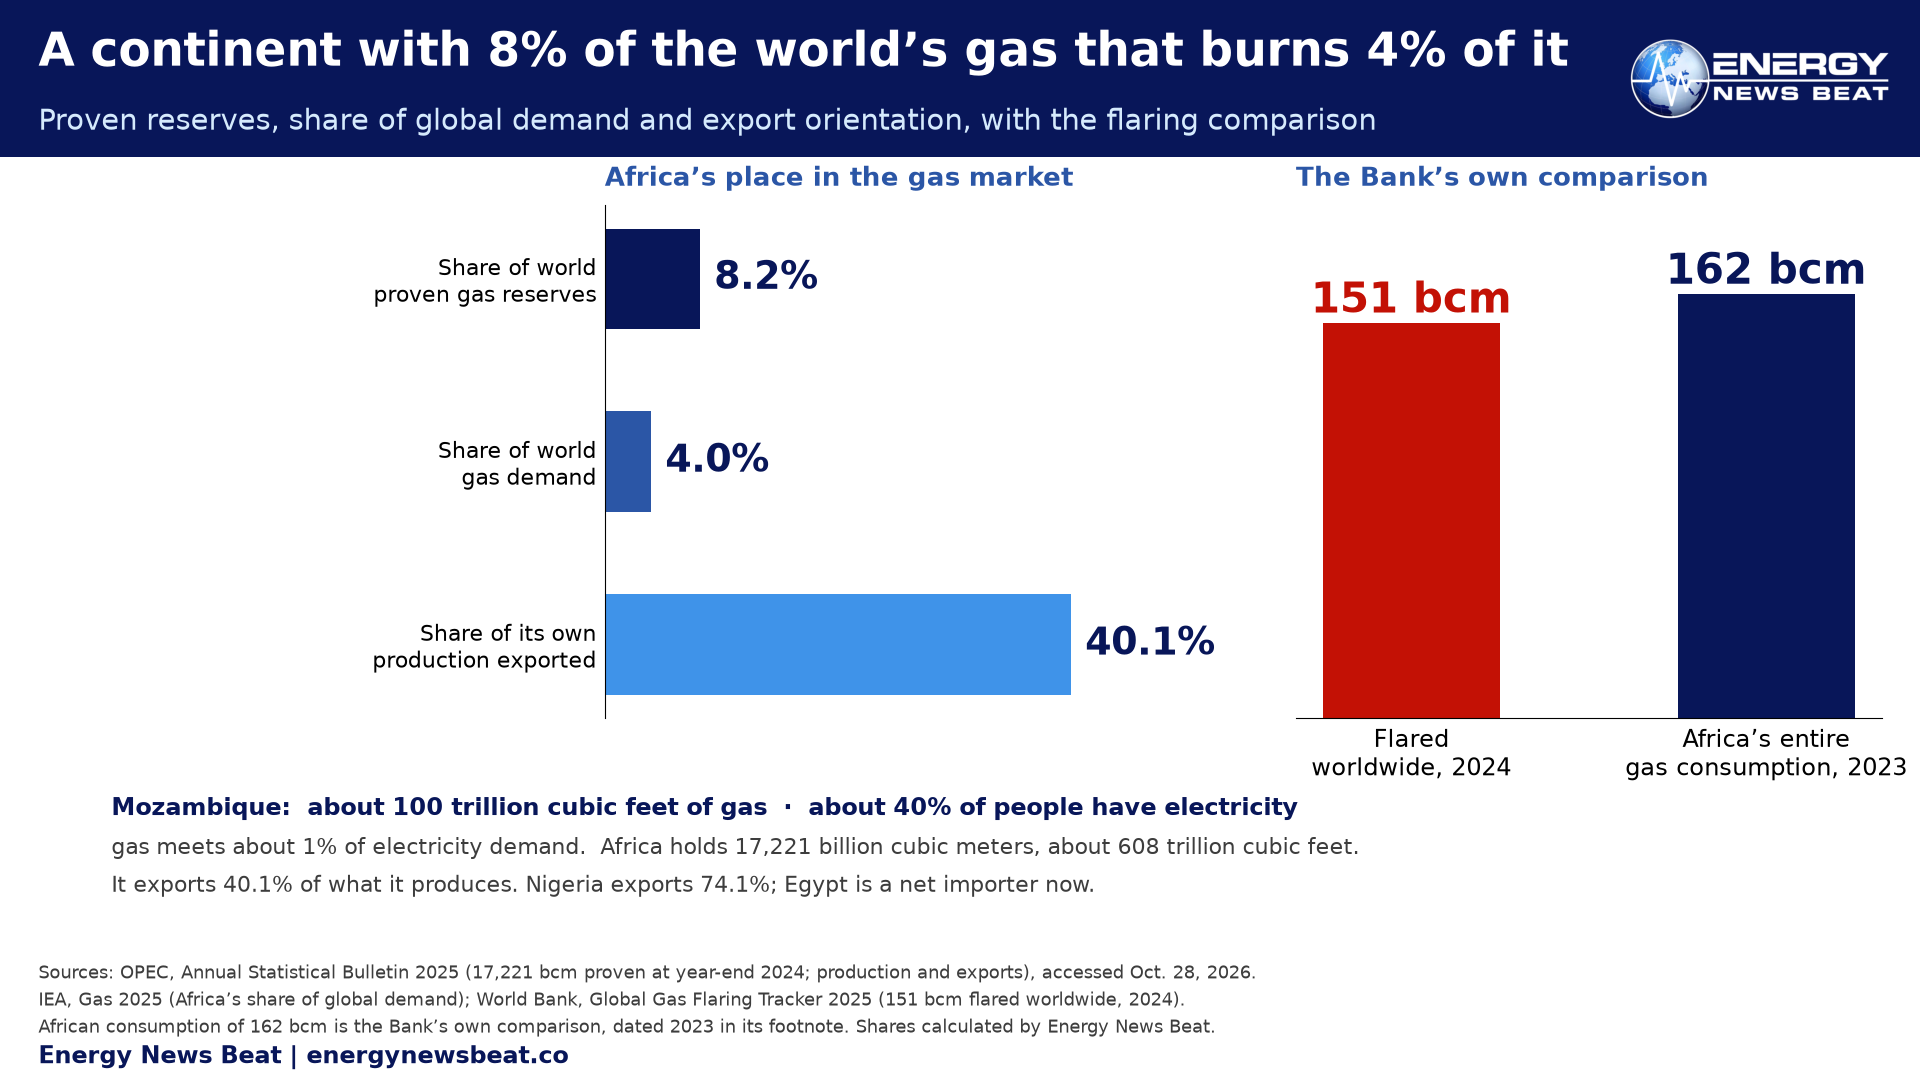
Africa holds 17,221 billion cubic meters of proven gas, about 608 trillion cubic feet and 8.2% of the world total, on the OPEC Annual Statistical Bulletin 2025, the aggregation used here; other compilations say nearer 13%. It exports 40.1% of what it produces, on our arithmetic from OPEC’s production and export tables. Nigeria exports 74.1%. Egypt is a net importer now: nil on OPEC’s total gas export measure, and 9.2 million tonnes of LNG brought in during 2025. Africa burns about 4% of the world’s gas, and the IEA expects about 4% in 2030. The Bank’s own tracker counted 151 billion cubic meters flared worldwide in 2024, “almost equivalent to the total annual gas consumption in Africa, 162 bcm” — a comparison the report’s own footnote dates to 2023.
Then Mozambique. About 100 trillion cubic feet of gas, roughly 40% of people with electricity access, and gas meeting about 1% of electricity demand.
Caveats, in fairness
- Emissions and stranded assets. Developing Africa’s discovered but unapproved gas would add about 10 gigatonnes of CO2 over 30 years, roughly 3.5% of world emissions: small against the global total, and not zero. Recourse’s Rajneesh Bhuee calls it “a resource that in the next 10 to 15 years will no longer have a market.”
- Europe’s gas station. “There is no country on the continent that you can point out and say that has invested in gas that is using that gas for local consumption,” Bhuee says. Nigeria’s 74.1% export share supports him; Algeria, which consumes about half of what it produces, does not.
- Bad economics. Sunil Acharya of Recourse, in a coalition statement: “Fossil gas is bad economics, it exposes countries to volatile global markets and debt while locking public resources into costly infrastructure.” Imported LNG is now projected to cost 45.8% more in 2027 than the Bank thought six months ago.
- Nigeria recorded 222 grid collapses between January 2010 and June 2022, and the region’s debt-to-GDP roughly doubled to about 60% between 2013 and 2022. More gas does not repair a transmission system, a tariff that does not recover cost, or a utility that cannot bill.
- Tariffs are not the problem, and this is where a popular version of the argument fails. Africa’s average residential price is $0.141 a kilowatt-hour, less than half Europe’s $0.260 and well under the world average of $0.179. Asia is cheaper again at $0.088, and that is the point: the tariffs are low and the lights are still off. The defensible claim is cost against income: CSIS puts the region’s electricity cost at 3,188% of income per capita, the highest of any region. The barrier is the connection, the reliability and the household budget.
| STU’S TAKE
Opinion. Every number is linked to its source. This is my opinion, so take it as such. The Bank raised its energy forecast by 32% for 2026 and cut Henry Hub by 7.9% in the same document. Read those two lines together and you have the whole argument about who gets to develop and who gets to import. Africa holds 608 Tcf of proven gas, burns 4% of the world’s gas, exports 40.1% of what it produces, and 560 million of its people have no electricity. Mozambique sits on 100 Tcf with 40% access. That is not a market failure. It is a policy outcome, and the policy is eight years old. I have argued for years that you cannot run a grid on an assumption about the weather. The AfDB’s Wale Shonibare says it better than I do: “When the sun is not shining, what happens?” The World Bank’s own Mission 300 FAQ answers yes to gas for power. So the money goes to the terminal and the plant and not to the well. Somebody should have to explain why an LNG importer in West Africa is a safer bet than a producer next door. The other side is real and I will not pretend otherwise. Gas is a fossil fuel, the stranded-asset case is serious, and LNG has just been repriced upward for the second time this year. But a country at 380 kWh per person is not the country that needs to hear that first. The Bank says gas “where appropriate.” The Treasury says retire the ban. Both are describing the same gap, and nobody has closed it. Honestly, the European, and some U.S. leaders energy hypocrisy makes me sad, sick and angry all in the same breath. We need to encourage development of African’s energy resources for Africans to improve their lives, economies and become bigger trading partners. We all win when we all grow together.
|
-
Check out the World’s Greatest Podcast Show Notes at EnergyNewsBeat.co or EnergyNewsBeat.com. And subscribe to: The Energy News Beat Substack.
Appendix
Sources, excerpts, data tables and methodology notes for “World Bank Raised the Price of Energy. Its Rules Keep Africa’s Gas in the Ground.”
A. Sources (all accessed Oct. 28, 2026 unless stated)
- World Bank, “Commodity Markets Outlook: October 2026” press release, published Oct. 28, 2026
- World Bank, Commodity Markets Outlook October 2026, Table 1 (forecast table, PDF)
- World Bank, Commodity Markets Outlook April 2026, Table 1 (forecast table, PDF), for all revisions
- World Bank, Commodity Markets Outlook October 2026, Pink Sheet (monthly spot prices, September 2026 averages)
- World Bank Group, “World Bank Group announcements at One Planet Summit,” Dec. 12, 2017
- World Bank, “Q&A: The World Bank Group and Upstream Oil and Gas” (explains the 2017 commitment and its exception)
- World Bank Group, “Update on the World Bank Group Climate Change Action Plan,” June 29, 2026
- World Bank, Energy topic page (states that the Bank has not financed a new coal plant since 2010)
- World Bank Group, Mission 300 energy compacts FAQ, “Energizing Africa”
- World Bank, “Gas market development to lower energy costs, create jobs, unlock private investment” (PRIME-GAS), July 20, 2026
- IFC disclosure, Central Térmica de Temane project (Mozambique), project 43099
- World Bank / Mission 300, Tanzania Energy Access and Energy Sector Compact, 2026
- Reuters, “Tanzania expects to sign $42 billion mega LNG project before June, minister says,” Jan. 26, 2026
- Reuters, “World Bank aims to give Mozambique $6 billion financing over next five years,” Feb. 23, 2026
- S. Department of the Treasury, press release sb0659, Oct. 14, 2026
- World Bank Group President Ajay Banga, remarks at the 2026 Annual Meetings plenary, Oct. 16, 2026
- Climate Home News, “Under US pressure, World Bank says it will back gas ‘where appropriate’,” Oct. 16, 2026
- Reuters, “World Bank to end ban on nuclear energy projects, still debating upstream gas,” June 11, 2025
- World Bank, “Accelerating Universal Energy Access” (Tracking SDG 7 launch), June 24, 2026
- IEA, IRENA, UNSD, World Bank, WHO, Tracking SDG 7: The Energy Progress Report 2026 (PDF)
- World Bank World Development Indicators, EG.USE.ELEC.KH.PC, access to electricity and per-capita consumption series
- OPEC, Annual Statistical Bulletin 2025 (proven gas reserves at year-end 2024; production and exports)
- IEA, Gas 2025 (Africa’s share of global gas demand, to 2030)
- IEA, Africa Energy Outlook 2022 (Africa home to “13% of the world’s natural gas and 7% of the oil resources”)
- GIIGNL, Annual Report 2026 (LNG trade, 2025)
- World Bank, Global Gas Flaring Tracker Report, July 2025 (2024 flaring data)
- International Gas Union, “Gas for Africa” report, 2025 edition
- CSIS, “Achieving Universal Energy Access in Africa Amid Global Decarbonization,” Jan. 31, 2024
- com, electricity prices by country and continent, Q3 2026
- Bloomberg, “World Bank Raises Commodity Price Outlook Citing War and El Niño,” Oct. 28, 2026 (headline only; article paywalled)
- President of Russia, transcript of the 8th Gas Exporting Countries Forum plenary, Oct. 27, 2026 (Russian)
- President of Russia, English-language page for the same event (abridged; omits the passage quoted below)
- TASS, report on Putin’s remarks to the GECF summit, Oct. 27, 2026
- Energy News Beat, “Africa’s Energy Moment: From Poverty to Abundance,” Conversations in Energy with Stu Turley, published Sept. 30, 2026
- Climate Home News, “Civil society groups push back on fossil gas funding as African Development Bank meets,” May 30, 2025
- Big Shift Global coalition, “Climate and energy crises bite as Bangkok World Bank meetings stay silent,” October 2026
- World Health Organization, “Household air pollution and health” fact sheet (2.9 million deaths, 2021)
Sources consulted but not cited in the body, retained here for transparency: E3G bank metrics on fossil-fuel exclusion policies; Oil Change International factsheet, October 2026; African Energy Chamber statement on the upstream financing ban; Business Insider Tanzania, Deputy Prime Minister Doto Biteko on using Africa’s own resources; Global South World, on the Putin passage; NANGS, Russian report on the same passage; and the World Bank gas flaring press release of July 18, 2025.
B. Key primary-document excerpts and translation notes
B1. The Bank’s 2017 commitment and its gas exception
“no new investments in upstream oil and gas would be undertaken after 2019, unless under exceptional circumstances” Link
“We will continue to support and finance midstream and downstream natural gas investments for transport and distribution to consumers and for power generation” Link
The exception the Bank describes applies “in the poorest countries where there is a clear benefit in terms of energy access for the poor,” and only where the project is consistent with the country’s Paris Agreement commitments. Link
“Does Mission 300 support gas to power generation? Yes.” Link
“the World Bank Group should formally retire its prohibition on financing upstream gas and oil. The Bank cannot credibly invoke country ownership while categorically excluding upstream projects before their development merits are even assessed.” (Treasury Secretary Scott Bessent, Oct. 14, 2026) Link
“Our approach is balanced by design – a full mix of renewables, hydro, gas where appropriate, nuclear when it makes sense, transmission, grids, storage – the whole thing.” (President Ajay Banga, Bangkok, Oct. 16, 2026, as reported by Climate Home News) Link
“almost equivalent to the total annual gas consumption in Africa, 162 bcm.” (World Bank, Global Gas Flaring Tracker, on 151 bcm flared worldwide in 2024) Link
B2. Moscow, Oct. 27, 2026: the passage and why it circulates in translation
Vladimir Putin spoke at the plenary of the 8th Gas Exporting Countries Forum summit in Moscow on Oct. 27, 2026, replying to Mohamed Menfi, Chairman of Libya’s Presidential Council. The passage below is taken from the Kremlin’s Russian transcript. The Kremlin’s English-language page for the same event is abridged and does not carry it, which is why the remark circulates in third-party translation. The English rendering here is Energy News Beat’s own translation from the Russian and is labeled as such.
Russian (Kremlin transcript): «Именно на угле, на углеводородах поднималась экономика сегодняшней Европы. А когда определённый уровень достигнут, теперь наши коллеги в той же Европе другим странам, прежде всего развивающимся, говорят: “А вам нельзя использовать углеводороды”. Почему же им нельзя? А как им быть? А где взять инвестиции? Где взять технологии? Разве это справедливо?»
English (Energy News Beat translation): “It was on coal, on hydrocarbons, that the economy of today’s Europe was raised up. And when a certain level has been reached, now our colleagues in the same Europe tell other countries, above all developing countries: ‘You may not use hydrocarbons.’ Why may they not? What are they to do? Where are they to get investment? Where are they to get technology? Is that fair?”
What the passage does not say. He said hydrocarbons (углеводороды), not coal, gas and oil as three separately restricted fuels; coal appears in the historical framing of the European Union as an association of coal and steel. He addressed developing countries, not Africa, and did not single out African states. The remark was a floor speech at a gas-exporters’ forum, not a social-media post. The stronger African voice at the same plenary was President Daniel Chapo of Mozambique: «Африка не может оставаться страной, которая будет давать свет другим странам, в то время как её собственные граждане живут в темноте» — “Africa cannot remain a country that gives light to other countries while its own citizens live in darkness.”
B3. Disclosure
One of the sources cited in this article is our own program: “Africa’s Energy Moment: From Poverty to Abundance,” an interview hosted by Stu Turley and published by Energy News Beat on Sept. 30, 2026, so readers should know that Energy News Beat is not a neutral party to the argument that interview advances.
C. Data tables
C1. Forecast revisions, April 2026 edition to October 2026 edition (full-year averages)
| Series | Unit | Apr 2026 | Oct 2026 | Revision | Apr 2027 | Oct 2027 | Revision | Source |
| Brent crude | $/bbl | 86 | 91 | +5.8% | 70 | 79 | +12.9% | Table 1, April |
| European gas (TTF) | $/mmbtu | 15 | 19 | +26.7% | 12.00 | 17.50 | +45.8% | Table 1, April |
| Japanese LNG | $/mmbtu | 16 | 20 | +25.0% | 13 | 18 | +38.5% | Table 1, April |
| Australian coal | $/mt | 130 | 135 | +3.8% | 115 | 130 | +13.0% | Table 1, April |
| Henry Hub | $/mmbtu | 3.80 | 3.50 | −7.9% | 4.00 | 3.70 | −7.5% | Table 1, April |
| Energy index | 2010 = 100 | 111.3 | 118.8 | +6.7% | 92.1 | 105.1 | +14.1% | Table 1, April |
| All-commodities index | 2010 = 100 | 113.7 | 121.1 | +6.5% | 99.8 | 112.6 | +12.8% | Table 1, April |
Revisions are Energy News Beat calculations. All figures are full-year averages as published in the two forecast tables; there is no WTI forecast in the October 2026 outlook, and none is implied here. WTI appears in that edition only as a September 2026 spot average ($96.90) in the Pink Sheet.
C2. Africa’s gas in the world, year-end 2024
| Measure | Value | Share / note | Source |
| Africa proven gas reserves | 17,221 bcm (about 608 Tcf) | 8.2% of world on OPEC data | OPEC |
| Africa share of world gas demand | about 4% | IEA projection holds near 4% through 2030 | IEA |
| Africa share of its own production exported | 40.1% (ENB calc.) | Nigeria 74.1%; Egypt nil on total gas exports, a net LNG importer | OPEC |
| World gas flared, 2024 | 151 bcm | Bank: “almost equivalent” to African consumption | World Bank |
| Africa gas consumption | 162 bcm | The Bank’s comparison figure; the report’s footnote dates it to 2023, from the Energy Institute Statistical Review | World Bank |
| Mozambique reserves | about 100 Tcf | about 40% electricity access; gas about 1% of power | CSIS |
| Tanzania resource | 57 Tcf | discovered resource, not booked reserves; OPEC does not list Tanzania | see note C3 |
Reserve aggregation varies by compiler. OPEC’s Annual Statistical Bulletin 2025 puts Africa at 17,221 bcm, or 8.2% of the world total on our arithmetic. Other compilations put the African share higher, and they are not all measuring the same thing. IEA’s Africa Energy Outlook 2022 says the continent “is home to 13% of the world’s natural gas and 7% of the oil resources,” a resources measure; CSIS, on reserves, says Africa “now holds roughly 13 percent of the world’s natural gas reserves,” in its January 31, 2024 analysis; and The Economist used the same 13% on July 18, 2023. BP’s Statistical Review, now published by the Energy Institute, put Africa at 7.8% of world proved gas reserves in its 2007 edition, and its 2023 edition carries no