
Energy News Beat | November 9, 2026
Strathcona Resources Ltd. (TSX: SCR) has agreed to acquire all outstanding shares of Greenfire Resources Ltd. (TSX: GFR; NYSE: GFR) in a cash-and-stock transaction valued at approximately C$2.7 billion to C$2.9 billion, including Greenfire’s roughly C$550 million in net debt as of September 30, 2026.Strathconaresources The deal, announced November 8, 2026, will combine two complementary thermal oil sands and heavy oil producers under common control by Waterous Energy Fund (WEF), creating what the companies describe as Canada’s only pure-play oil sands operator without natural gas or downstream operations, the fourth-largest SAGD operator in the country, and the holder of the longest 2P reserves life index among publicly traded Canadian companies.Strathconaresources
Greenfire shareholders may elect either 0.25 Strathcona shares per Greenfire share (valued at C$9.09, a 15% premium to Greenfire’s November 6, 2026 closing price) or C$11.00 in cash (a 39% premium to the same close and 26% to the 30-day VWAP). Neither option is subject to proration.Strathconaresources WEF, which holds about 72% of Greenfire and 57% of Strathcona, has agreed to support the deal and will elect the share option, resulting in expected ownership of 60–64% of the pro forma company. Depending on elections by other shareholders, Strathcona anticipates issuing 43–60 million shares (17–22% of the pro forma equity) and paying up to approximately C$740 million in cash.Strathconaresources
The combined entity is expected to produce about 153,000 barrels per day on a 2026 year-to-date pro forma basis (Strathcona ~119 kbbl/d; Greenfire ~34 kbbl/d, including the recent Connacher/Great Divide acquisition). Both companies target 11–12% compound annual production growth over five years through drilling to fill existing facilities and brownfield expansions, taking combined output toward roughly 260 kbbl/d by 2031. Proved plus probable (2P) reserves exceed 3.0 billion barrels, equating to a 54-year reserves life index—approximately 20 years longer than any other publicly traded Canadian company.Strathconaresources
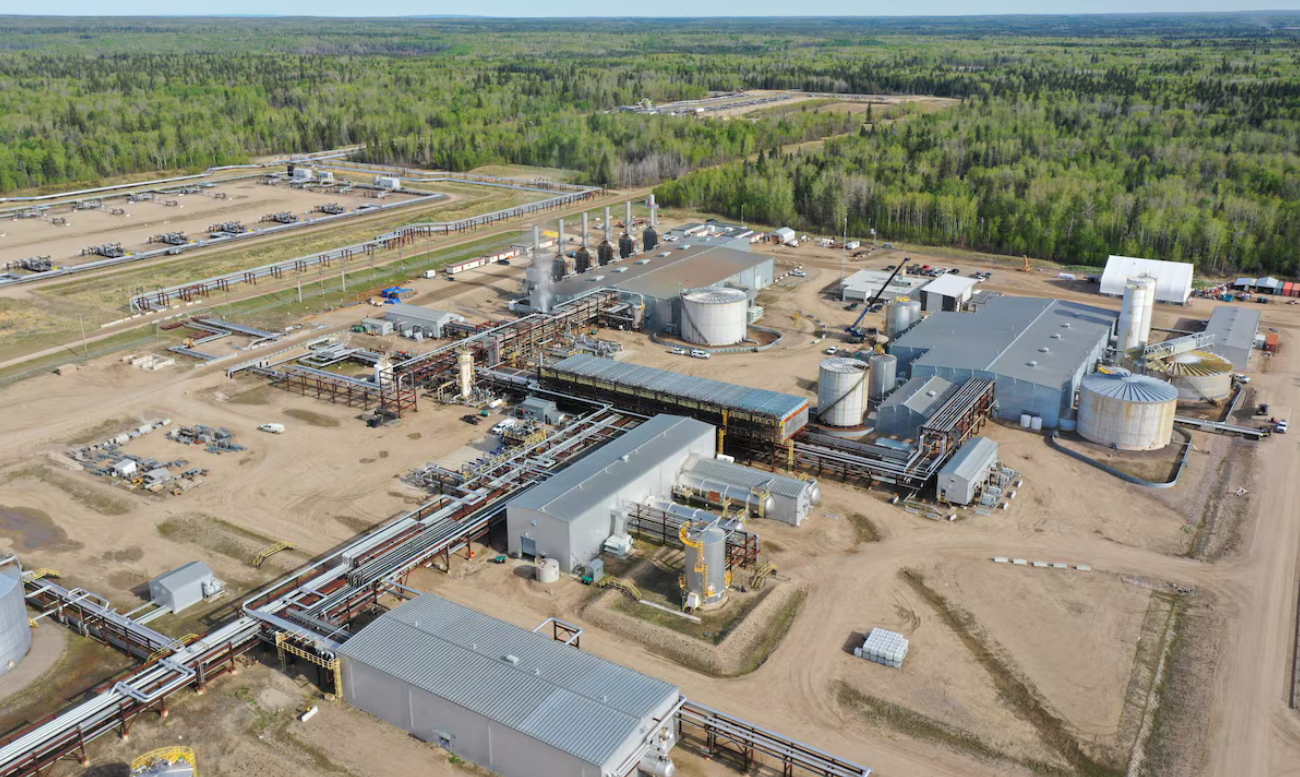
Greenfire’s Athabasca thermal assets (Hangingstone Expansion at 75% working interest, Hangingstone Demo at 100%, and Great Divide at 100% following the August 2026 Connacher acquisition) will form a new semi-autonomous business unit, SCR Central Athabasca, led by Greenfire President Colin Germaniuk. This joins Strathcona’s existing units in Cold Lake, Lloydminster Thermal, and Lloydminster Conventional, giving the combined company operations across the Athabasca, Cold Lake, and Lloydminster deposits and the McMurray, Clearwater, and Mannville formations.Strathconaresources
Expected benefits include approximately C$75 million in annual run-rate synergies within one year (lower borrowing costs, procurement efficiencies, and elimination of duplicate public-company costs), roughly C$400 million in cash tax savings over four years from Greenfire’s C$2.8 billion in tax pools (C$2.0 billion immediately deductible) that extend Strathcona’s cash tax horizon from 2027 to 2031 (at US$75/bbl WTI), and the prospect of an investment-grade credit rating within a year. The transaction is described as about 6% accretive to Strathcona’s year-end 2025 2P NAV per share and immediately accretive to free cash flow after sustaining capital; the share option is about 3% accretive to Greenfire’s 2P NAV.Strathconaresources
Shareholder meetings are expected in January 2027, with closing shortly thereafter subject to customary approvals (including two-thirds votes, minority approval under MI 61-101, court, TSX, and Competition Act). Greenfire shares will delist from the TSX and NYSE; Strathcona will not list on the NYSE.Strathconaresources
Implications for Canadian Oil Sands Production
The transaction is primarily a consolidation of complementary long-life thermal assets rather than an immediate large addition of new barrels. It positions a mid-sized pure-play operator with a clearer growth runway (11–12% CAGR targets via brownfield and facility-fill work) at a time when the broader oil sands sector is expected to continue growing mainly through optimization of existing facilities.
S&P Global Energy forecasts Canadian oil sands production averaging a record 3.5 million barrels per day in 2026 (up ~100 kbbl/d or 3% from 2025) and rising toward 3.9 million bbl/d by the early 2030s, with most near-term gains from optimizations and brownfield expansions rather than large greenfield projects. Analysts note potential upside of nearly 500,000 bbl/d if investment conditions improve and previously deferred projects advance.Oilandgas360 Pipeline capacity is also viewed as supportive: Enverus Intelligence Research has indicated that planned expansions and optimizations could support 2–3 million bbl/d of Western Canadian production growth into the late 2030s, with takeaway capacity remaining ahead of needs for much of the next decade and WCS differentials expected in a more stable range.Worldoil
By combining scale, shared operational learnings across SAGD business units, improved capital access, and a pure-play structure, the enlarged Strathcona is better positioned to execute its organic growth plans and potentially accelerate longer-term opportunities (including areas such as Plover Lake, Taiga, Glenbogie, Selina, Muriel Lake, Corner, and Chard beyond 2031). In a sector that has seen significant consolidation among larger players (e.g., recent activity involving Cenovus and others), this deal further concentrates capable thermal operators while creating a dedicated mid-cap vehicle focused solely on long-life heavy oil.Strathconaresources
Broader policy developments—including ongoing discussions around fiscal terms, carbon pricing clarity, project-review streamlining under a Canada-Alberta memorandum of understanding, and Pathways Alliance carbon capture efforts targeting a potential late-2027 final investment decision—provide a more constructive backdrop than in prior years. The combined company can pursue growth within this environment with a stronger balance sheet and longer reserve life.
Implications for Consumers
For consumers (primarily of refined products in North America and, increasingly, export markets), the deal supports continued reliable supply growth from a low-decline, long-life resource base. Oil sands production is characterized by high upfront capital intensity but very low decline rates once online, contributing to stable North American heavy crude availability.
Stable or modestly growing oil sands volumes, combined with improved pipeline egress, tend to moderate extreme discounts for Western Canadian Select (WCS) versus WTI over time, which can help keep feedstock costs more predictable for refiners configured for heavy crude (particularly in the U.S. Midwest and Gulf Coast). This can support more stable gasoline, diesel, and other refined product pricing relative to scenarios of constrained Canadian supply. The pure-play focus and synergies may also improve operational efficiency and capital discipline, indirectly supporting competitive long-term supply.
No immediate large production surge is expected from the combination itself; the consumer-relevant impact is more about reinforcing the medium-term growth trajectory already embedded in industry forecasts (toward 3.9 million bbl/d oil sands) and reducing the risk of underinvestment in existing thermal assets.
Implications for Investors
For Greenfire shareholders, the cash option offers a substantial near-term premium (39% to the November 6 close), while the share option provides participation in a larger, more diversified, better-capitalized pure-play with improved liquidity, a longer reserve life, expected synergies, tax benefits, and a path toward investment-grade credit. Early market reaction reflected the premium, with Greenfire shares moving sharply higher in initial trading.Stocktitan
For Strathcona shareholders, the deal is framed as accretive to NAV and free cash flow, with material tax-pool benefits that defer cash taxes and lower expected borrowing costs. The enlarged company offers a clearer pure-play oil sands equity story with targeted double-digit production growth, a 54-year 2P reserves life, and operations spanning all major deposits. WEF’s decision to roll its Greenfire stake into shares signals continued long-term alignment from the controlling investor.
Risks include execution on synergies and growth, commodity price volatility (the tax-savings and accretion math references US$75/bbl WTI), integration of the semi-autonomous units, regulatory and shareholder approvals, and the usual oil-sands factors (steam-oil ratios, capital costs, differentials, and policy). The pure-play structure removes diversification into gas or downstream, which some investors may view as higher-beta exposure to heavy oil pricing and Canadian policy.
Overall, the transaction consolidates two complementary operators into a scaled pure-play with an extended growth runway at a time when the oil sands sector is demonstrating resilience through optimization and benefiting from improved infrastructure and policy signals. Closing is targeted for early 2027.
Appendix: Sources and Links
- Strathcona Resources Ltd. official announcement: Strathcona Resources Ltd. Announces Agreement to Acquire Greenfire Resources Ltd. (November 8, 2026)
- PR Newswire release: Strathcona Resources Ltd. Announces Agreement to Acquire Greenfire Resources Ltd.
- Bloomberg: Strathcona to Acquire Greenfire in Canadian Oil Sands Deal
- Reuters: Canada’s Strathcona to buy Greenfire in up to $2 billion deal
- The Globe and Mail: Strathcona to buy Greenfire Resources in up to $2.9-billion deal
- Credence Research summary: Strathcona Resources to Acquire Greenfire in C$2.9 Billion Oil Sands Consolidation Deal
- S&P Global Energy / related coverage: Canadian Oil Sands Production Expected to Grow for 25th Straight Year, Reaching New Record and Canadian oil sands production to hit record 3.5 MMbpd in 2026
- Enverus / World Oil on pipeline capacity: Canadian pipeline expansions could unlock 2–3 MMbpd of oil production growth
- Greenfire Resources company materials and Q3 2026 results (assets, production, Connacher acquisition): greenfireres.com and related releases
- Oil Sands Magazine facility and production references: oilsandsmagazine.com
- Additional coverage: Finimize, FairsOnline, Merger Monday, Stock Titan (market reaction notes), and company presentations referenced in the release.
Note: All deal terms, production figures, synergies, and strategic claims are drawn primarily from the companies’ joint announcement and supporting materials. Production forecasts for the broader sector are from independent analyst sources (S&P Global Energy, Enverus). This article is for informational purposes and does not constitute investment advice.