
The IEA’s November Oil Market Report, published Friday, says global balances point to a surplus in the fourth quarter of 2026. European diesel is still about 77% above pre-war levels, and U.S. pump diesel is still above $6 a gallon.
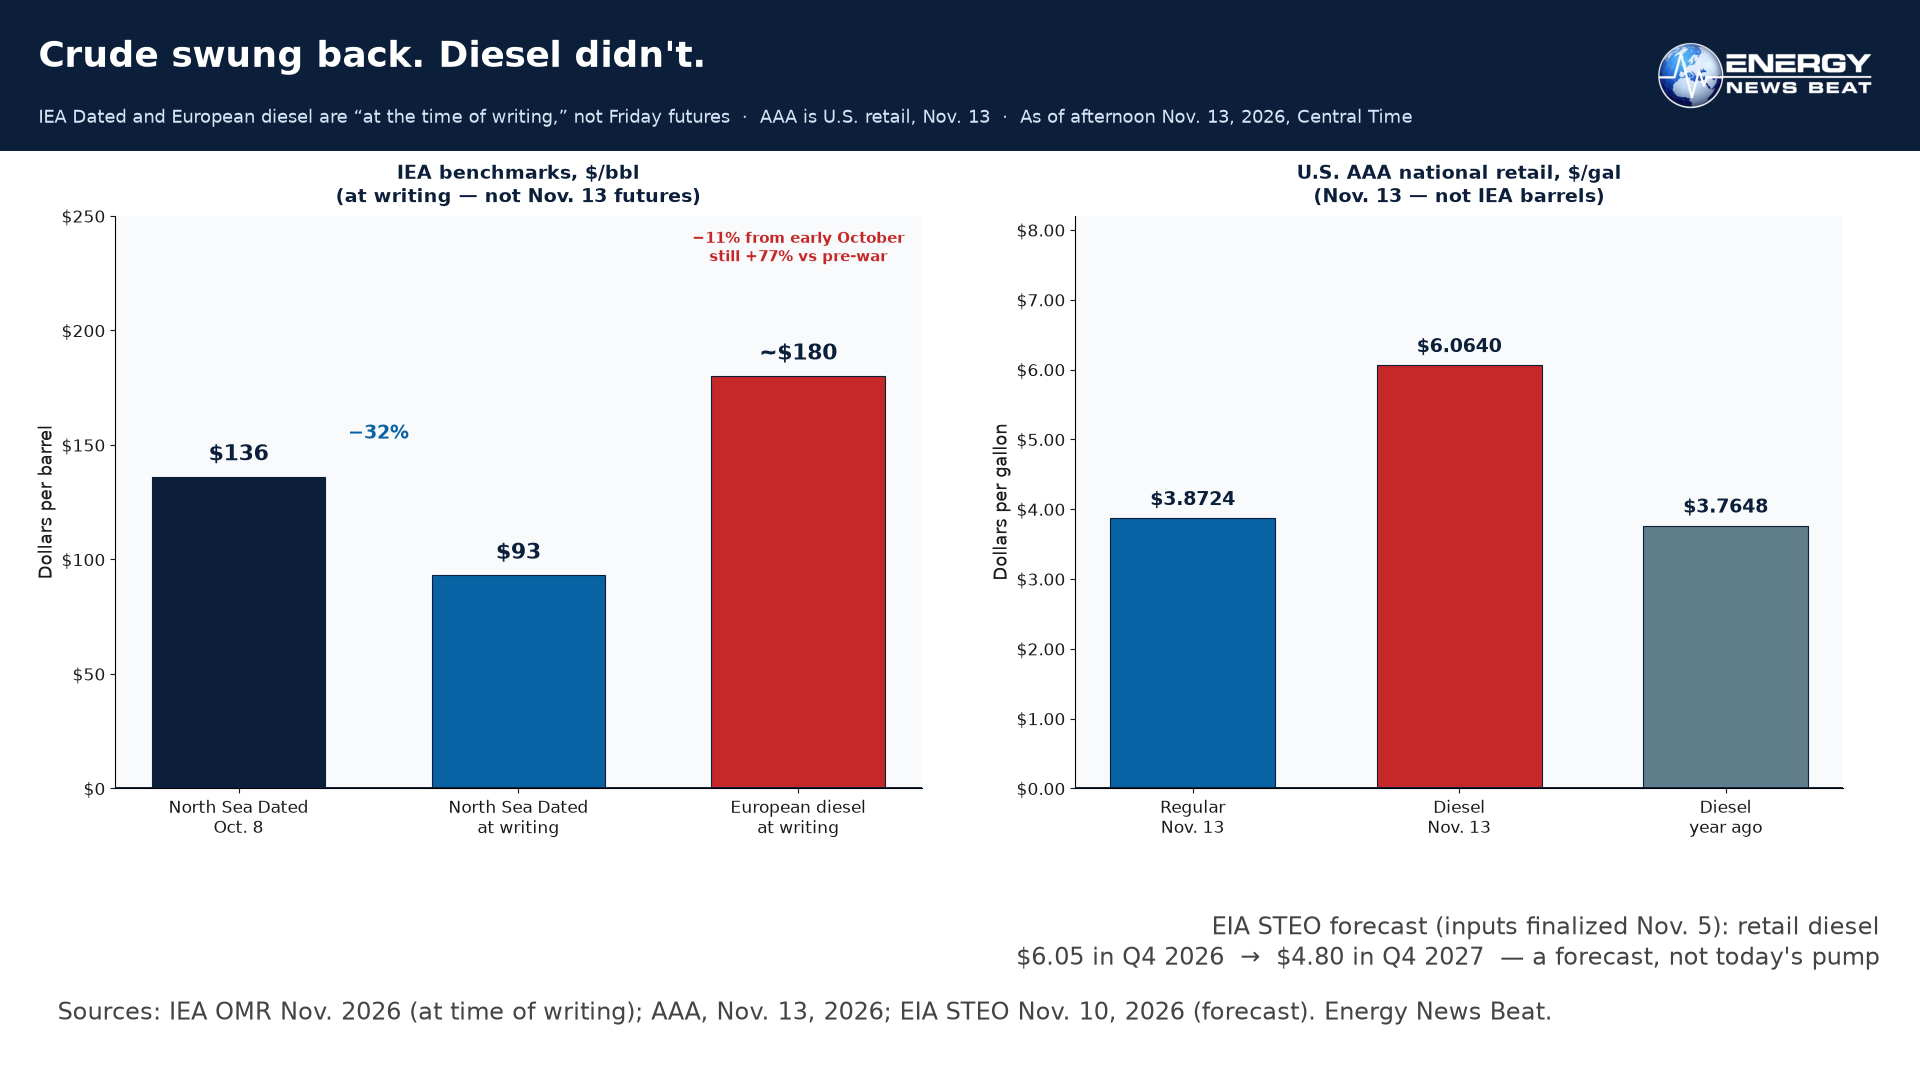
The International Energy Agency said Friday the global oil market is swinging back to a surplus — and that severe tightness in product supply, especially diesel, remains the “overriding concern.” In its November Oil Market Report, published Nov. 13, the agency said North Sea Dated crude “tumbled by 32%,” from a high of $136 a barrel on Oct. 8 to $93 “at the time of writing,” still $22 above pre-war levels. Diesel prices in Europe “fell by 11%” over the same period but, “at close to $180/bbl, remained 77% above pre-war levels.” Those IEA figures are not Friday’s futures or the U.S. pump. AAA put national regular at $3.8724 a gallon on Nov. 13 and diesel at $6.0640.
Global supply rose 2.3 million barrels a day to 105.4 million in October, the IEA said, “on lofty Gulf exports despite ongoing attacks on energy infrastructure and tankers,” after a 3 million b/d September increase and a 5.3 million b/d lift since August. After a 4.8 million b/d decline in 2026, “oil supply is expected to rebound by 6.6 mb/d, reaching an average of 108.1 mb/d in 2027.” The 108.1 million is next year’s average, not the growth figure. Demand falls 2.7 million b/d in 2026, to 102.3 million, then rebounds by 2 million b/d in 2027, with “LPG/ethane and naphtha” about “80% of the increase” and “transport fuels” seeing “very modest gain.”
“Our November supply and demand balances suggest that the global oil market will return to a surplus in 4Q26, with a more substantial build in 2027,” the IEA wrote, adding that “attacks on shipping undermine maritime security.” Reuters said 4Q26 supply will average 105 million b/d, 1.7 million above demand, with a 2027 surplus of about 3.8 million b/d. Gulf exports excluding Oman reached 18.4 million b/d in October, still 26% below pre-war; products and LPG remain at “roughly half of pre-war levels.” Observed inventories rose 52 million barrels in October as oil on water surged 86 million, but on-land stocks “continued to fall” and “remain at their lowest level since at least 2016.” Observed global stocks have fallen a cumulative 462 million barrels since the war began.
The IEA’s $93 Dated figure is not Friday’s futures close. Official settlements on Friday, Nov. 13, were $95.84 a barrel for ICE Brent January, up 2 cents, and $88.56 for NYMEX WTI December, down 18 cents, according to Xinhua and Dow Jones Market Data. Thursday’s official settlements were $95.82 and $88.74. U.S. pump diesel was still above $6, versus $3.7648 a year earlier and below the Sept. 22 record of $6.5276. AAA already calls this the most expensive November on record for gasoline.
Emergency diesel releases, the IEA said, will provide a “critical bridge” until refinery output recovers. Reuters said members will make about 71 million barrels available through end-February 2027, including about 15 million barrels of diesel almost entirely from France and Germany. A related Reuters dispatch put about 37 million barrels from the U.S. SPR and about 33 million from Europe, which includes most of the diesel, with wartime releases heading toward about 420 million barrels if schedules are met, above the March 400 million target. EIA’s weekly report for the week ended Nov. 6, released Nov. 12, showed U.S. distillate stocks up 4.1 million barrels, to 103.3 million, still below the year-ago 110.9 million.
EIA’s Short-Term Energy Outlook, released Nov. 10, predates today’s IEA report. The agency “finalized inputs into the model on November 5, 2026” and “does not specifically account for market events after that day,” so it omits President Trump’s Nov. 12 social-media post and today’s IEA balances. Table 2 has Brent spot at $97.44 in 2026 and $85.78 in 2027 (rounded $97 and $86), regular gasoline at $3.89 and $3.73, and on-highway diesel at $5.25 and $5.03, with fourth-quarter 2026 retail diesel at $6.05, easing to $4.80 in the fourth quarter of 2027.
Consumer & Investor Views
For households and truckers, a forecast surplus is not a lower filling-station bill. Regular has eased, but diesel is still more than $2 a gallon above last year. Weigh the on-land stock draw, the 26% Gulf-export shortfall, and the IEA’s shipping-risk warning against the 2027 build. Emergency releases are a bridge, not a cure.
Caveats
IEA Dated $93 and European diesel near $180 are “at the time of writing,” not Nov. 13 futures or U.S. retail. Reuters supplied the 4Q26 supply of 105 million b/d and the 2027 surplus of about 3.8 million b/d. Friday’s $95.84 Brent and $88.56 WTI figures are official ICE and NYMEX settlements, per Xinhua and Dow Jones Market Data, not the IEA Dated benchmark. Weekly distillate is versus year-ago stocks, not a five-year average. The STEO omits events after Nov. 5.
Stu’s Take
The IEA just told the market that crude is heading back into surplus. That matters. It does not mean the diesel problem is over. Dated crude has come a long way off $136 a barrel, and European diesel has come off only 11%, still 77% above pre-war levels. At the U.S. pump, diesel is still hanging above $6 a gallon. On-land inventories are at their lowest since at least 2016, Gulf product exports are still roughly half of pre-war, and the agency itself calls diesel the “overriding concern.” Emergency stocks are a “critical bridge,” not a substitute for product supply coming back. If you drive a truck, heat with oil, or follow refiners and midstream, watch distillate and on-land stocks — not just the headline surplus. The paper barrel can turn faster than the gallon at the rack.
Appendix A — Sources
Primary documents and wires used for this article, opened or reconfirmed on Friday, Nov. 13, 2026. Full excerpts are in Appendix B; the data table is Appendix C.
- IEA, Oil Market Report, November 2026 (Highlights and “Straightening out” essay), published Nov. 13, 2026. https://www.iea.org/reports/oil-market-report-november-2026
- Reuters (Alex Lawler), via BNN Bloomberg, “World oil market is returning to surplus as Gulf exports recover, IEA says,” Nov. 13, 2026, 7:53 a.m. EST (4Q26 supply 105 mb/d, ~1.7 mb/d above demand; 2027 surplus about 3.8 mb/d; 71 mb emergency stocks including 15 mb diesel). https://www.bnnbloomberg.ca/markets/oil/2026/11/13/world-oil-market-is-returning-to-surplus-as-gulf-exports-recover-iea-says/
- Reuters, via BOE Report, “Oil releases from IEA emergency stocks to pick up through February, agency says,” Nov. 13, 2026, 8:45 a.m. (BOE Report timestamp) (71 mb through end-February 2027; ~15 mb diesel almost entirely France and Germany; Europe ~33 mb; U.S. SPR ~37 mb; 349 mb already out; ~420 mb if schedules met vs 400 mb March commitment). https://boereport.com/2026/11/13/oil-releases-from-iea-emergency-stocks-to-pick-up-through-february-agency-says/
- U.S. Energy Information Administration, Short-Term Energy Outlook, November 2026, released Nov. 10, 2026 (model inputs finalized Nov. 5). https://www.eia.gov/outlooks/steo/
- EIA, STEO Table 2, Energy Prices (Brent, WTI, regular gasoline, on-highway diesel, including quarterly diesel $6.05 in Q4 2026 and $4.80 in Q4 2027). https://www.eia.gov/outlooks/steo/tables/pdf/2tab.pdf
- EIA, Weekly Petroleum Status Report, week ended Nov. 6, 2026, released Nov. 12, 2026, Overview Table 1 (distillate 103.3 million barrels, +4.1 million; year-ago 110.9 million; file as of the Nov. 12 release). https://ir.eia.gov/wpsr/overview.pdf
- AAA Fuel Prices, national averages as of Nov. 13, 2026 (daily page, regular $3.8724, diesel $6.0640, year-ago diesel $3.7648). https://gasprices.aaa.com/
- AAA commentary, Nov. 12, 2026, as quoted by al.com, Nov. 13, 2026: “So far, this month is the most expensive November on record for gas prices.” Record diesel $6.5276 on Sept. 22, 2026, per AAA’s “highest recorded average price” table, https://gasprices.aaa.com/. https://www.al.com/news/2026/11/gas-prices-for-111326-what-will-you-pay-heading-into-the-weekend.html
- Xinhua, dateline NEW YORK, Nov. 12, 2026 (published Nov. 13): official Thursday settlements — NYMEX WTI December $88.74, up $2.21 or 2.55%; ICE Brent January $95.82, up $3.06 or 3.3%. https://english.news.cn/20261113/382ec38ae9164b60ba58298b585b868c/c.html
- Xinhua, Nov. 13, 2026, via NAMPA: official Friday settlements — NYMEX WTI December $88.56, down 18 cents or 0.2%; ICE Brent January $95.84, up 2 cents or 0.02%. https://www.nampa.org/text/23065816
- Dow Jones Market Data, Nov. 13, 2026, via Morningstar Data Talk: front-month NYMEX crude (Dec.) settled at $88.56, down 18 cents or 0.20% (WTI Data Talk); front-month ICE Brent (Jan.) settled at $95.84, up 2 cents or 0.02% (Brent Data Talk).
Appendix B — Key excerpts
IEA Highlights, November 2026: “Following an increase of 3 mb/d in September, global oil supply rose by a further 2.3 mb/d to 105.4 mb/d in October on lofty Gulf exports despite ongoing attacks on energy infrastructure and tankers.” “After a decline of 4.8 mb/d in 2026, oil supply is expected to rebound by 6.6 mb/d, reaching an average of 108.1 mb/d in 2027.” “World oil demand is forecast to fall by 2.7 mb/d in 2026, to 102.3 mb/d, before rebounding by 2 mb/d in 2027.” “LPG/ethane and naphtha will account for around 80% of the increase next year as supply chains normalise, while transport fuels will see very modest gain.”
IEA Highlights on prices and stocks: “North Sea Dated crude oil prices tumbled by 32%, dropping from a high of $136/bbl in early October to $93/bbl at the time of writing, as a sustained recovery in Gulf exports eased market tightness. Diesel prices also fell by 11% in Europe over the same period but, at close to $180/bbl, remained 77% above pre-war levels.” “Observed oil inventories rebounded by 52 mb (+1.7 mb/d) in October, the first increase since June, as oil on water surged by 86 mb to its highest level since January on robust crude exports from the Gulf. On-land stocks continued to fall, however, and remain at their lowest level since at least 2016.” “Observed global stocks have fallen by a cumulative 462 mb since the start of the war.”
IEA “Straightening out” essay: “The oil market is showing tentative signs of rebalancing, with global oil supplies surpassing demand for the first time since the outbreak of the war in Iran.” “North Sea Dated crude oil prices plunged by more than 30% from a high of $136/bbl on 8 October to around $93/bbl at the time of writing but remained $22/bbl above pre-war levels.” “Global oil supplies surged by 2.3 mb/d to 105.4 mb/d in October, lifting output by an extraordinary 5.3 mb/d since August.” “Despite continued attacks on tankers, Gulf oil exports, excluding Oman, reached 18.4 mb/d last month, 26% below pre-war levels.” “Global oil demand continues to be weighed down by ongoing disruptions to exports of refined products and LPG from the Gulf, remaining at roughly half of pre-war levels, and high fuel prices.”
IEA essay on the surplus and diesel: “Our November supply and demand balances suggest that the global oil market will return to a surplus in 4Q26, with a more substantial build in 2027. As always, downside risks to the forecast persist, as attacks on shipping undermine maritime security, which is pivotal to a sustained recovery. For now, the severe tightness in product supply, especially for diesel, remains the overriding concern of the broader market and consumers.” “Notably, the accelerated release of IEA emergency diesel stocks over the coming months will provide a critical bridge across the supply gap until the global refinery system and product output recover.”
Reuters via BNN Bloomberg, Nov. 13, 2026: “Oil supply will average 105 million barrels per day in the fourth quarter … 1.7 million bpd higher than forecast demand.” “For 2027, the IEA sees the supply surplus at about 3.8 million bpd, slightly down from a 3.94 million bpd surplus last month.” The same dispatch said the agency “gave more details of remaining volumes to come from a record release of oil from its members’ emergency reserves pledged in March, saying 71 million barrels would be made available by the end of February including 15 million barrels of diesel to ease market tightness.” It also noted Brent was last down 0.1% at $95.71 after the 0900 GMT release, as of the dispatch — an earlier Friday print, not the official afternoon settlements used in the body.
Reuters via BOE Report, Nov. 13, 2026, 8:45 a.m. (BOE Report timestamp): “The International Energy Agency’s member countries will release around 71 million barrels of emergency oil and products stocks through end-February 2027.” “Included in the release will be around 15 million barrels of diesel which are scheduled to be released by end-February, almost entirely from government stocks in France and Germany, at a pace of 4 million to 5 million barrels in January before easing in February.” “Emergency oil stock releases in Europe are expected to total 33 million barrels, led by Germany and France, and around 37 million barrels is due to come from the US Strategic Petroleum Reserve. Government stocks account for at least 85% of all scheduled volumes.” “Since then, member countries have put out 349 million barrels of emergency stocks.” The report quotes the IEA: “If current schedules are met, total emergency stocks released by IEA countries would reach around 420 million barrels, exceeding the 400 million barrels committed for release in March.”
EIA STEO, November 2026, released Nov. 10: model “finalized inputs into the model on November 5, 2026” and “does not specifically account for market events after that day.” Table 2: Brent spot $97.44 (2026) and $85.78 (2027); WTI $88.29 and $80.54; regular gasoline $3.89 and $3.73; retail on-highway diesel $5.25 and $5.03; quarterly diesel $6.05 in Q4 2026, easing to $4.80 in Q4 2027.
EIA Weekly Petroleum Status Report, Overview Table 1, week ended Nov. 6, 2026 (released Nov. 12): commercial crude 414.4 million barrels (+4.7); gasoline 210.8 million (+1.8); distillate fuel oil 103.3 million (+4.1 from 99.3; year-ago 110.9 million, −7.6 million or −6.8%). SPR 279.5 million. U.S. distillate is compared with year-ago stocks only.
AAA Fuel Prices, as of Nov. 13, 2026: regular $3.8724, mid-grade $4.4025, premium $4.7966, diesel $6.0640, E85 $2.9818. Yesterday: regular $3.9081, diesel $6.0977. Week ago: $4.0688 / $6.2305. Month ago: $4.3413 / $6.2787. Year ago: $3.0799 / $3.7648. AAA, quoted by al.com on Nov. 13: “So far, this month is the most expensive November on record for gas prices.”
Xinhua via NAMPA, Nov. 13, 2026: “Oil prices settled mixed on Friday. The West Texas Intermediate for December delivery lost 18 cents, or 0.2 percent, to settle at 88.56 U.S. dollars a barrel on the New York Mercantile Exchange. Brent crude for January delivery added 2 cents, or 0.02 percent, to settle at 95.84 dollars a barrel on the London ICE Futures Exchange.” Dow Jones Market Data, via Morningstar Data Talk the same day: front-month NYMEX crude for December settled at $88.56, down 18 cents or 0.20%; front-month ICE Brent for January settled at $95.84, up 2 cents or 0.02%.
Appendix C — Full data table
Figures below are as reported by the named source. IEA Dated and European diesel are “at the time of writing” in the Nov. 13 report, not Friday futures or U.S. retail. Friday crude figures are official ICE Brent January and NYMEX WTI December settlements.
| Date | Item | What the official source says | What it is not |
| Oct. 2026 | IEA global oil supply | 105.4 mb/d, up 2.3 mb/d in October (after +3 mb/d in September; +5.3 mb/d since August) | Not a 2027 average, and not demand |
| 2026 / 2027 | IEA supply outlook | 2026 supply down 4.8 mb/d; 2027 supply rebound +6.6 mb/d to an average of 108.1 mb/d | +6.6 mb/d is growth; 108.1 mb/d is the 2027 total |
| 2026 / 2027 | IEA demand outlook | 2026 demand down 2.7 mb/d to 102.3 mb/d; 2027 demand rebound +2 mb/d (~80% LPG/ethane and naphtha; transport fuels “very modest”) | Not a transport-fuel recovery story |
| 4Q26 / 2027 | IEA / Reuters surplus | IEA: balances suggest surplus in 4Q26 and a more substantial 2027 build. Reuters: 4Q26 supply 105 mb/d, ~1.7 mb/d above demand; 2027 surplus about 3.8 mb/d | A forecast, with IEA downside risk from shipping attacks |
| Oct. 2026 | Gulf exports ex-Oman | 18.4 mb/d, still 26% below pre-war; refined products and LPG “roughly half of pre-war levels” | Not a full pre-war recovery |
| Oct. 2026 | IEA observed stocks | +52 mb in October (first rise since June) as oil on water +86 mb; on-land stocks still falling, lowest since at least 2016; cumulative 462 mb drawn since the war began | The +52 mb is not an on-land rebuild |
| IEA at writing | North Sea Dated | $136/bbl on Oct. 8 to $93/bbl at writing, −32%; still $22/bbl above pre-war (essay: “around $93”) | Not Nov. 13 ICE/NYMEX futures and not U.S. retail |
| IEA at writing | European diesel | Fell 11% over the same period; “at close to $180/bbl, remained 77% above pre-war levels” | Not a published pre-war price |
| Nov. 12, 2026 | Official futures settles | ICE Brent January $95.82; NYMEX WTI December $88.74 (Xinhua) | Not the IEA Dated $93 benchmark |
| Nov. 13, 2026 | Official futures settles | ICE Brent January $95.84, up 2 cents; NYMEX WTI December $88.56, down 18 cents (Xinhua; Dow Jones Market Data) | Not the IEA Dated $93 benchmark |
| Nov. 13, 2026 | AAA U.S. retail | Regular $3.8724/gal; diesel $6.0640/gal; year-ago diesel $3.7648; below Sept. 22 record $6.5276 | Dollars per gallon, not IEA $/bbl |
| Week ended Nov. 6 | EIA U.S. distillate stocks | 103.3 million barrels, +4.1 million; year-ago 110.9 million (−6.8%) | Not a verified five-year-average comparison |
| STEO Nov. 10 | EIA price outlook | Brent spot $97.44 (2026) / $85.78 (2027); regular $3.89 / $3.73; diesel $5.25 / $5.03; Q4 2026 diesel $6.05 → Q4 2027 $4.80 | Inputs finalized Nov. 5; does not include the Nov. 12 Trump post or the Nov. 13 IEA report |
| Through Feb. 2027 | IEA emergency stocks (Reuters) | ~71 mb total, including ~15 mb diesel almost entirely France/Germany (mostly inside Europe’s ~33 mb); U.S. SPR ~37 mb; 349 mb already out; ~420 mb if schedules met vs 400 mb March target | A scheduled release, not a new standalone program |
Sources: IEA Oil Market Report, November 2026; Reuters via BNN Bloomberg and BOE Report, Nov. 13, 2026; EIA STEO, Nov. 10, 2026, Table 2; EIA WPSR Overview, week ended Nov. 6, 2026; AAA Fuel Prices as of Nov. 13, 2026; Xinhua Nov. 12 settlements; Xinhua and Dow Jones Market Data official Nov. 13 settlements (ICE Brent January $95.84, NYMEX WTI December $88.56). Energy News Beat.
Appendix D — Background
The IEA’s November 2026 Oil Market Report is the agency’s first full monthly balances update after a sharp rebound in Gulf crude exports during September and October, even as attacks on tankers and energy infrastructure continued. The war in Iran, which began in late February 2026, had already forced a record emergency-stock program, announced in March, of up to 400 million barrels. Crude prices have come off their early-October highs as exports recovered through workarounds, including so-called dark crossings of the Strait of Hormuz, but product markets — especially diesel — have lagged because Gulf product and LPG exports remain roughly half of pre-war levels and attacks have continued to disrupt Russian diesel supplies. The United States is seeing the same split at the pump: regular gasoline has slipped back under $4 a gallon, while national diesel remains above $6. EIA’s November Short-Term Energy Outlook, whose inputs were locked on Nov. 5, still envisions retail diesel easing from a $6.05 average in the fourth quarter of 2026 toward $4.80 by the fourth quarter of 2027 — a path, not a promise, and one that does not yet include today’s IEA surplus call.
Appendix E — Methodology
IEA figures and quotations are from the Highlights and the “Straightening out” essay on the IEA’s November 2026 Oil Market Report page (Nov. 13, 2026). The 4Q26 supply of 105 mb/d, the ~1.7 mb/d gap, the ~3.8 mb/d 2027 surplus, and the emergency-stock volumes (71, 15, 33, 37, 349 and ~420 million barrels) are as reported by Reuters from the full report. EIA figures are from STEO Table 2 (released Nov. 10; inputs finalized Nov. 5) and WPSR Overview Table 1 (week ended Nov. 6, released Nov. 12); U.S. distillate is compared with year-ago stocks only. Retail prices are AAA national averages dated 11/13/26. Friday crude prices are official ICE Brent January and NYMEX WTI December settlements reported by Xinhua and Dow Jones Market Data; IEA North Sea Dated and European diesel levels are “at the time of writing” and are not futures or retail prices.