
The war is in its ninth month and the United States has never taken Kharg. It did not have to: the blockade drove Iranian seaborne crude to zero with no American ground casualties, which is exactly what a seizure was supposed to deliver. The question worth asking is not whether America could hold the island. It is what holding it would have invited.
By Energy News Beat | Oct. 31, 2026 | Anthony Cordesman, CSIS, “Lessons of Modern War, Vol. II,” ch. 7, read Oct. 31; USNI “Proceedings,” April 2026; ACLED, Aug. 4, 2026; Foreign Policy, Oct. 30, 2026; EIA STEO data, Aug. 12, 2026; ICE settlement, Oct. 30; EIA retail survey, week of Oct. 26.
There is a version of this story that gets written every few weeks, and it is wrong every time. In it, American aircraft are about to destroy Kharg Island, Iran’s main oil terminal, and the world braces. The claim traces to one UAE outlet, Erem News, on Oct. 19, citing anonymous diplomatic sources and confirmed by nobody. Israel Hayom, Moneycontrol and JFeed all ran it; none of them added a second source. That is one report counted four times.
Here is what actually happened, and it is a better story. The United States struck more than 90 military targets on Kharg in March and deliberately spared the oil infrastructure. It threatened for months to take the island and shelved the idea. Then it imposed a naval blockade — lifted for four weeks under the June memorandum, reinstated on 14 July — that drove Iranian seaborne crude exports to effectively zero by October, with roughly 43 million barrels stranded inside the blockade zone and, by all available reporting, no American ground casualties from any Kharg operation.
The blockade already delivered what the seizure was for. So the honest question is not whether America could take Kharg. It is what taking it would have bought, and what it would have invited.
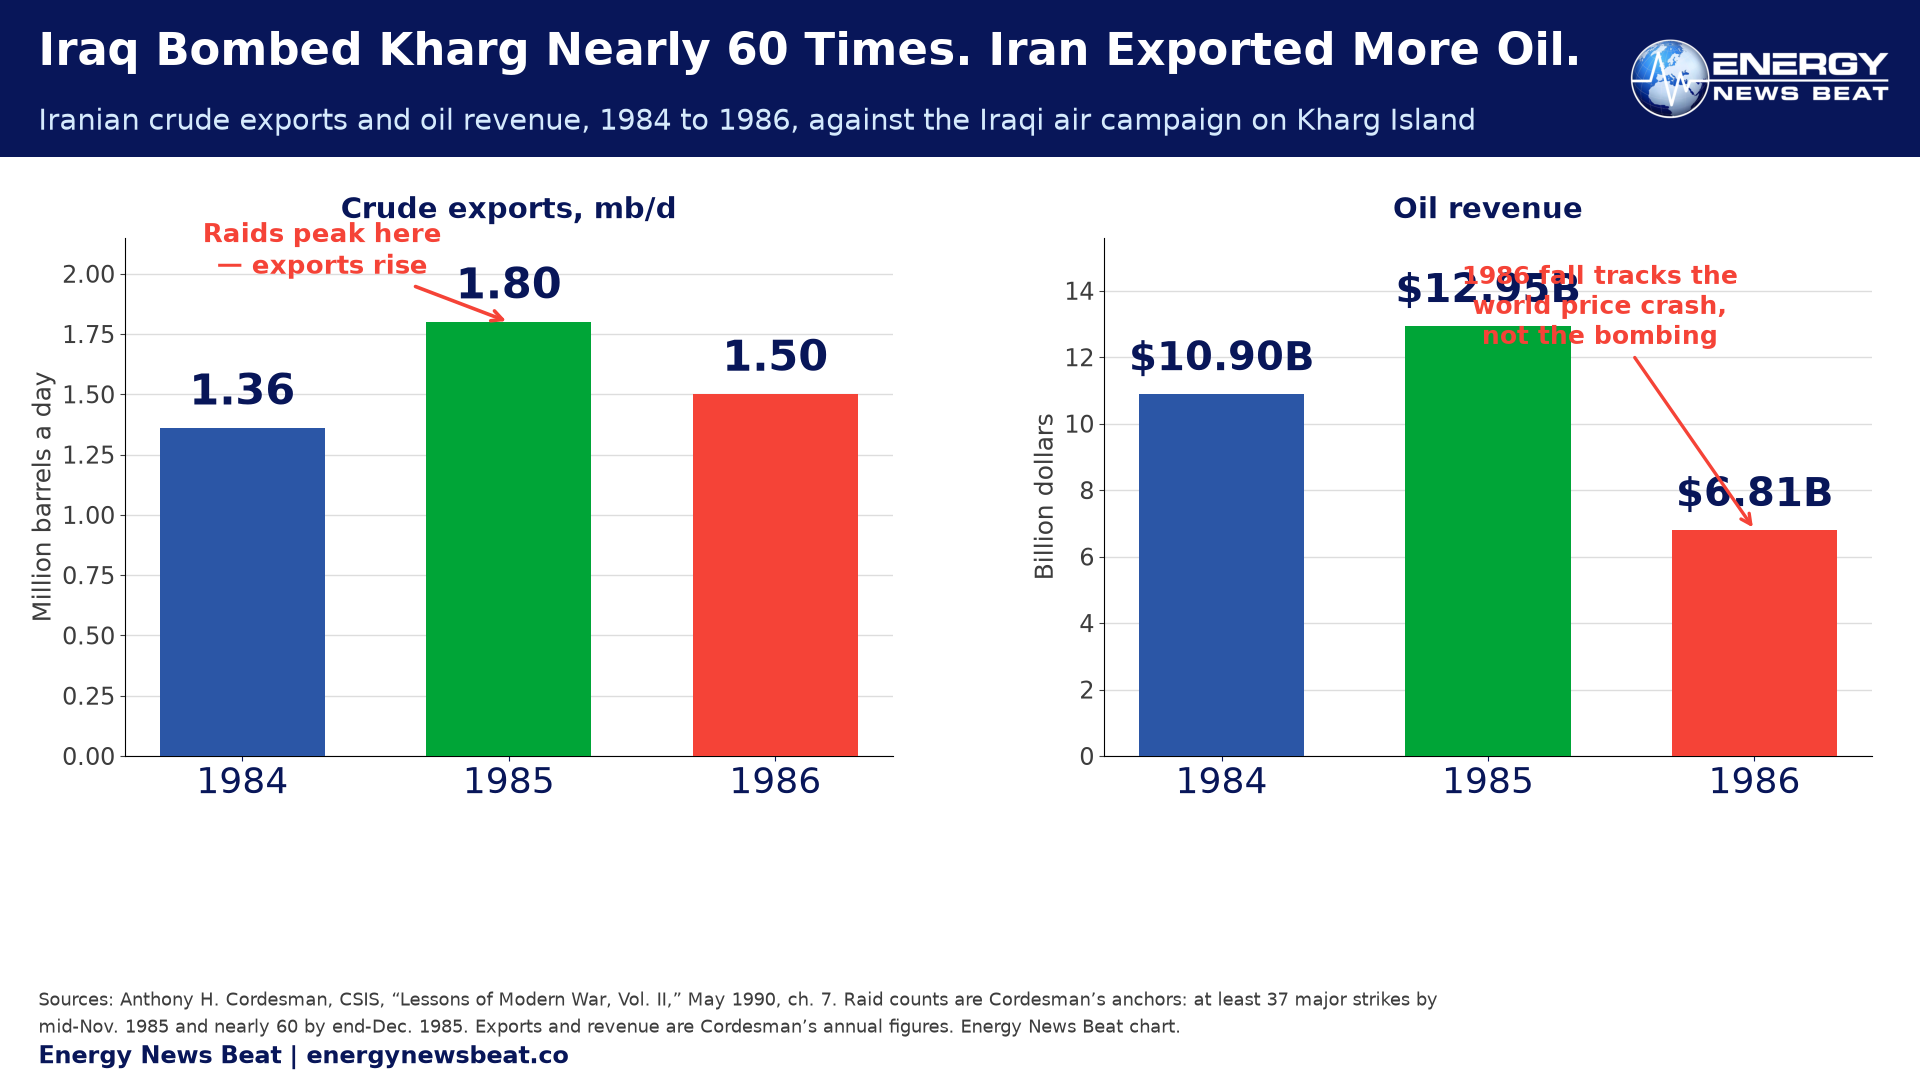
The reason is mechanical. Iran did not defend the terminal; it routed around it. It leased six tankers and shuttled crude over 800 kilometers to Sirri Island, with naval escort and fighter cover. When Iraq attacked Sirri, Iran shifted transshipment to Larak — though as late as mid-1987 about 80 percent of its oil still moved through Kharg. The terminal was never the system.
Cordesman’s general finding is worth carrying into any discussion of Kharg today: “Supposedly critical vulnerabilities generally prove to be easily repairable or subject to substitution, particularly when the country under attack is given time to recover. The net effect of such attacks has generally been to unite a nation in hostility rather than to intimidate it.”
What seizure would actually require
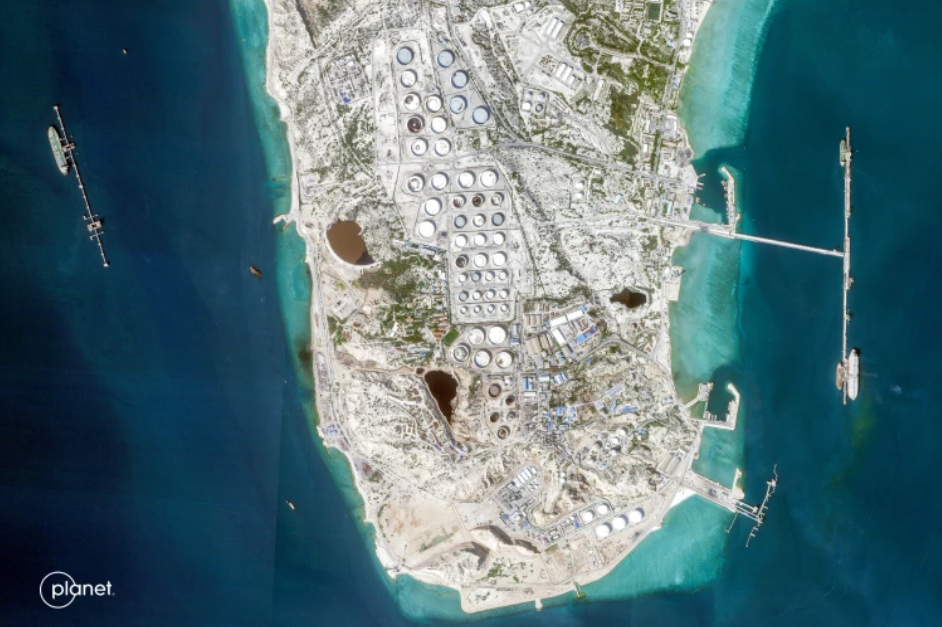
Kharg is 7.7 square miles, flat, more than 8,000 civilians, and 16 miles off the Iranian coast. There is no cover. Iran has laid anti-personnel and anti-armor mines on the beaches and moved in additional MANPADs and personnel. A USNI Proceedings analysis concludes it is “highly unlikely the United States could launch an operation against Kharg with any advantage of surprise.”
Taking it is the easy half. Holding it is the problem: Marine Expeditionary Units self-sustain for about 15 days before resupply, and that resupply would come under fire. Francis Galgano of Villanova estimates about 5,000 troops to take and hold the island. One report, from Zeteo in March, citing anonymous officials, put initial casualties “easily in the dozens,” rising sharply if the island were held — single-outlet and unconfirmed, and we flag it as such. No government and no second outlet has published an estimate.
Two former officials said it plainly. Joe Kent, who resigned from the administration over the war, told the Washington Post an invasion “would be a disaster” that would hand Iran “a bunch of hostages on an island that they could barrage with drones and missiles.” Harrison Mann, a former intelligence analyst, wrote that for the troops ordered in, the operation “would land somewhere between a suicide mission and a self-imposed hostage crisis.”
Iran said what it would do. Then it did it.
In March, a spokesperson for Iran’s Khatam al-Anbiya Central Headquarters stated the doctrine in advance: “In the event of an attack on the oil, economic and energy infrastructure of the Islamic Republic of Iran … all oil, economic and energy infrastructure belonging to oil companies throughout the region that own American stocks or cooperate with the United States will be immediately destroyed … turned into a pile of ashes.” Hours later a drone forced Fujairah to suspend loadings.
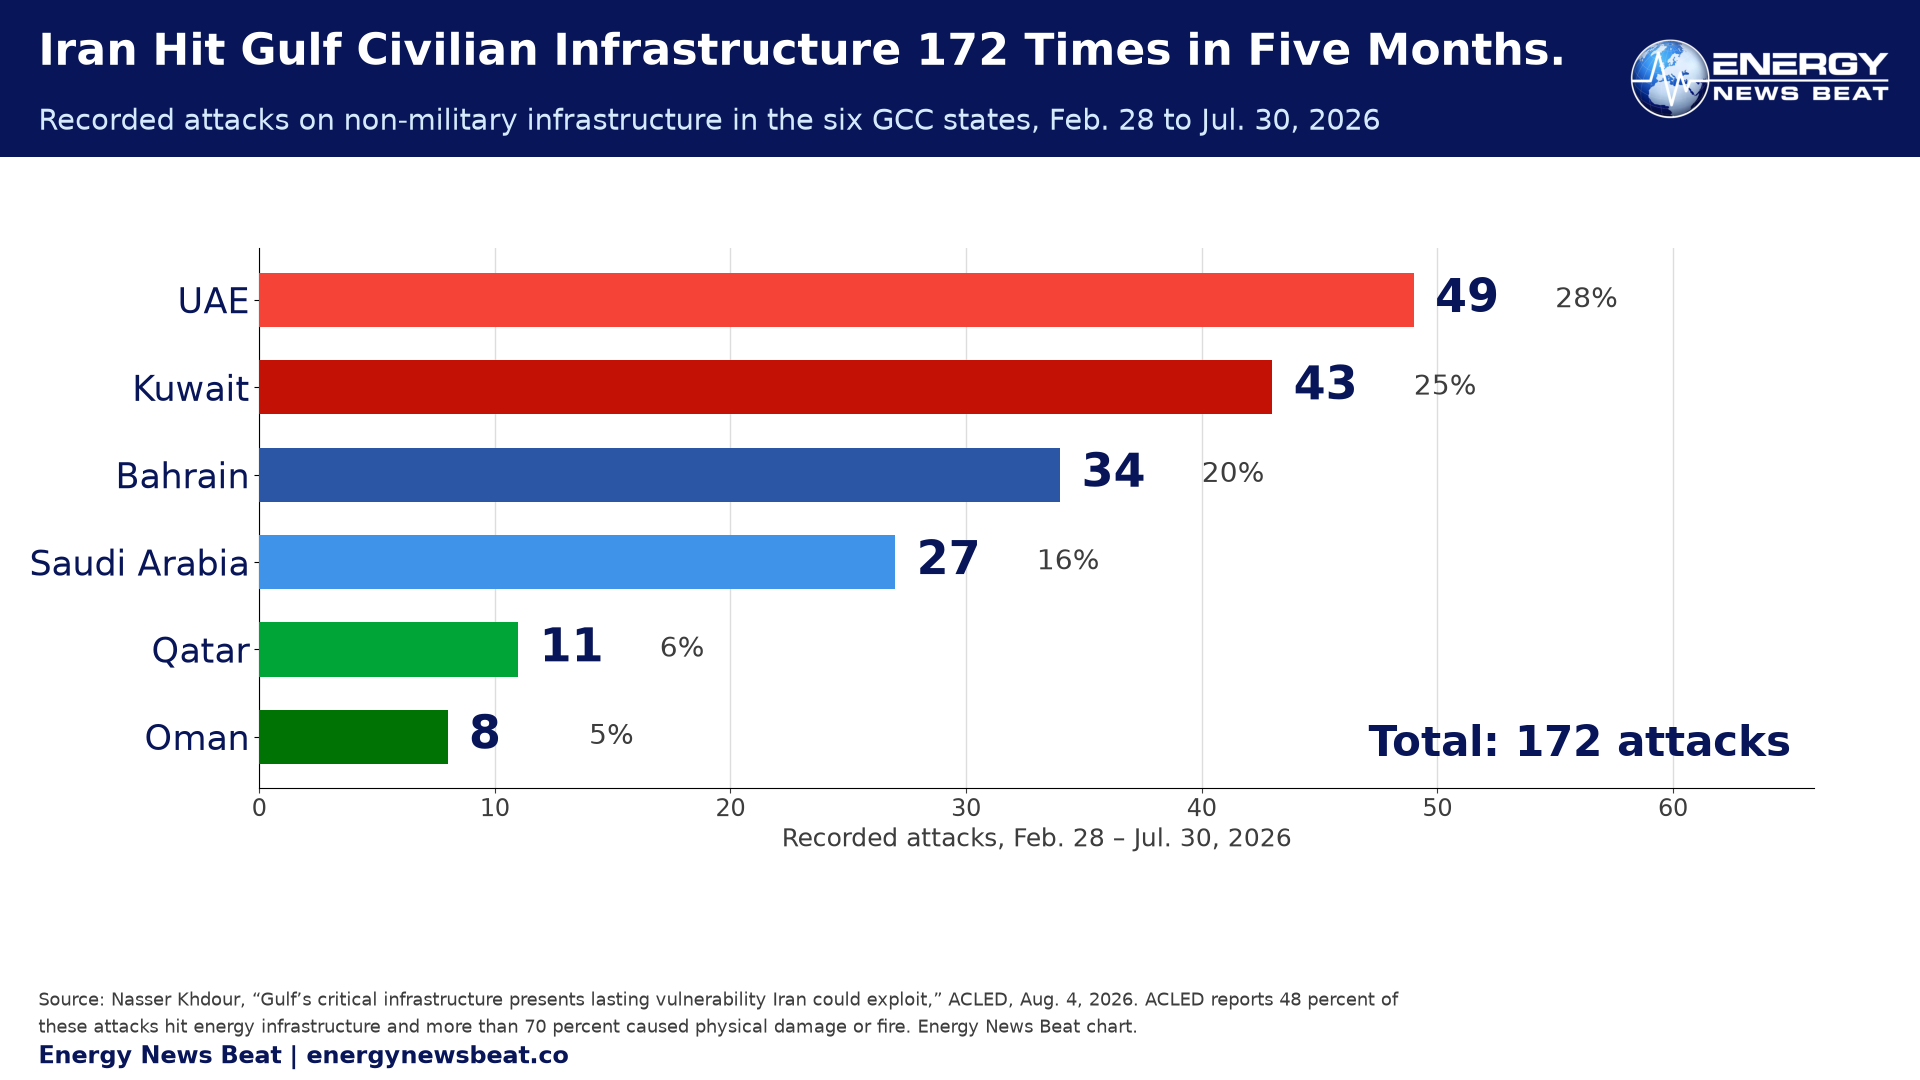
That is not rhetoric. ACLED counted 172 attacks on non-military infrastructure across the six Gulf states between Feb. 28 and July 30, 2026. Energy facilities were 48 percent of them. More than 70 percent caused damage or fire. The UAE took 49, Kuwait 43, Bahrain 34, Saudi Arabia 27.
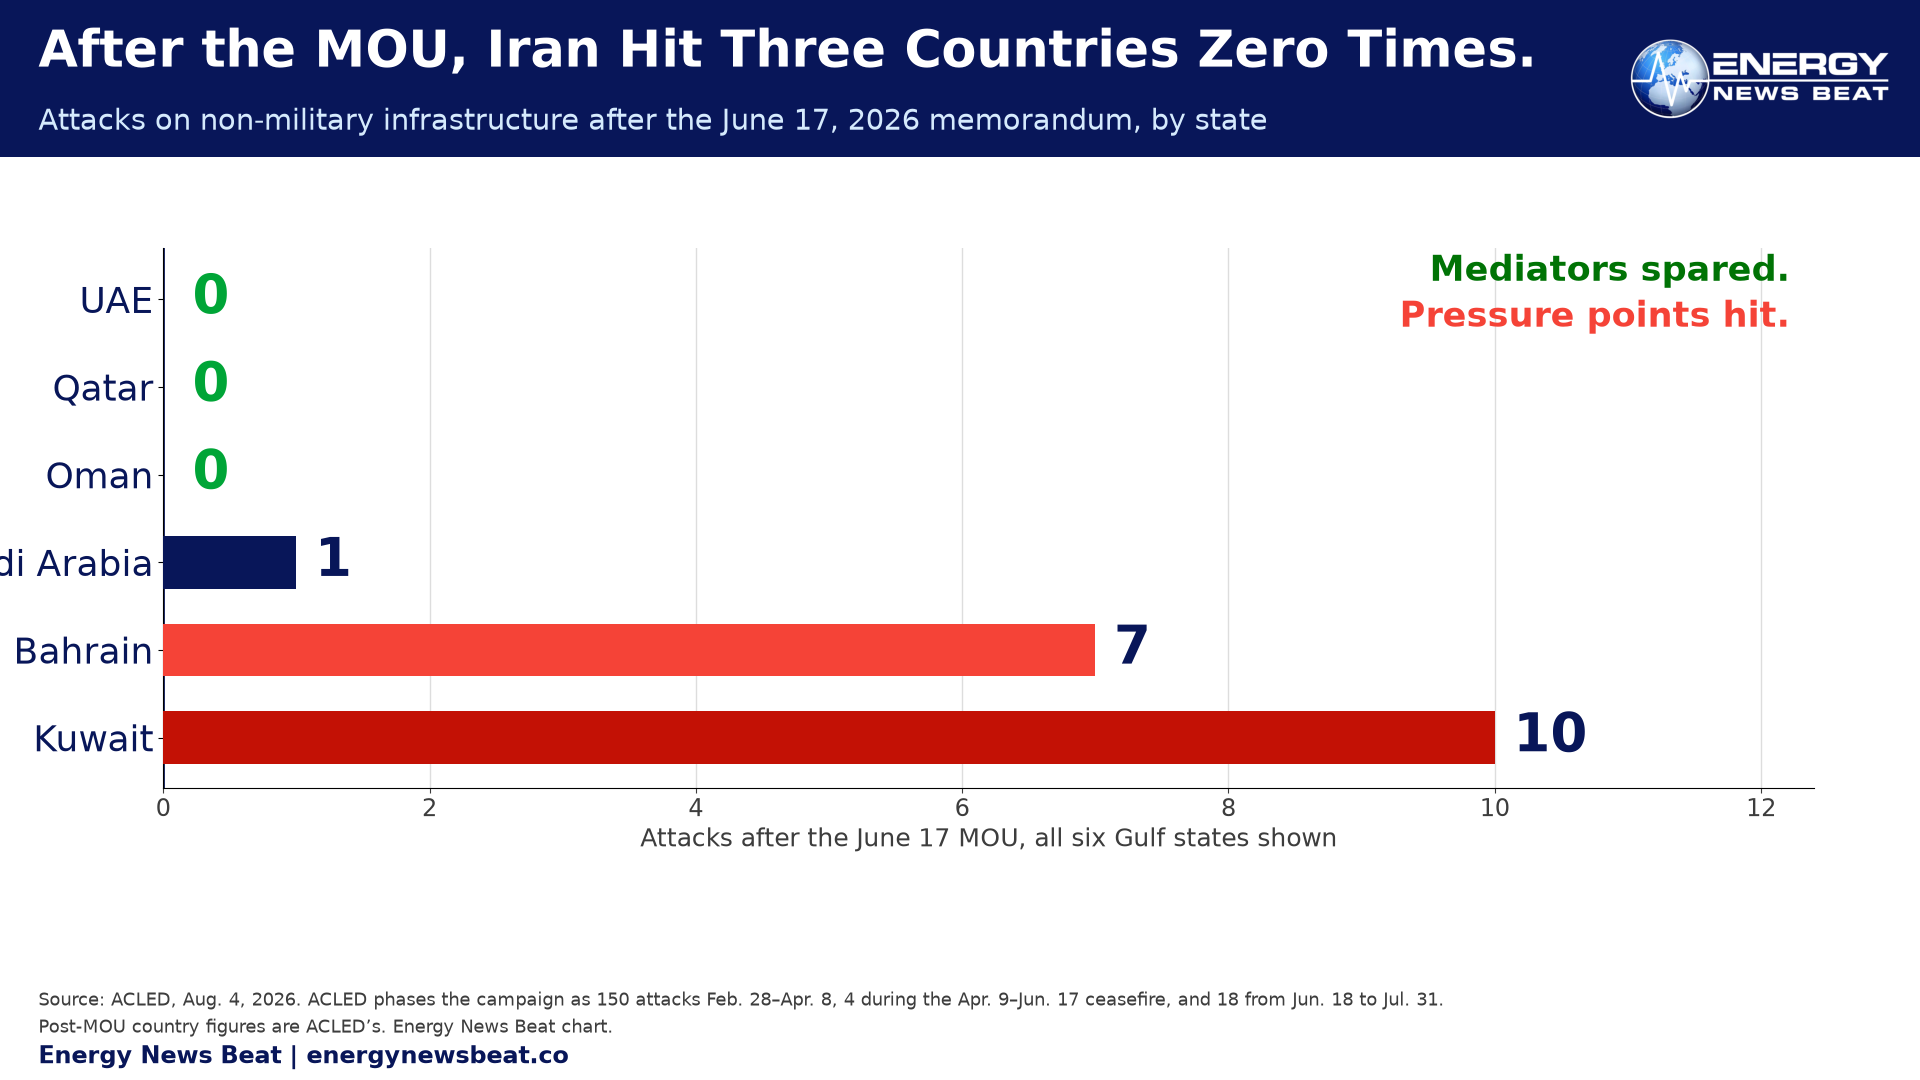
And the pattern is not indiscriminate. Since the June 17 memorandum of understanding, Iran has hit zero non-military targets in the UAE, Qatar or Oman; Kuwait took 10 and Bahrain 7. Which state gets hit tracks perceived alignment, not geography. This is a bargaining instrument, calibrated for political effect — which is more disturbing than a doctrine of annihilation, because it means the retaliation is chosen.
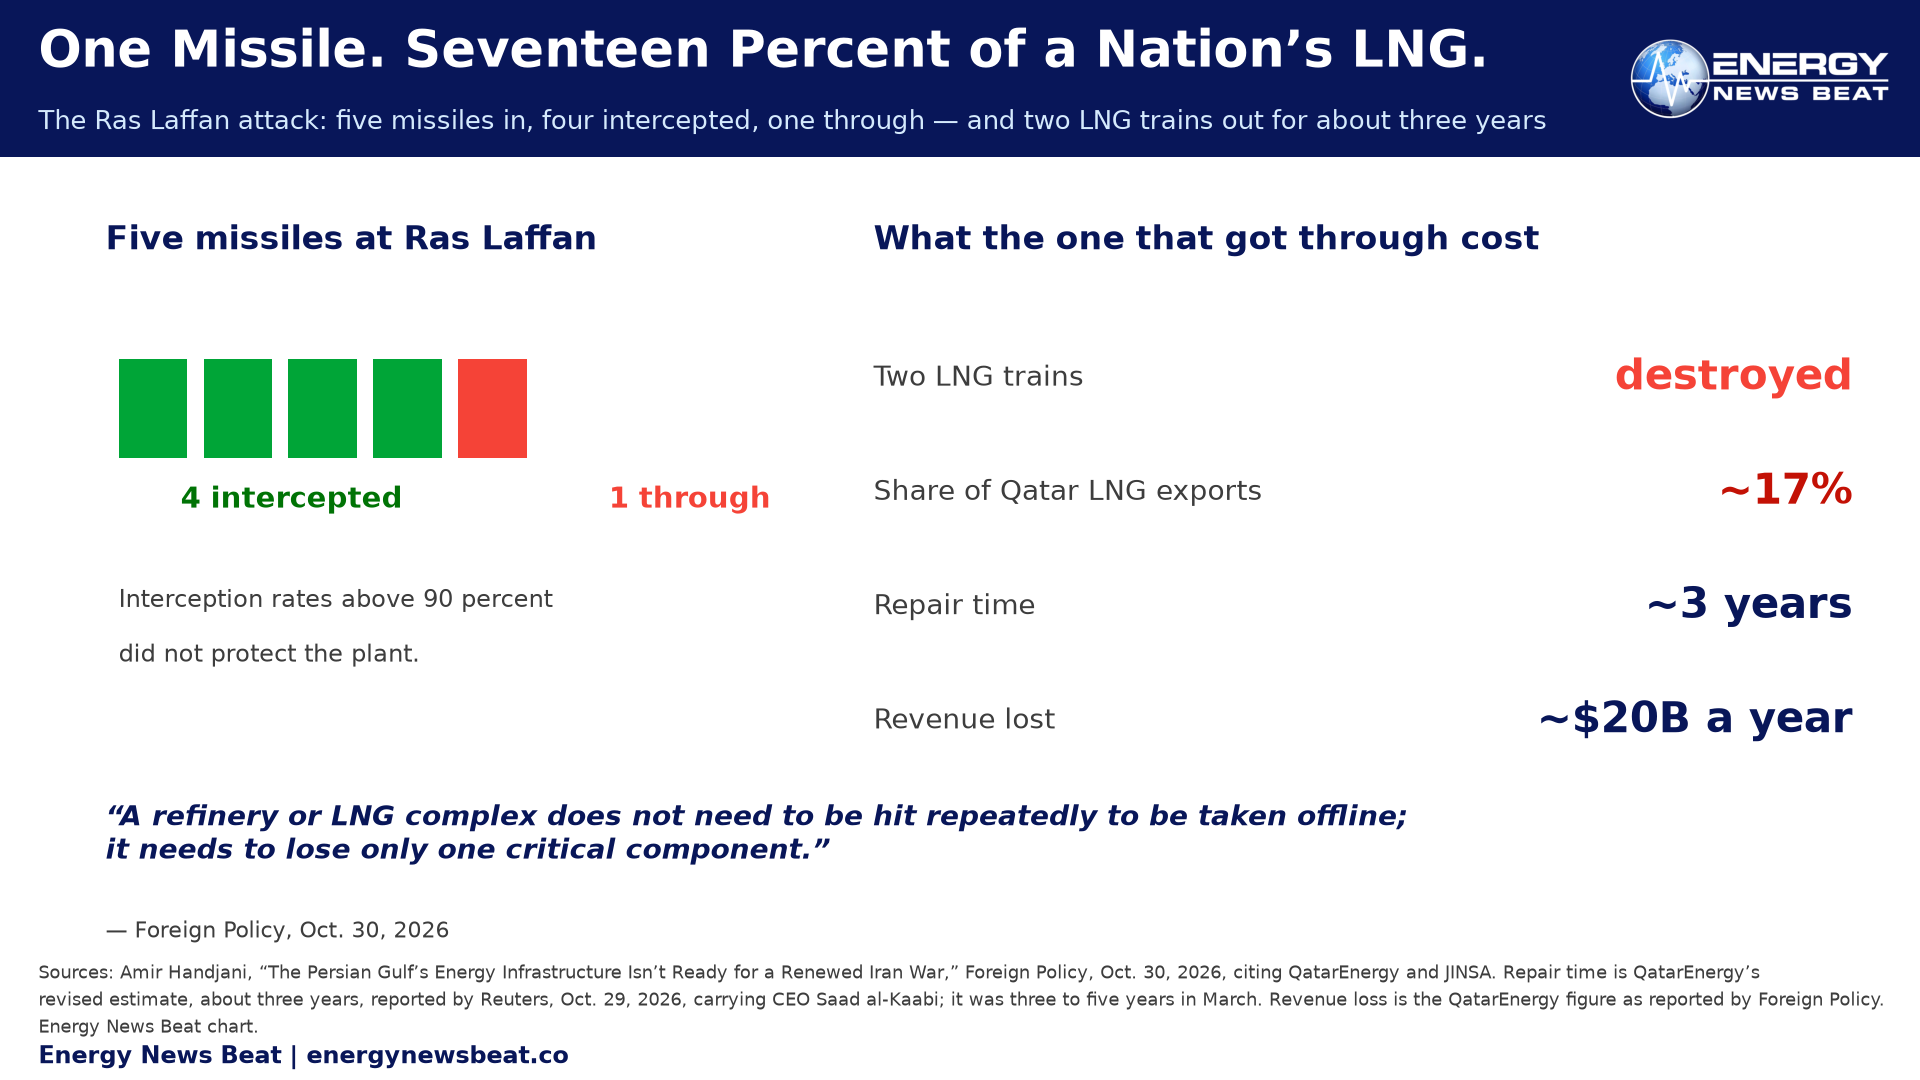
One missile explains why it matters. At Ras Laffan in March, four of five incoming missiles were intercepted. One got through, and that attack took out two LNG trains, about 17 percent of Qatar’s export capacity, for about three years on QatarEnergy’s latest estimate, revised down from the three to five years it gave in March, at an estimated $20 billion a year in lost revenue. The undamaged 83 percent of capacity could restart within a week of a peace deal; the lost 17 percent cannot — and that is the part the market prices. The lesson, in Foreign Policy’s words: “A refinery or LNG complex does not need to be hit repeatedly to be taken offline; it needs to lose only one critical component.”
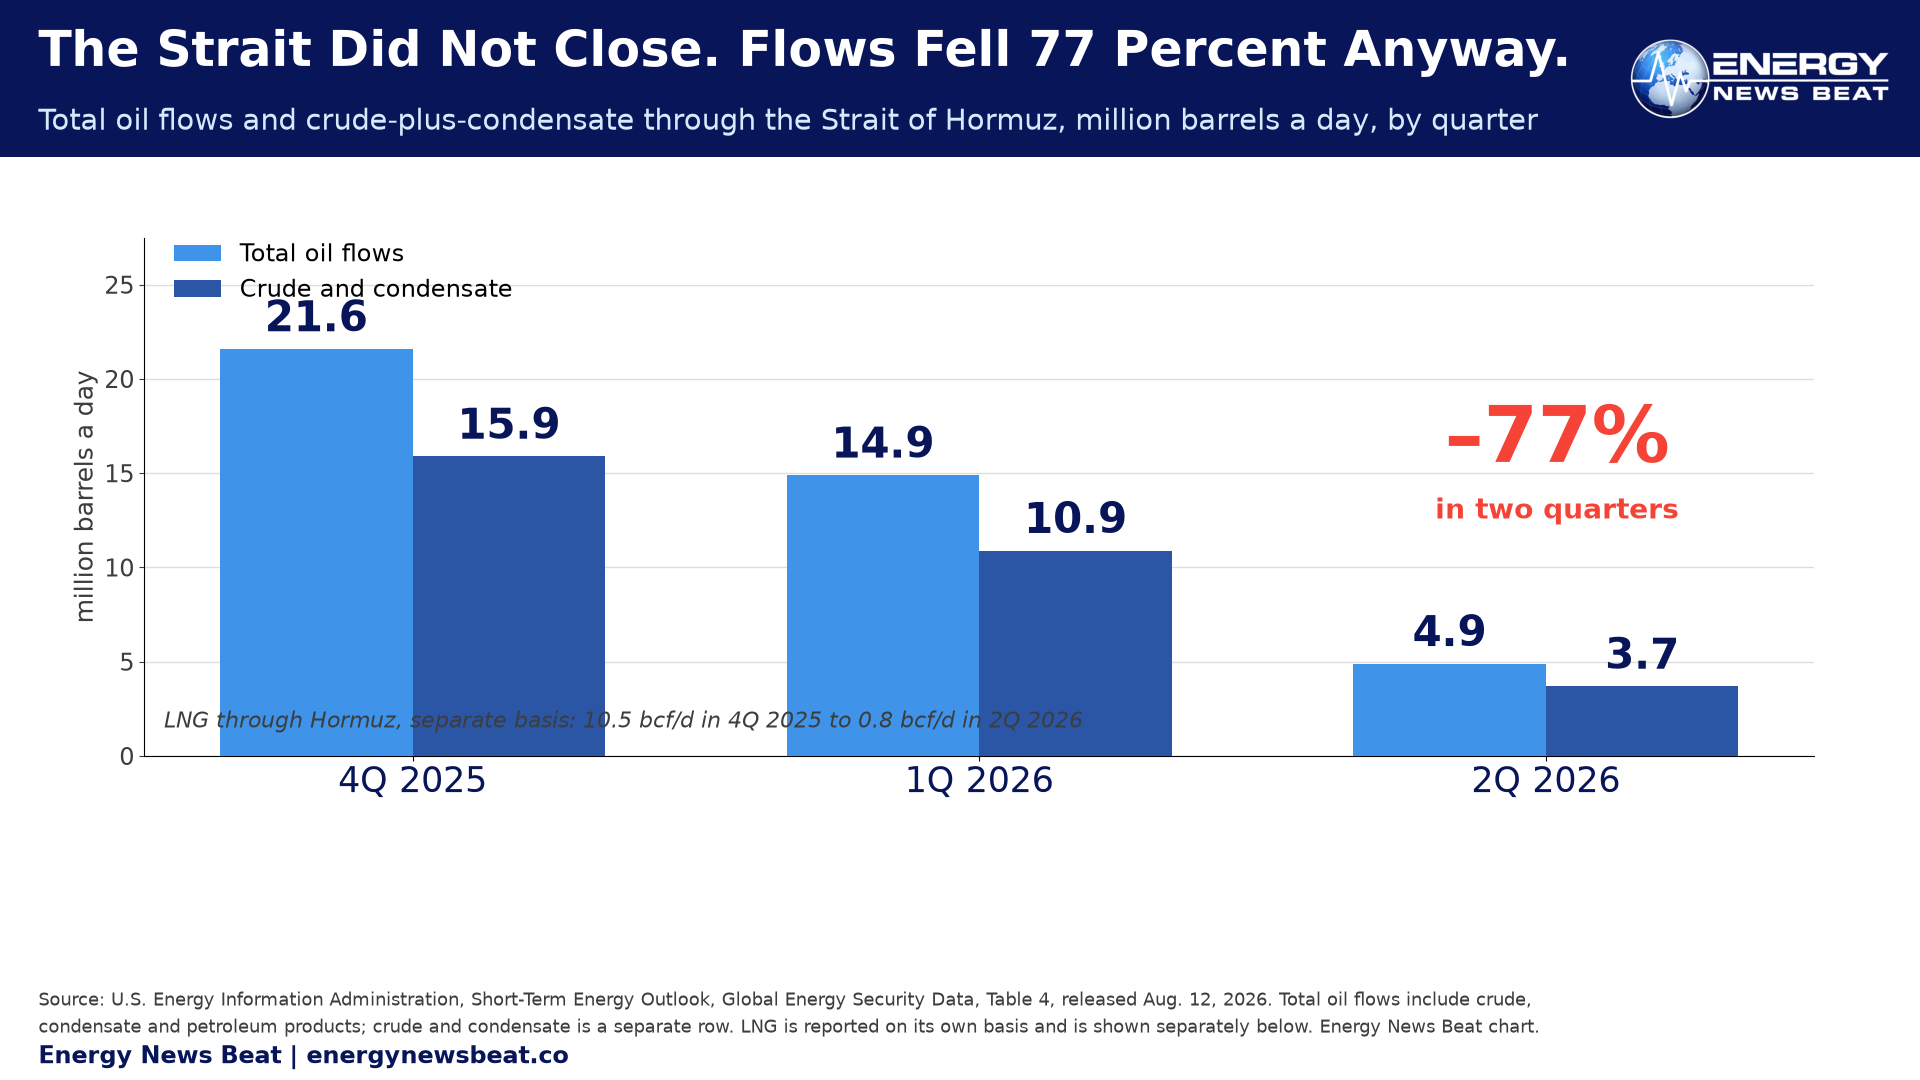
The interception rate is the wrong metric, and the Gulf learned that the hard way. The UAE reported intercepting 132 of 137 ballistic missiles on day one; Bahrain had burned through up to 87 percent of its Patriot interceptors by late March. Hormuz traffic tells the same story in flow data: total oil through the strait fell from 21.6 million barrels a day in the fourth quarter of 2025 to 14.9 and then 4.9. Crude and condensate alone went from 15.9 to 3.7, and LNG from 10.5 billion cubic feet a day to 0.8. That is measured flow, not a model.
The money was never the oil
There is a second half to this argument, and it is where the conversation usually goes wrong. It is worth being precise about what is documented here and what is the host’s thesis, because the documented half does not need the thesis to stand. The thesis, which is his and is argued in his own words in the Take below, is that America does not need to own a country’s oil to control what it is worth to that country’s government — it needs a dollar-denominated sale, an account at a U.S. institution, and a licensing authority that can switch the flow. That is right, and the mechanism is documented even where the larger claim is argued.
Every dollar Iraq earns from selling crude enters an account at the Federal Reserve Bank of New York from which Baghdad pays salaries and imports. In April 2026 the United States suspended dollar shipments and security cooperation to press Iraq toward a government without Iranian influence. The mechanism is real and it was used. It is also not new: UN Security Council Resolution 1483 created the Development Fund for Iraq in May 2003, and CPA Regulation No. 2 implemented it the following month, putting the fund at the New York Fed and providing that “The Fund will be controlled by the Administrator through a communications protocol.”
Two corrections, because getting them wrong hands a critic the whole article. The Federal Reserve is not a privately held company; its own FAQ says the system is “not ‘owned’ by anyone,” that member-bank stock ownership is by law a condition of membership and is “quite different from owning stock in a private company,” that the Reserve Banks are not operated for profit, that they must transfer net earnings to the Treasury, and that those who read it as a private corporation have “mistakenly” done so. And there is no “Bank of Qatar” — the Venezuelan account was reportedly at Qatar National Bank, a partly state-owned commercial bank, and it was temporary. Chris Wright, in an NBC News interview reported by CNBC on Feb. 13: “Now we have an account at the U.S. Treasury. The money won’t go to Qatar anymore.”
The accurate version is more radical than the version it replaces. Executive Order 14373 of Jan. 9, 2026 holds Venezuelan oil revenue in Treasury as, in its own words, “sovereign property of the Government of Venezuela … and not as the property of the United States,” immune from creditors, disbursed at the direction of the Secretary of State, under IEEPA authority. General License 50A then authorizes BP, Chevron, Eni, Maurel & Prom, Repsol and Shell to operate in Venezuela on condition that every royalty and tax is paid into those Treasury accounts, under contracts governed by U.S. law. A custodial regime over a foreign state’s resource revenue, created by executive order, with reporting to two agencies and no independent audit.
The precedent that should temper all of it is Iraq. The U.S. controlled that money from June 2003 and the insurgency intensified anyway through the 2006–07 civil war. The IAMB’s final report found it “not possible to determine that all Iraqi oil resources … had been used for the benefit of the Iraqi people,” and SIGIR found the Defense Department could not account for $8.7 billion of the $9.1 billion it received. The independent international audit ended when the IAMB’s mandate expired on 30 June 2011; oversight passed to Iraq’s Committee of Financial Experts, which Baghdad had created back in October 2006 to take over. Twenty-three years on, Washington still cannot get Baghdad to disarm Iran-aligned militias; the deadline has slipped to June 2027.
Consumer and investor views
For a driver the number that matters this week is diesel, not crude. U.S. on-highway diesel averaged $6.352 a gallon in the week of Oct. 26, up 7.6 cents, the second consecutive weekly increase, against $3.718 a year ago. Gasoline fell slightly, to $4.269. California paid $5.888 for gasoline and $8.155 for diesel. The war is transmitting through the distillate barrel, not the crude one, and the households most exposed are the ones heating with oil.
For an investor the signal is in the curve, not the headline. Brent for December settled at $117.64 on Oct. 30, and January at $113.43 — a $4.21 backwardation. The market is paying up for the next sixty days and pricing relief after that. It is charging for a decision, not for a multi-year outage. On Polymarket, the contract asking whether Kharg leaves Iranian control by Oct. 31 trades below 1 percent on $1.56 million of volume. The same event’s Dec. 31 contract sits at 8 to 9 percent — an 8.5 percent midpoint, a last trade of 9, quoted 8 bid and 9 offered. Read those two numbers together and the market is saying something narrower and more useful than “nothing will happen”: it assigns almost no probability to a seizure in the next twenty-four hours, and a small one to a seizure inside two months. Neither is a price that reflects conviction that an operation is under way.
The honest counter-case
The strongest argument for taking Kharg is that it would have ended the war quickly by bankrupting the IRGC, and it is worth stating in its own words. Officials reportedly believed taking the island would “totally bankrupt” the Guard, while many inside the administration were wary because it required ground troops. That is the optimistic case, and it is the one the evidence then fails.
The counter-case has three parts. First, the leverage was already total: with exports at zero, bombing the terminal removes barrels that are already off the market, so the incremental supply loss is far smaller than the “90 percent of Iran’s exports” framing implies. Second, Iran’s other terminals could meet about 25 percent of Kharg’s volume, Iranian crude has sold at roughly twice its pre-war price, and Iran ran exports below 250,000 barrels a day for months in 2021–22 “yet the regime refused to buckle.” Third, and decisively, a seizure converts a price event into a capacity event. A stranded cargo is a headline; a destroyed LNG train is three years of lost capacity, with 83 percent of the rest able to restart within a week of a peace deal.
Where the other side is right: a strike on the oil terminal would hurt, and the escalation ladder is real. The U.S. has already threatened to hit Kharg’s crude facilities if Hormuz were not reopened, CNN has reported that strike packages include “a lot of energy infrastructure”, and the President has said he “may do another little Epic Fury.” None of that is a plan to seize the island. It is a threat to bomb it, which is a different and cheaper thing — and the difference is the whole point.
What the record actually supports
One thing needs saying plainly, because it is the reason this piece is a counterfactual and not a warning. There is no substantial, verifiable reporting that a U.S. seizure of Kharg, or a strike on its oil infrastructure, is imminent. No named American official has confirmed Kharg is a target. The AP and the Wall Street Journal both reported independently, on Oct. 28, that Gulf allies had been told to prepare for possible renewed action after the midterms — a real and well-sourced build-up, and not the same claim.
The video circulating of Kharg exploding is AI-generated. It was posted on Aug. 30 with the caption “Kharg Island being blown to smithereens!!!” No attack occurred on Kharg; CENTCOM said the strikes that day hit two rocket launchers on Larak Island instead. Any clip of Kharg in flames is almost certainly that fabrication resurfacing.
So the answer to the what-if is neither branch usually offered. A seizure would not produce regional stability, and the IRGC would not necessarily destroy the entire region. It would be undertaken to acquire leverage the United States already holds, at the cost of creating the one vulnerability Iran most wants to hold — and the retaliation would be reciprocal, named in advance, calibrated to political effect, and aimed at precisely those facilities whose destruction turns a price event into a years-long capacity event.
Iraq hit Kharg nearly sixty times by the end of 1985 and Iranian exports went up. The barrels found another route, because the terminal was never the system. What the blockade proved is that you can stop the barrels without taking the ground. What Ras Laffan proved is what the ground is worth to the other side.
| STU’S TAKE
Opinion. Every number is linked to its source. Let me say the thing that needs saying first. I have spent nine months watching people argue about taking Kharg Island, and most of the argument is about a war that already happened in a different way. We bombed that island. Ninety-plus military targets, March, and we went out of our way not to touch the oil. Then we blockaded instead, and Iranian seaborne exports went to zero anyway, with no American ground casualties. So the seizure everyone keeps debating is a road we did not walk, and we did not need it. That means the honest version of the question is not whether we could take Kharg. It is what taking it would have cost us, and whether we would have liked the bill. My answer is no, and I want to be careful about why, because I have argued both sides of this out loud and one of my own premises was wrong. I used to say the Fed is a private company. It is not, and its own FAQ says so in plain English: the system is “not owned by anyone,” and people who think otherwise have “mistakenly” done so. I also used to say the Venezuela money runs through a bank in Qatar. There is no Bank of Qatar. It was Qatar National Bank, temporarily, and since February the money sits at Treasury, where EO 14373 holds it as the sovereign property of Venezuela and not of the United States. That is a stranger and more radical arrangement than the one I was describing, and it is all in the paperwork. So here is the sharper version. We do not need to own the oil. We own the plumbing. Every dollar Iraq earns from crude lands at the New York Fed, and when we wanted a government in Baghdad without Iranian influence, we turned that off for a while. Which brings me back to Kharg. Iraq flew nearly sixty raids at that terminal in the eighties and Iranian exports went up. The lesson was never that bombing fails. The lesson is that the terminal is not the system. Our blockade proved it again this year, from the water, without a single soldier standing on seven square miles of flat ground sixteen miles off an enemy coast with eight thousand civilians on it. Iran told us what it would do. Then it did it 172 times. One missile at Ras Laffan took out seventeen percent of Qatar’s LNG for years. That is the price of the ground. We did not pay it. Let us not go looking for the invoice. We won this one by not taking the island. Somebody should write that down before the next person proposes taking it. My advice, is learn the difference between Iraq and Iran, and understand the history that was taught to us, and search for the real history through older books. Trust no one single publication. And The Energy News Beat is a composite of show notes and opinions for the podcast. We offer our sources to the open, unless we are asked not to share, but we want cross checking, and I will admit when I am wrong. Oh, last part of the advice – harden your home for safety. Plan for the worst so that more Americans can stroll through a natural disaster. We are living in a new era where it will get bumpy before it gets better. |
Appendix
Sources, verbatim excerpts, data tables, methodology notes and corrections for “Iraq Hit Kharg Island Nearly 60 Times. Iran’s Oil Exports Rose.”. The principal figures in the article resolve to these entries. Where a number is an Energy News Beat calculation it is labelled as one here and in the text.
A. Sources (all accessed Oct. 31, 2026)
- Anthony H. Cordesman, “Lessons of Modern War, Vol. II: The Iran-Iraq War,” CSIS, May 1990, chapter 7, “The Air War Against Iranian Oil,” read in full
- Brandon Carr, “Seizing Iranian Offshore Islands: High Risk, Low Payoff,” U.S. Naval Institute Proceedings, April 2026, Vol. 152/4/1,478
- Politico Europe, “Iran warns of retaliatory strikes on US oil facilities,” March 14, 2026, quoting the CENTCOM statement and the Khatam al-Anbiya statement in full
- Nasser Khdour, “Gulf’s critical infrastructure presents lasting vulnerability Iran could exploit,” ACLED, Aug. 4, 2026
- Amir Handjani, “The Persian Gulf’s Energy Infrastructure Isn’t Ready for a Renewed Iran War,” Foreign Policy, Oct. 30, 2026, citing the Reuters investigation as well as QatarEnergy and JINSA figures
- S. Energy Information Administration, Short-Term Energy Outlook, Global Energy Security Data, Table 4, released Aug. 12, 2026
- The National (Abu Dhabi), “US suspends Iraq’s dollar access as pressure tactic to curb Iranian influence and militias,” April 21, 2026
- Coalition Provisional Authority, Regulation No. 2, “Development Fund for Iraq,” June 15, 2003, primary text
- International Advisory and Monitoring Board, Final Report, 2011, including Annex II on cumulative DFI flows and the SIGIR finding on unaccounted funds
- Executive Order 14373, “Safeguarding Venezuelan Oil Revenue for the Good of the American and Venezuelan People,” Jan. 9, 2026
- OFAC General License No. 50A, Feb. 18, 2026, authorizing transactions with six named oil companies
- CNBC, “Venezuela oil money won’t go to Qatar anymore, Energy Secretary says,” Feb. 13, 2026, reporting an NBC News interview with Energy Secretary Chris Wright conducted Thursday, Feb. 12, 2026
- Board of Governors of the Federal Reserve System, FAQ “Who owns the Federal Reserve?”
- Qatar National Bank, corporate profile (for the Qatar National Bank / Qatar Central Bank distinction)
- Kpler, “Explainer: Why Kharg Island is the backbone of Iran’s oil economy — and its greatest vulnerability,” March 16, 2026
- Kpler, “Iran’s oil on water outside the blockade zone hits zero as Tehran’s trilemma sharpens,” Oct. 22, 2026
- Al Jazeera, “US military says it has lifted naval blockade of Iranian ports,” June 18, 2026
- S. Forces, “US Forces Resume Naval Blockade Against Iran,” DVIDS release 569836, July 13, 2026
- CNN, “US has struck Iranian military targets on Kharg Island,” updated April 7, 2026, carrying the Mehr damage assessment and the Ghalibaf statement
- CNN, “US and Iran trade attacks, marking first major military escalation in a month,” Aug. 30, 2026, carrying CENTCOM spokesman Capt. Tim Hawkins on the Larak Island rocket launchers
- CNBC, on the March 2026 Kharg strikes and the oil-market reaction, March 13, 2026, carrying the Francis Galgano force estimate
- CNBC, “Trump warns Iran over Kharg Island strikes and oil exports,” March 16, 2026
- Euronews, “Explainer: Why Kharg Island is vital to Iran and the global economy,” March 16, 2026
- Zeteo, “The Kharg Island Bloodbath,” March 23, 2026, single-outlet report on internal U.S. casualty estimates, quoting Joe Kent and Harrison Mann
- International Energy Agency, Strait of Hormuz Factsheet, 2026, sections on oil, natural gas, alternative export routes and country exposure
- Clayton Seigle, “If Trump Strikes Iran: Mapping the Oil Disruption Scenarios,” CSIS, Feb. 18, 2026
- Center for a New American Security, “In Dire Straits? Implications of a US-Iran Conflict for the Global Oil Market,” Nov. 21, 2019
- RAND, Q&A with Scott Savitz on demining the Strait of Hormuz, May 19, 2026
- Can Kasapoğlu, “Cutting the Gordian Knot: US Military Options on Kharg Island and the Strait of Hormuz,” Hudson Institute, March 30, 2026
- Lead Stories fact check of the Aug. 30, 2026 Truth Social video purporting to show Kharg Island destroyed, verified with Hive Moderation, ZeroGPT and FauxLens
- Erem News (UAE), Oct. 19, 2026, the origin of the Kharg strike report, citing unnamed diplomatic sources; relayed by Israel Hayom, Moneycontrol and JFeed, none of which added independent sourcing
- Associated Press (Aamer Madhani and Samy Magdy), Oct. 28, 2026, as published by The Washington Post, on warnings to Gulf allies about post-midterm action
- The Wall Street Journal (Summer Said, Shelby Holliday, Benoit Faucon, Anat Peled), Oct. 28, 2026, read through the To Vima syndication of the full WSJ text
- The Times of Israel, Oct. 30, 2026, on the CENTCOM commander’s briefing of the President and the open-source flight-tracking claims
- Axios (Barak Ravid), Oct. 31, 2026, on Qatari mediation and the internal U.S. debate
- Polymarket, “Kharg Island no longer under Iranian control by…?” event, all sub-markets, read Oct. 31, 2026
- Iran International, Oct. 31, 2026, carrying the SHANA statement by acting oil minister Hamid Bovard and the UKMTO reporting on the Louise 1
- CNN (Zachary Cohen, Haley Britzky, Kevin Liptak), Oct. 15, 2026, on strike packages including energy infrastructure and the MOAB
- Newsquawk, crude market wrap, Oct. 30, 2026, reporting the ICE settlements for December and January contracts
- S. Energy Information Administration, Gasoline and Diesel Fuel Update, week of Oct. 26, 2026, released Oct. 27
- Agreement and Joint Report, United States and Mexico, 58 Stat. 1408–1415 (E.A.S. 419), exchange of notes at Washington, Sept. 25 and 29, 1943
- Independent Inquiry Committee into the United Nations Oil-for-Food Programme (Volcker Committee), final report, Oct. 27, 2005
- UN Security Council Resolution 1483, May 22, 2003, and the Iraqi government letter of 2011 under Resolution 1956 describing the successor account structure
- Executive Order 13668, “Ending Immunities Granted to the Development Fund for Iraq and Certain Other Iraqi Property and Interests in Property Pursuant to Executive Order 13303, as Amended,” May 27, 2014, 79 FR 31019
- Al-Baydar Center (Rafat Al-Baldawi), “Iraqi Funds Abroad,” October 2024, on the IRAQ2 account and the 2014 Federal Reserve–Iraqi Ministry of Finance agreement
- Reuters, “How the U.S. controls Iraq’s oil revenues,” Jan. 23, 2026 (paywalled; substance confirmed through the Al-Monitor syndication)
- Al-Monitor syndication of the Reuters explainer on U.S. control of Iraqi oil revenues, 2026
- Reuters, on the IRGC claim of an attack on the Saudi Jubail petrochemical complex, April 7, 2026
- House of Commons Library, research briefing CBP-10829, on the June 2025 U.S.–Iran strikes and the state of the nuclear file
- Encyclopaedia Iranica, “Kharg Island,” sections iii, on the 1980s Iraqi raids and the state of the terminal by autumn 1986
- Reuters, on Axios’ reporting that the President was weighing a Kharg Island operation to force Iran to reopen the Strait of Hormuz, March 20, 2026
- Institute for the Study of War and the Critical Threats Project at the American Enterprise Institute, Iran Update, editions of Oct. 26, 27, 28, 29 and 30, 2026, section “US and Partner Military Operations”; the standing format note on the same page states that weekend editions are abbreviated and cover the Houthi-Saudi conflict
- Donald J. Trump, Truth Social posts of June 11, 2026, as archived by the American Presidency Project, University of California, Santa Barbara; the 5:22 a.m. post carries the Kharg language and the 10:28 a.m. post cancels the strikes
- Ynet, “Lapid: Destroy all oil fields and energy industry of Iran on Kharg Island,” March 7, 2026
- Al Jazeera (Nour Odeh), “On Iran, Israel’s opposition is even more hawkish than Netanyahu,” Oct. 19, 2026, carrying Lapid’s Atlantic Council remarks calling for strikes on Kharg’s energy facilities
- Al Jazeera, “Mapping where US bombers are based around the world,” Oct. 6, 2026, on the departure of a dozen B-1B bombers from RAF Fairford
- CBS News (Olivia Gazis), “U.S. ordering some government staff to depart Saudi Arabia, reducing military footprint in Middle East,” Oct. 21, 2026, quoting State Department spokesperson Tommy Pigott’s X post on the ordered departure and carrying the Riyadh airport casualty figures
- The Maritime Executive, “Amidst Tensions With Iran, Diego Garcia Fills Up With Support Aircraft,” 2026
- Reuters (Andrew Mills and Maha El Dahan), “QatarEnergy buys U.S., other LNG to hedge future Hormuz disruptions,” Oct. 29, 2026, carrying CEO Saad al-Kaabi on the revised three-year repair estimate and the 83 percent restart figure
- Reuters (Rami Ayyub, Humeyra Pamuk, Timour Azhari), “US orders diplomats to depart Saudi Arabia amid Houthi strikes,” Oct. 21, 2026, carrying the four U.S. officials on other Gulf missions; AFP, Oct. 22, 2026, citing a diplomatic source on the UAE, Jordan, Qatar and Bahrain
- Middle East Eye live blog, Oct. 21, 2026, carrying State Department spokesman Tommy Pigott’s statement and his public pushback on the scope of the ordered departure
- Saudi General Authority of Civil Aviation (GACA), follow-up statement on the attack targeting King Khalid International Airport, carried by the Saudi Press Agency, Oct. 11, 2026, reporting 12 fatalities and 309 injured; corroborated by Associated Press, Reuters, The Guardian and The Wall Street Journal, Oct. 10–11, 2026
- 12 U.S.C. § 287: shares of Federal Reserve Bank capital stock owned by member banks “shall not be transferred or hypothecated”
- 12 U.S.C. § 289 (Federal Reserve Act § 7), setting the member-bank dividend at the lesser of the 10-year Treasury high yield or 6 percent
B. Verbatim excerpts
Anthony Cordesman, CSIS, “Lessons of Modern War, Vol. II,” chapter 7, the conclusion of the Kharg campaign analysis: “In short, the flow of Iranian exports was far more affected by the growing world oil glut than by Iraqi bombing.” [CORDESMAN] Link
Cordesman, the general lesson he draws from the oil war: “Supposedly critical vulnerabilities generally prove to be easily repairable or subject to substitution, particularly when the country under attack is given time to recover. The net effect of such attacks has generally been to unite a nation in hostility rather than to intimidate it.” [CORDESMAN] Link
Cordesman, on Iraqi losses: Iraq took “serious losses of skilled pilots and of Mirage aircraft,” and each successive attack “became progressively more difficult” as Iran thickened short-range air defences. No Kharg-specific aircraft-loss total is given. [CORDESMAN] Link
Khatam al-Anbiya Central Headquarters spokesperson, March 2026, via Fars, the declared trigger: “In the event of an attack on the oil, economic and energy infrastructure of the Islamic Republic of Iran … all oil, economic and energy infrastructure belonging to oil companies throughout the region that own American stocks or cooperate with the United States will be immediately destroyed.” [POLITICO] Link
The same statement: “They will be destroyed and turned into a pile of ashes.” [POLITICO] Link
CENTCOM, March 13–14, 2026, on the Kharg strikes, as quoted by Politico Europe: more than 90 Iranian military targets destroyed “while preserving the oil infrastructure.” [POLITICO] Link
Foreign Policy, Oct. 30, 2026, the single-component lesson: “A refinery or LNG complex does not need to be hit repeatedly to be taken offline; it needs to lose only one critical component.” [FP] Link
Foreign Policy, on why the interception headline is the wrong metric: the UAE reported intercepting 132 of 137 ballistic missiles on day one, and JINSA estimated over 90 percent intercepted theater-wide, yet the March 18 Ras Laffan attack still destroyed two LNG trains for years. [FP] Link
USNI Proceedings, April 2026, on surprise: “It is highly unlikely the United States could launch an operation against Kharg with any advantage of surprise.” [USNI] Link
USNI Proceedings, on the geometry: the island is 7.7 square miles, flat, holds more than 8,000 civilians, and “Given the island’s lack of cover and proximity to Iran’s shoreline, U.S. forces on Kharg would be extremely exposed.” [USNI] Link
USNI Proceedings, on the holding problem: the 15-day Marine self-sustainment figure comes from the island-seizure analysis generally, not from the Kharg passage. [USNI] Link
USNI Proceedings, on Iran’s resilience: Iran sustained exports below 250,000 barrels a day for several months in 2021–22, against typical output above 3 million, “yet the regime refused to buckle.” [USNI] Link
Joe Kent, former director of counterterrorism, to the Washington Post, as quoted by Zeteo: a Kharg invasion “would be a disaster … It would essentially be giving Iran a bunch of hostages on an island that they could barrage with drones and missiles.” [ZETEO] Link
Harrison Mann, former U.S. intelligence analyst, as quoted by Zeteo: for the troops ordered to take Kharg, “the operation would land somewhere between a suicide mission and a self-imposed hostage crisis.” [ZETEO] Link
Zeteo, March 23, 2026, the casualty estimate, single-outlet and unconfirmed: casualties would very likely be “considerable,” with some estimates “easily in the dozens” for an initial phase and “likely to rise sharply” if the island were held. [ZETEO] Link
Mohammad Bagher Ghalibaf, Iranian parliament speaker, March 25, 2026, on X, as quoted by CNN: “If they step out of line, all the vital infrastructure of that regional country will, without restriction, become the target of relentless attacks.” [CNN7APR] Link
Mehr News Agency, Iran’s semi-official agency, on the March strikes, as quoted by CNN: Kharg’s maritime infrastructure “suffered little damage during US bombing and continues to operate as normal.” [CNN7APR] Link
The Federal Reserve’s own FAQ: “The Federal Reserve System is not ‘owned’ by anyone,” and observers who consider it private have “mistakenly” done so. [FEDFAQ] Link
Energy Secretary Chris Wright, Feb. 13, 2026: “Now we have an account at the U.S. Treasury. The money won’t go to Qatar anymore.” [CNBCWRIGHT] Link
Executive Order 14373, §5(a)(i), requiring Treasury to designate the funds “in a manner that clearly reflects their status as sovereign property of the Government of Venezuela held in custody by the United States, and not as the property of the United States.” [EO14373] Link
Executive Order 14373, on the emergency it declares: “the possibility of attachment or the imposition of judicial process against the Foreign Government Deposit Funds constitutes an unusual and extraordinary threat to the national security and foreign policy of the United States, which has its source in whole or substantial part outside the United States, and I hereby declare a national emergency to deal with that threat.” [EO14373] Link
CPA Regulation No. 2, June 15, 2003: “The Fund will be controlled by the Administrator through a communications protocol … documented in a funds transfer security procedures agreement.” [CPAREG2] Link
The National, April 21, 2026: “Every dollar Iraq gains from selling crude oil enters an account at the Federal Reserve Bank of New York, from which Baghdad makes withdrawals to pay government salaries and imports.” [NATIONAL] Link
IAMB Final Report, 2011: “It is not possible to determine that all Iraqi oil resources during the period since IAMB inception had been used for the benefit of the Iraqi people.” [IAMB] Link
IAMB Final Report, on disbursements: “It was not possible to determine whether all DFI disbursements were made for the purposes intended. Considerable internal control weaknesses were noted at the spending ministries.” [IAMB] Link
SIGIR, July 2010, as carried in the IAMB final report: DoD controls left it unable to properly account for $8.7 billion of the $9.1 billion in DFI funds it received for reconstruction activities. [IAMB] Link
RAND, Scott Savitz, May 19, 2026, on minefields: “The number of mines you need to create an effective minefield is zero. You just need people to perceive that there’s a threat there.” [RAND] Link
Foreign Policy, Oct. 30, 2026, on the confusion of flow with capacity: “This view confuses how much oil and gas are still flowing from the Gulf with the state of the plants and terminals that move it.” [FP] Link
C. Data tables (as of Oct. 31, 2026)
C1. The 1980s record: Iraqi raids on Kharg against Iranian crude exports
| Year | Iraqi raids on Kharg | Crude exports (mb/d) | Oil revenue | Note |
| 1984 | Earlier strikes 1980–84; sustained campaign opens Aug. 14, 1985 | 1.36 | $10.9B | June 24, 1984 raid damaged Sea Island loading; Cordesman calls Aug. 1985 the first successful strike since |
| 1985 | At least 37 by mid-Nov.; nearly 60 by end-Dec. | 1.80 | $12.95B | Exports ROSE year over year, during the raids |
| 1986 | Iraq presses the campaign | 1.50 | $6.81B | Revenue collapse tracks the world price crash, not the bombing |
Sources: Cordesman, CSIS chapter 7. Exports and revenue are Cordesman’s annual figures, as published. The raid counts are his two anchored totals for the 1985 campaign, not a campaign-wide count — Cordesman gives no complete raid total, and none is asserted here.
C2. Attacks on Gulf Cooperation Council non-military infrastructure, Feb. 28 – Jul. 30, 2026
| Country | Attacks on non-military infrastructure | Share of regional total (ACLED) |
| United Arab Emirates | 49 | 28% |
| Kuwait | 43 | 25% |
| Bahrain | 34 | 20% |
| Saudi Arabia | 27 | 16% |
| Qatar | 11 | 6% |
| Oman | 8 | 5% |
| Total | 172 | 100% |
Source: ACLED, Aug. 4, 2026. Percentages are ACLED’s own published shares, rounded as ACLED rounds them. ACLED also reports that these 172 attacks equal about 18% of all Iranian land attacks in the GCC over the period, that 48% hit energy infrastructure, and that more than 70% caused physical damage or fire, with 25 causing casualties.
C3. The calibration, after the June 17, 2026 memorandum of understanding
| Country | Post-MOU attacks | Energy News Beat reading |
| United Arab Emirates | 0 | Escalation deliberately not resumed |
| Qatar | 0 | Mediator; not targeted |
| Oman | 0 | Mediator; not targeted |
| Kuwait | 10 | Hosts U.S. forces |
| Bahrain | 7 | Hosts U.S. Fifth Fleet |
Sources: ACLED, Aug. 4, 2026, cross-read against the Foreign Policy analysis of Oct. 30, 2026. The attack counts are ACLED’s; the readings in the third column are Energy News Beat’s interpretation and ACLED does not offer them. ACLED’s post-MOU subtotals are Bahrain 7, Kuwait 10 and Saudi Arabia 1, totalling 18. The chart shows Kuwait and Bahrain, the two states hosting U.S. forces; Saudi Arabia’s single post-MOU attack fell in the same phase and is noted here.
For context, ACLED phases the campaign in three parts: 150 attacks from 28 February to 8 April, just 4 during the ceasefire from 9 April to 17 June, and 18 from 18 June to 31 July. The near-silence during the ceasefire is itself the point: when Tehran wanted the shooting to stop, it stopped.
C4. Strait of Hormuz flows: the measured disruption
| Quarter | Total oil through Hormuz (mb/d) | of which crude and condensate | LNG through Hormuz (bcf/d) |
| 4Q 2025 | 21.6 | 15.9 | 10.5 |
| 1Q 2026 | 14.9 | 10.9 | (not restated) |
| 2Q 2026 | 4.9 | 3.7 | 0.8 |
Source: EIA Short-Term Energy Outlook, Table 4, released Aug. 12, 2026. The 4Q25 and 2Q26 columns are as published. EIA did not restate a 1Q26 LNG figure in the table as read.
C5. What the United States actually did, March to October 2026
| Date | Action | Oil infrastructure at Kharg |
| March 13–14 | Struck 90+ military targets on and around Kharg | Explicitly spared |
| March 16 | President warns Iran over Kharg and oil exports | Intact |
| March–May | Seizure publicly floated, then shelved as an endgame option | Intact |
| April 13 | Naval blockade imposed | Intact; exports fall anyway |
| June 17 | Memorandum of understanding signed | Intact |
| June 18 | Naval blockade lifted under the MoU | Intact |
| July 14 | Naval blockade reinstated | Intact; exports fall to zero under the reinposition |
| October | Seaborne crude exports outside the blockade zone reach zero | Intact |
Sources: Politico Europe, CNN, CNBC, Kpler, USNI Proceedings, CENTCOM resumption release, Al Jazeera on the June 18 lift. The “shelved” characterization reflects reporting in the Wall Street Journal and Foreign Policy.
C6. The cost of holding Kharg, as estimated in open sources
| Factor | Figure | Source type |
| Island area | 7.7 sq mi | USNI Proceedings |
| Distance from Iranian coast | approx. 16 miles | USNI Proceedings |
| Civilian population | 8,000+ | USNI Proceedings |
| Troops to take and hold | approx. 5,000 | Francis Galgano, via CNBC |
| Marine self-sustainment | approx. 15 days | USNI Proceedings |
| Initial U.S. casualties | “easily in the dozens” | Zeteo, single source |
| Defences encountered | Beach mines, MANPADs | USNI Proceedings |
The casualty estimate is the weakest number in this table: it comes from one outlet citing unnamed officials and has not been confirmed by any named U.S. official. It is flagged as such wherever it appears in the text.
C7. The three corrections, side by side
| Claim as often stated | What the primary source actually says |
| “The Federal Reserve is a privately owned company.” | “The Federal Reserve System is not ‘owned’ by anyone.” Owning Reserve Bank stock is, in its words, “quite different from owning stock in a private company”: ownership is by law a condition of membership, the Reserve Banks are not operated for profit, and they must transfer net earnings to the Treasury. Federal Reserve FAQ |
| “Venezuelan oil money sits in a Bank of Qatar account.” | Reportedly held at Qatar National Bank, a partly state-owned commercial bank, temporarily, as creditor protection for roughly the first $500m. Energy Secretary Chris Wright, Feb. 13, 2026: “Now we have an account at the U.S. Treasury. The money won’t go to Qatar anymore.” CNBC |
| “The U.S. just took the oil money.” | Executive Order 14373 holds it as “sovereign property of the Government of Venezuela … and not as the property of the United States,” immune from creditors, disbursed at the Secretary of State’s direction. OFAC General License 50A authorizes six named companies to operate in Venezuela on condition that any royalty or tax payments are routed into those Treasury accounts. EO 14373 GL 50A |
D. Methodology and how to read the numbers
This article rests on two documents produced before drafting. The first is a 16,800-word strategy memo that triages every claim in it as [FACT], [ESTIMATE] or [SPECULATION] and lists 67 sourced number rows. The second is an independent sourcing-quality review whose only job was to establish what is confirmed versus what is rumour. Where the two disagreed, the more conservative reading won.
- A claim is marked [FACT] only where a named, checkable primary or institutional source states it. Trade-press relays of a single anonymous report do not clear that bar, however many outlets repeat it.
- A claim is marked [ESTIMATE] where a credible institution or reporter produced a figure that is a projection, an assessment or an arithmetic inference rather than a measurement. The $20 billion a year in lost Qatari LNG revenue is an estimate of this kind, and it is labelled as one in the text.
- A [SPECULATION] label is reserved for reasoning about what did not happen. The entire piece is counterfactual, so the reasoning is explicitly marked as reasoning. The distinction between what the record shows and what this article infers from it is drawn in every section.
- The 1980s export figures are Cordesman’s, measured at the time and reported in a 1990 CSIS study. They are the best available series for that campaign and they are not revised estimates.
- Raid counts for the 1980s campaign are given only as the two numbers the record anchors: at least 37 major strikes by mid-November 1985, and nearly 60 by the end of December 1985. Commonly repeated claims of “hundreds” of raids could not be sourced and are not used.
- Attack counts on Gulf infrastructure are ACLED’s, which records incidents rather than munitions. One ACLED attack may represent a salvo and one munition may produce several incidents. Read the counts as an index of pressure, not a body count of projectiles.
- The 172-attack figure covers the six GCC states only and the period 28 February to 30 July 2026. It is not a count of all Iranian attacks in the war.
- Hormuz flow figures are EIA short-term outlook numbers for the quarter named. They are modelled estimates published in August 2026, not tanker-by-tanker counts, and EIA revises them.
- Casualty estimates for a Kharg seizure come from a single outlet citing anonymous officials. No government has published a wargame or an official estimate. The article says so in the text, not only here.
- Dollar figures for Venezuelan and Iraqi revenue describe account structure and legal status, not amounts. No public accounting of balances in either structure was located, and the article does not assert any.
- Where a source is paywalled and was read through a syndication, the citation says so. The Reuters explainer on Iraqi oil revenue was read through Al-Monitor and The National, and the Wall Street Journal reporting was read through a full-text syndication. Nothing was cited that was not read somewhere in full.
- No figure in this article was generated by a model, inferred from a chart, or carried over from another article. The substantive figures trace to rows in the source list above.
E. Could not verify
Listed plainly, so that nothing here reaches air or print as fact. Each item below is either absent from the article or explicitly labelled as unconfirmed where it appears.
- Any public, detailed U.S. wargame of a Kharg seizure with casualty figures. No institution — CSIS, RAND, CNAS, Heritage, IISS or RUSI — has published one. The only casualty figure in circulation is Zeteo’s 23 March 2026 report of casualties “easily in the dozens” in an initial occupation phase, resting on anonymous sources at a single outlet. It is flagged as single-source everywhere it appears.
- A Kharg-specific Iraqi aircraft-loss total for the 1980s campaign. Cordesman confirms “serious losses of skilled pilots and of Mirage aircraft” but gives no number. None is given here.
- A total raid count for the entire 1980s Kharg campaign. The verified anchors are at least 37 by mid-November 1985 and nearly 60 by the end of December 1985. Figures of “hundreds,” or any definitive campaign total, could not be sourced and are not used.
- The exact identity and terms of the Qatar account. Chris Wright said an account “was set up in Qatar, controlled by the U.S. government the whole time, to land that money in and then send the money from there down to Venezuela.” Reporting in Venezuelan and regional outlets places it at Qatar National Bank. No primary document naming the institution, the account holder or the terms was located. The article says “reportedly at Qatar National Bank” and attributes the rest to Wright.
- Who physically holds and disburses Venezuelan oil proceeds inside Treasury, and under what authority beyond EO 14373. The order is clear on custody and on State Department direction of disbursement; it is not clear on account mechanics, and no Treasury statement of the account structure was located.
- Whether any independent audit of the Venezuelan accounts exists. None was located. The Schumer–Schiff request for a GAO audit is a request; its status is unverified.
- Whether the EO 13303 national emergency has been continued, and on what date. Executive Order 13668 left it expressly in place (“which shall remain in place”), and it was continued for one year by the notice of May 4, 2026, published at 91 FR 25071, extending it beyond May 22, 2026 under 50 U.S.C. 1622(d).
- Iran’s claimed mining of six commercial vessels on the southern route in late October 2026. An Iranian claim; UKMTO confirms an attack on one ship in the area. Unverified as to the six, and the six are not printed.
- The 24 and 26 October 2026 Houthi claims against Saudi East–West pipeline pumping stations. Unconfirmed per Foreign Policy, and labelled as a claim only.
- The claimed Chinese YJ-12 transfer to Iran before Operation Epic Fury. Unconfirmed, with no verified use. The Hudson Institute raises it as a possibility, not a finding.
- Iranian “missile city” capacities and the specifics of underground facilities. Sourced largely to Iranian state media and IRGC sources. Treated as adversary claims, not verified capability.
- Whether any Kharg oil infrastructure has been deliberately struck by the U.S. As of the record reviewed, no. Strikes in March and April 2026 explicitly preserved the oil infrastructure. A suspected oil slick near the terminal in May 2026 was reported from satellite imagery and denied by Iran, with no attribution established.
- Total American combat deaths in the war to date. Not established in the sources reviewed. There has been no U.S. ground operation on Kharg, so there are no Kharg ground casualties — that much is safe to say, and is all the article says.
- The Reuters explainer “How the U.S. controls Iraq’s oil revenues” (23 January 2026) in full text. Paywalled. Its substance was confirmed through the Al-Monitor syndication and The National’s reporting, and it is cited that way.
- The exact Turkish Petroleum Company shareholding percentages after San Remo (Anglo-Persian 47.5%, Shell 22.5%, CFP 25%, Gulbenkian 5%). Widely reported and consistent with the 25% French allocation in the primary text, but no primary document establishing those precise percentages was located. They are not attributed to a primary source here.
- Any current, credible reporting that a Kharg seizure, or a strike on Kharg’s oil infrastructure, is imminent. This is the most important non-finding in the whole exercise. See section F below.
- A reliable total for Iraqi aircraft losses specifically during the Kharg campaign, as distinct from Iraq’s overall wartime attrition.
- Reports of explosions at or near Kharg on 29–30 October 2026. Carried by Iranian and regional outlets and attributed by some to a strike. The originating report hedged toward a possible technical failure at the terminal, which is not a strike indicator; no imagery, official confirmation or second independent outlet has established a cause. It is listed here as an unverified report and is not treated as evidence of an attack anywhere in this article.
F. What the reporting on Kharg actually shows
This section exists because of a specific instruction: if there is not substantial and verifiable reporting that the United States is about to attack Iran, nothing false goes out. There is not. Here is the full audit trail, so a reader or an editor can see exactly what was checked and how the piece handled it.
F1. The October news cycle traces to one origin
| Outlet | Date | What it added |
| Erem News (UAE) | Oct. 19, 2026 | The origin. Reports a planned Kharg operation, citing unnamed diplomatic sources. |
| Israel Hayom | Oct. 19–20 | Relays Erem. No independent sourcing. |
| Moneycontrol | Oct. 20 | Relays Erem. No independent sourcing. |
| JFeed | Oct. 20 | Relays Erem. No independent sourcing. |
Four outlets is not four sources. Each of the three downstream reports cites the same single origin, and none adds a named official, a document, or a second line of reporting. Presenting this as a multi-sourced story would be inaccurate, and this article does not.
F1b. Why a Kharg story keeps finding oxygen
The October report did not arrive in a vacuum. Kharg has been proposed, threatened and imagined often enough that old material recirculates easily, and a reader who half-remembers one of the following can be forgiven for thinking a decision is close.
- In March 2026, Axios reported that the President was considering occupying or blockading Kharg to force Iran to reopen Hormuz. Reuters carried it with the caveat that no decision had been made. That was a reported option, eight months ago.
- On 11 June 2026 the President said the United States would, in his words, be “taking Kharg Island, and other oil infrastructure points” at some point in the not too distant future — and called the strikes off hours later, citing diplomatic progress.
- On 30 August 2026 a video circulated showing Kharg in flames. It was generated — Lead Stories tested it with Hive Moderation, ZeroGPT and FauxLens — and the Defense Department confirmed that Kharg had not been struck. CENTCOM said the strikes that day hit two rocket launchers on Larak Island instead.
- Yair Lapid, until this week Israel’s opposition leader — his bloc took 48 seats in the 27 October election and is now negotiating to form a government — has publicly called for Israel to “destroy all of Iran’s oil fields and energy industry on Kharg Island,” a position he has held since at least March 2026 and pressed through the campaign, where Al Jazeera reported him calling for the bombing of Kharg’s energy facilities. This is a foreign opposition politician’s argument, now carried into a coalition negotiation rather than a stump speech. It is not American policy, and it is worth naming because it is a plausible reason the idea feels more imminent in circulation than it is in the record.
None of these is evidence of a decision. Together they explain how a thin report can land on ground already prepared for it.
F2. The flight-tracking claims do not resolve to aircraft
Open-source accounts circulated in late October describing specific cargo and military flights said to be positioning for a Kharg operation. As reported, those claims carry no tail numbers, no aircraft types and no verifiable call signs. A flight-tracking claim without a registration number cannot be checked and is not evidence. It is not used here.
F3. The August video of Kharg exploding was AI-generated
A video posted to Truth Social in August 2026 purported to show Kharg Island being destroyed. It was not real. Lead Stories checked it with Hive Moderation, ZeroGPT and FauxLens and found it likely AI-generated, and established that Kharg itself was not attacked. CENTCOM said the strikes that day hit two rocket launchers on Larak Island instead. Anyone who shared that video in good faith was sharing a fabrication, and repeating it now would compound the error. This article states plainly that the video was fake.
F4. Three indicators that point the other way, checked and reported
Rumours of an imminent strike are usually supported by the same short list of observable signals: a bomber deployment, an evacuation of American civilians, and unusual military movement visible to the daily monitors. Each was checked against the record this week. All three are negative.
- No bomber package. Satellite imagery of Diego Garcia taken on 24 October and reported by The Maritime Executive two days later found “there are no B-2 or B-52 long-range bombers present.” The apron was filling instead with transports and maritime patrol aircraft. A dozen B-1Bs at RAF Fairford flew home in early October, ending that base’s role as a launchpad. The movement of heavy bombers in October was out, not in.
- The evacuation is narrower than it sounds. State Department spokesman Tommy Pigott, named and on the record, said the department had “issued an ordered departure for non-emergency U.S. government employees and their family members in Saudi Arabia only,” and he pushed back on reports that it might extend to other Gulf states, though Reuters reported four U.S. officials saying missions in other Gulf states would also send family members home, and AFP cited a diplomatic source saying families in the UAE, Jordan, Qatar and Bahrain had been told to leave. The order was attributed to Houthi attacks on the kingdom — including a strike on Riyadh airport on 10 October that, per the Saudi civil aviation authority, killed 12 people and injured 309 — not to preparations for a strike on Iran. An ordered departure is not an evacuation of citizens, and it is not pre-strike staging. Reading it as either is a misreading of a document that says something else.
- The daily military monitors recorded nothing under that heading. The Institute for the Study of War and the Critical Threats Project run the most strike-attentive public tracking of this war. Under “US and Partner Military Operations,” their Iran Update carried “nothing significant to report” on every weekday edition that week — 26, 27, 28, 29 and 30 October. Their weekend editions are abbreviated and cover the Houthi-Saudi conflict, so they are not evidence either way. That section tracks U.S. and partner strike activity specifically; the same updates do report Iranian minelaying and Houthi attacks elsewhere.
None of this proves a strike will not happen. It establishes that the observable indicators a careful analyst would look for were absent in the final week of October, and that the stories implying otherwise rested on something other than those indicators.
F5. What is actually established
- The United States struck more than 90 military targets on and around Kharg in March 2026, while explicitly preserving the oil infrastructure.
- The United States struck again in April 2026. No ground seizure has occurred at any point.
- Seizure was discussed publicly for months and repeatedly shelved as an endgame option.
- A naval blockade imposed in April 2026 drove Iranian seaborne crude and condensate exports to effectively zero by October 2026, with roughly 43 million barrels stranded inside the blockade zone.
- Plans for renewed strikes after the 3 November midterms have been reported independently by the AP and the Wall Street Journal. As of this writing the President had not approved them, and Iran and Qatar were mediating, with a draft delivered 25 October 2026.
That is the record. It supports a counterfactual about a road not taken. It does not support a prediction, and this article makes none.
F6. Claims commonly made that this article does not make
| Claim as usually stated | Verdict | The accurate version |
| “The U.S. seized Kharg Island.” | False | More than 90 military targets struck in March 2026 with the oil infrastructure preserved. No ground seizure. |
| “The U.S. is about to attack Kharg.” | Not supported | Plans reported for after the midterms; not approved. Seizure shelved. Mediation under way. |
| “Iran closed the Strait of Hormuz.” | Partly | Iran made transit uninsurable rather than physically closing it. Flows fell about 77%, not to zero. |
| “The U.S. blockade stopped Iranian exports.” | Correct | Seaborne crude and condensate effectively zero in October 2026, approx. 43 million barrels stranded. |
| “The Federal Reserve is a private company.” | Incorrect | “The Federal Reserve System is not ‘owned’ by anyone.” Net earnings, after necessary expenses, legally required dividend payments, and maintaining a limited balance in a surplus fund, are transferred to the Treasury. |
| “Venezuelan oil money runs through the Bank of Qatar.” | Out of date | Reportedly Qatar National Bank, temporary. Since 13 February 2026 it goes to a Treasury account. |
| “EO 13303 gave the U.S. control of Iraqi oil.” | Misleading | It immunised Iraqi proceeds from creditors. Control came from the account structure and the disbursement protocol. |
F7. A note on the phrase “pile of ashes”
The Khatam al-Anbiya statement is quoted verbatim in this article because it is the clearest public statement of Iran’s declared trigger, and because events in the Gulf subsequently tracked it. It is a threat made by an Iranian military headquarters, reported by Politico Europe. It is not a U.S. assessment and it is not this publication’s characterization of what a strike would do. The distinction matters and is preserved in the text.
G. Corrections to premises in circulation
Two premises that circulate widely, including in commentary this publication respects, do not survive contact with their own primary sources. Correcting them makes the underlying argument stronger, not weaker, because what replaces them is more consequential and is documented.
The first is the ownership of the Federal Reserve. The claim that it is a privately held company is contradicted by the Fed’s own FAQ: “The Federal Reserve System is not ‘owned’ by anyone,” and observers who consider it private have “mistakenly” done so. Member-bank stock ownership is, by law, a condition of membership; Section 287 of Title 12 provides that the shares “shall not be transferred or hypothecated,” and § 289 caps the dividend at the lesser of the 10-year Treasury high yield or 6 percent; and the Reserve Banks are “not operated for profit” and must transfer net earnings to the U.S. Treasury after expenses, dividend payments and a limited surplus. The Board of Governors is a federal agency. What is true, and what the article argues, is that the Fed is a chokepoint — the dollar-clearing system gives the United States leverage over other countries’ oil revenue that no other country has. That claim needs no theory of private ownership to stand.
The second is the Qatar account. There is no institution called “the Bank of Qatar.” The account was reportedly at Qatar National Bank, a partly state-owned commercial bank, and it was a temporary creditor-protection device used for roughly the first $500 million, chosen because a newly opened U.S. account could have been frozen by Venezuela’s creditors. Since 13 February 2026, per Energy Secretary Chris Wright, “The money won’t go to Qatar anymore.” It goes to the U.S. Treasury. The accurate version of the claim is stranger than the inaccurate one: under Executive Order 14373, the money is held as “sovereign property of the Government of Venezuela … and not as the property of the United States,” immune from creditors, disbursed at the Secretary of State’s direction, and subject to the quarterly reporting General License 50A requires to State and Energy — but not to an independent audit.
H. A note on what this article is not
It is not a prediction. It is not sourced to the October reporting cycle, which traces to a single anonymous origin and is treated accordingly. It does not repeat the August video, which was generated. It does not describe an attack as imminent, because the record does not support that and because this publication will not put something out that the evidence cannot carry.
What it is: an attempt to answer a question honestly that most coverage has answered carelessly. The United States has already bombed Kharg and has already achieved the oil-denial outcome a seizure was meant to deliver. The interesting question is therefore not whether the United States could take the island. It is what taking it would have cost, and whether the retaliation it invited would have been worth a prize t