
Energy News Beat | September 19, 2026
The world’s long-haul crude system is running out of the ships that make it work. Bloomberg reported today that soaring freight costs are already making some distant crude trades uneconomic, with barely any Very Large Crude Carriers left for hire in parts of the market.
That shortage is not a side story. It is the mechanism through which three distressed chokepoints — the Strait of Hormuz, the Bab el-Mandeb, and the Black Sea — are forcing a violent rebalancing between sellers who can still move barrels and buyers who can still receive them.
A VLCC is a floating pipeline: roughly two million barrels, three football fields long, and the workhorse of Middle East-to-Asia and Atlantic-to-Asia crude. When those ships are trapped, waiting, shuttling, or simply too expensive, oil does not disappear. It changes destination, changes owner, and often never reaches the refinery that expected it.
Hormuz Did Not Close Cleanly. It Became a Shuttle System.
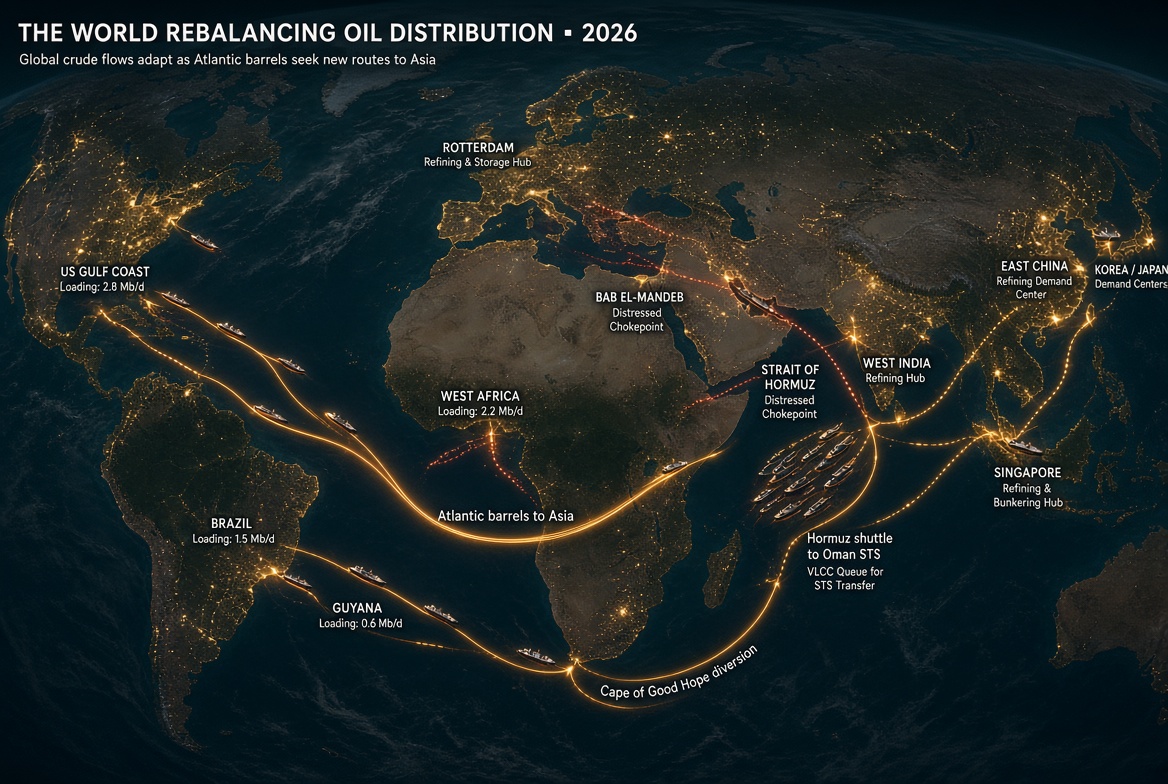
The US-Iran war that began in late February fractured the old loading pattern. Instead of a VLCC sailing into the Persian Gulf, loading at Ras Tanura, Basrah, or Fujairah, and steaming to Asia, much of the remaining Gulf crude now moves in two legs.
Shuttle tankers still enter the Gulf, load, and run the strait. Then they transfer cargo ship-to-ship off Sohar, Oman, or Fujairah, to a long-haul VLCC that never enters Hormuz. Saudi Arabia intensified that workaround after drone attacks knocked its East-West pipeline offline, closing the main land route that had been used to bypass the strait. Loadings have climbed back toward several million barrels a day, but the method is brutally inefficient.
Each STS transfer takes 24 to 40 hours. Shuttle ships cycle back through the strait. Long-haul VLCCs sit in a growing queue in the Gulf of Oman. Brokers estimate around 15 percent of the global VLCC fleet is already tied up, to some degree, in Hormuz shuttle work. That is capacity removed from the spot market even when the oil eventually leaves.
Freight has priced that inefficiency in real time. Lloyd’s List reported Gulf of Oman VLCC earnings up about 250 percent month to date, with the Baltic Oman-China index near $871,000 a day and fixtures discussed above $900,000. The theoretical MEG-China TD3C index has printed even higher. West Africa-China and US Gulf-China rates have more than doubled this month as the same ships are pulled toward Oman.
Bloomberg’s point follows directly: faraway barrels become less attractive when the ride costs more than the crude. Refiners grab whatever is closer — US Gulf, Brazil, Guyana, West Africa — if they can find it. That is rebalancing by freight, not by OPEC communiqué.
Two More Chokepoints Are on Fire
Hormuz is only one broken valve.
The Bab el-Mandeb, the southern gate of the Red Sea, was supposed to be Saudi Arabia’s escape hatch. After Hormuz seized up, Riyadh pushed crude across the East-West pipeline to Yanbu and sent it south toward Asia. Houthi advances — including the seizure of Mocha, the Hanish islands, and Perim Island — have put a landlord on that strait. Saudi-linked traffic has been targeted. Cargoes that still want Asia are being forced north through Suez, then around Africa, adding weeks and more tonne-miles to the same barrel.
The Black Sea is not a VLCC theatre in the same way, but it is another fire under the refined-product side of the market. Russia and Ukraine have spent 2026 striking commercial shipping, shadow-fleet tankers, and refineries. Türkiye says attacks on civilian ships surged this year and has floated a new safe-passage proposal. Every damaged tanker, delayed cargo, or offline Russian refinery tightens diesel and fuel oil even if crude still exists on paper.
Sellers with Atlantic Basin barrels and buyers with Atlantic Basin refineries are relatively favored. Sellers sitting behind Hormuz or Bab el-Mandeb, and Asian refiners that built their systems on AG grades, are not. US crude exports have hit record highs. Brazil, Guyana, and West Africa have become the replacement long-haul supply. That is the new map.
The Fleet Was Already Old Before the War
The shortage did not start in February. It was baked in by a decade of under-ordering, an aging fleet, and a sanctioned “shadow” fleet that no longer serves the compliant market.
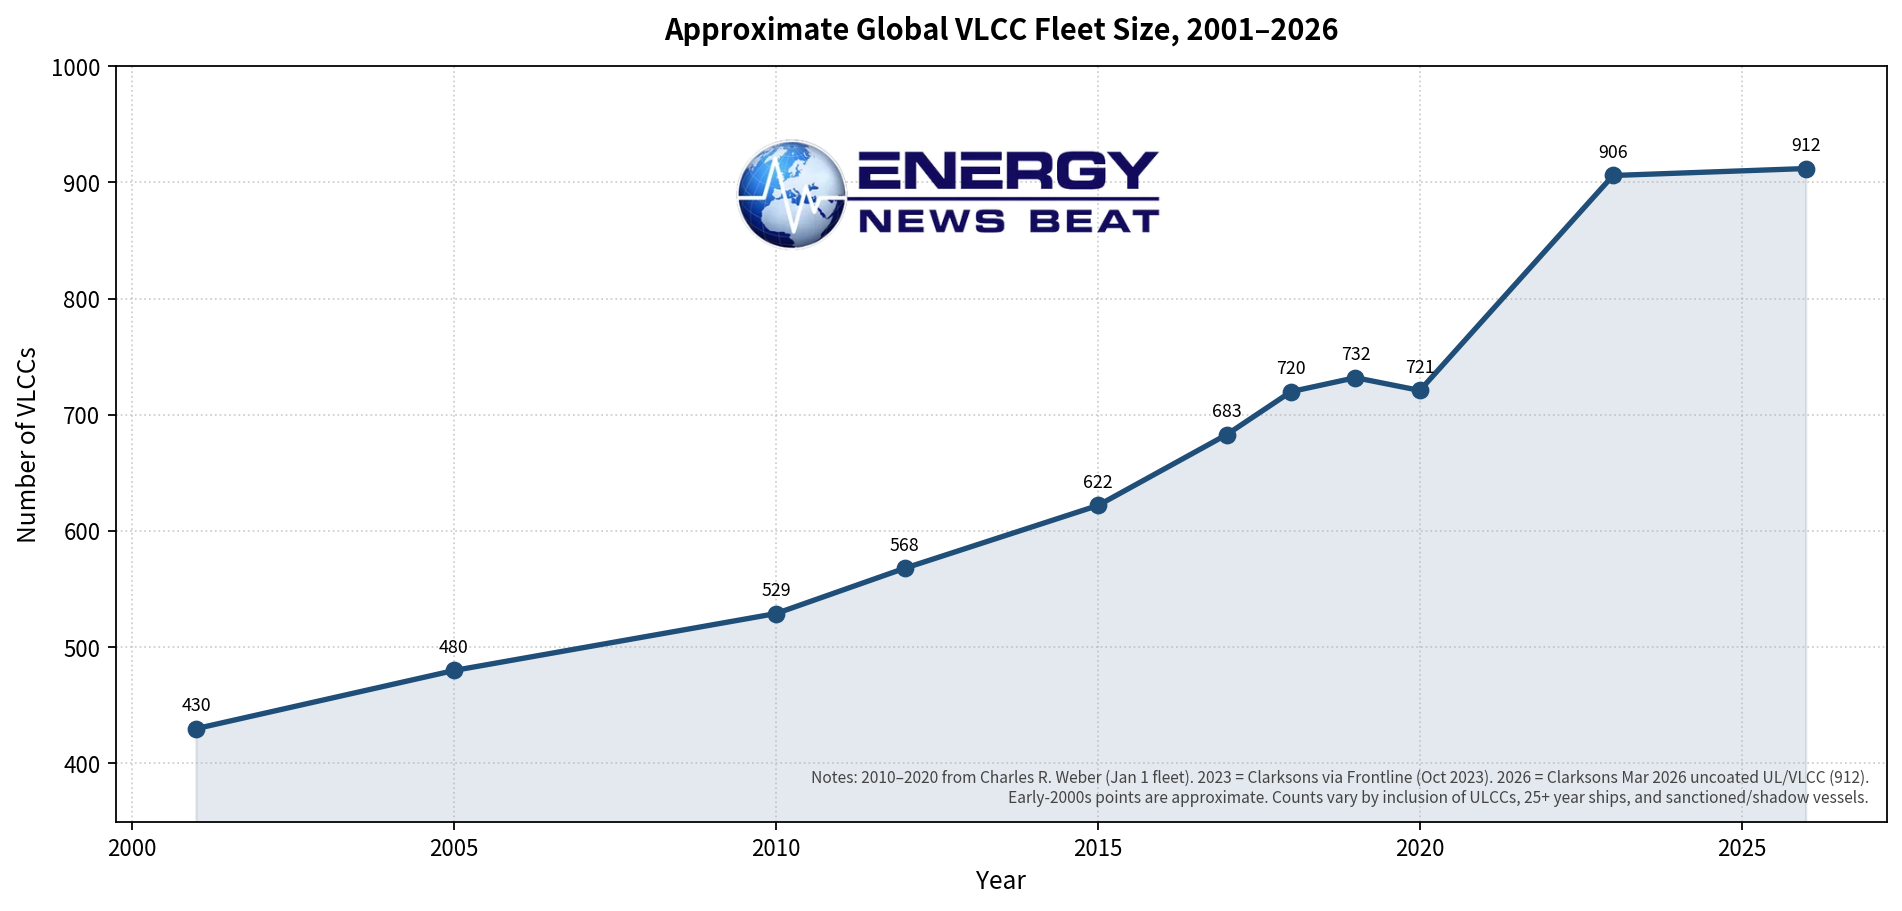
Approximate fleet snapshots over the last 25 years show how the arithmetic changed. Charles R. Weber’s January 1 counts put the VLCC fleet at 529 ships in 2010, 622 in 2015, 732 in 2019, and 721 in 2020 after a brief contraction. Clarksons data cited by Frontline counted 906 VLCCs in October 2023. Clarksons’ March 2026 world fleet table showed 912 uncoated UL/VLCCs. Other owner filings, which strip out very old ships or treat sanctioned tonnage differently, print closer to 850–870. The headline fleet grew. The usable fleet did not grow with it.
Roughly one in five VLCCs is now more than 20 years old. Five years ago that club numbered fewer than 20 ships; recently it has been around 130. A large share of those vintage ships work sanctioned trades and will not return to BP, Shell, or Sinopec-vetted service. About 17 percent of VLCC capacity has been under sanction in Clarksons’ recent tallies. Effective supply is the compliant, insurable, SIRE-acceptable fleet — not the IMO number on a rusty hull.
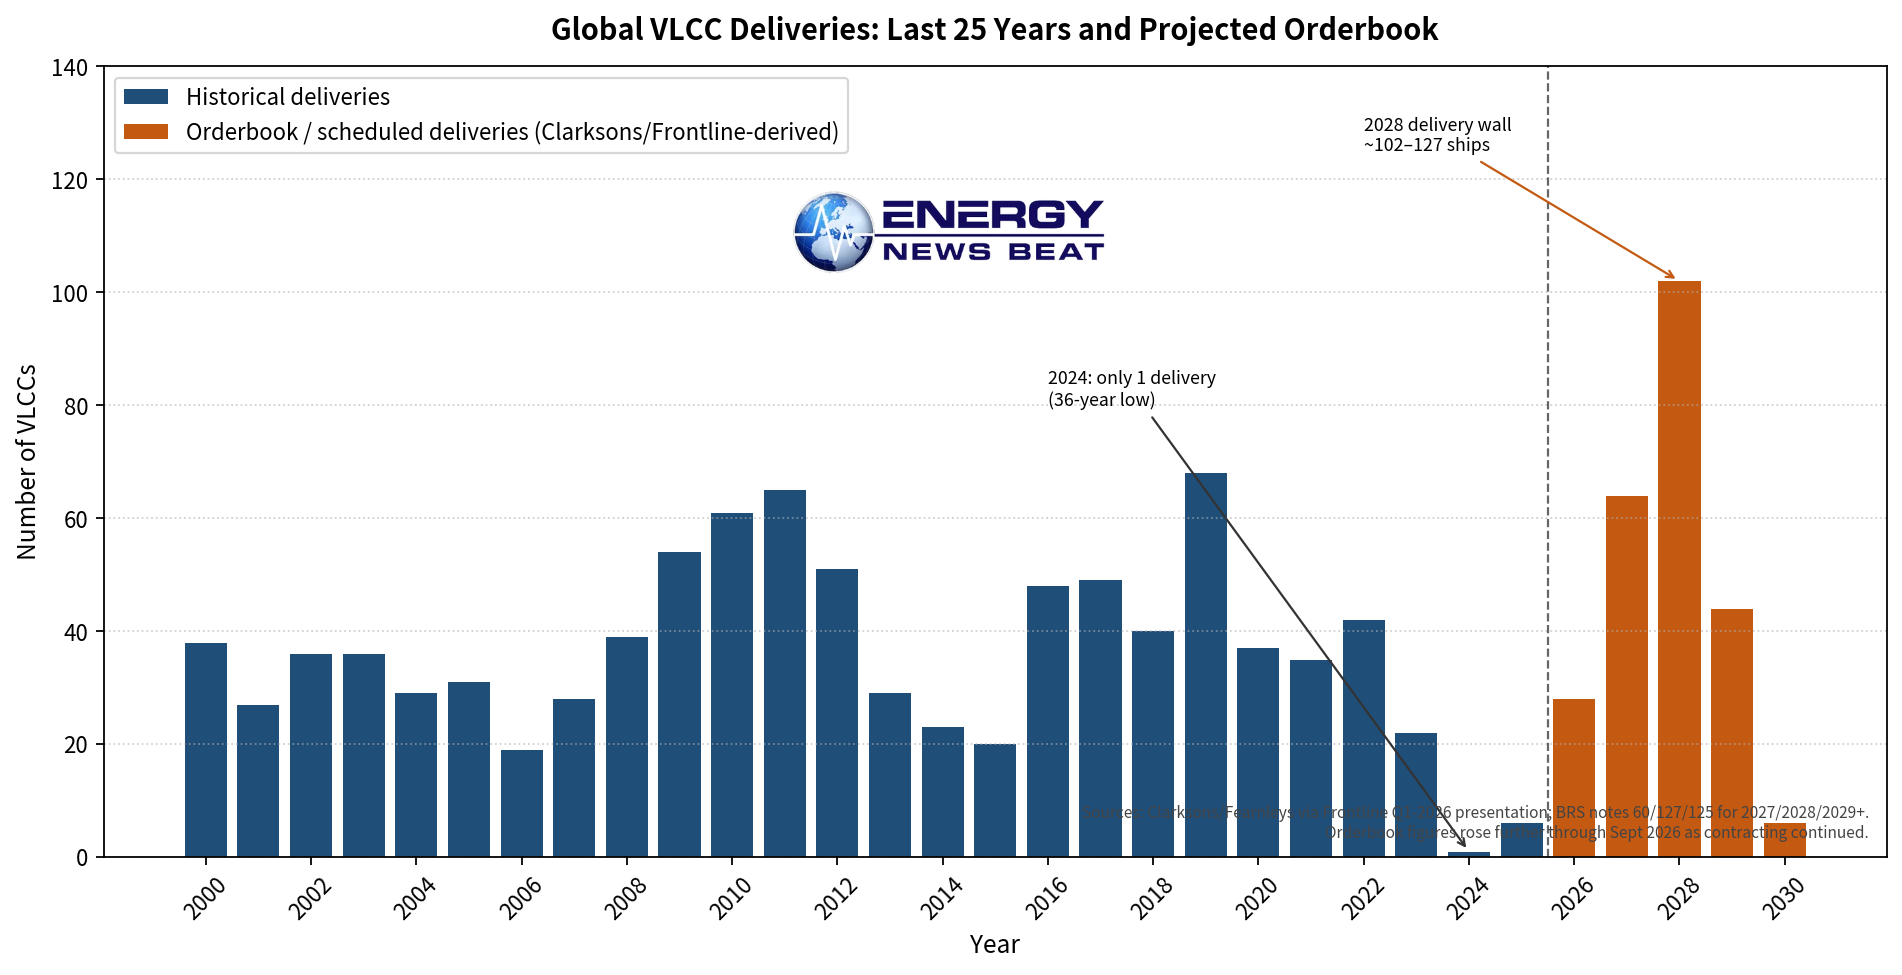
Then came the delivery drought. Only one VLCC was delivered in 2024, a 36-year low. 2025 added a handful. Historical average deliveries were around 40 a year. The industry simply stopped replacing itself while it argued about fuels, CII, and EEXI.
That is why today’s market can be short even while owners place the largest VLCC order wave in at least 25 years.
Record Orders Will Not Rebalance 2026. They May Overshoot 2028.
Shipowners have answered the rate spike with a checkbook. Signal Group counted 217 VLCC orders in 2026 through mid-September, versus 93 in all of 2025. Allied Shipbroking had 164 versus 83. MSI said H1 2026 alone contracted 177 VLCCs totaling 54.5 million dwt — more than any previous full year, including the 2006 record of 32.6 million dwt. Clarksons had already put the orderbook at 262 ships by June, about 30 percent of the existing fleet, above the 2008 peak that later crushed rates. Later broker notes put the orderbook-to-fleet ratio near 35 percent. The buying spree is worth more than $20 billion. Newbuild prices are about $130 million a ship. In a reversal of normal economics, a 10-year-old VLCC has at times cost as much as, or more than, a new one.
Delivery timing is the trap. Most of this wave does not arrive in time to fix Hormuz.Clarksons/Fearnleys figures compiled from Frontline’s Q1 2026 presentation show the shape of the pipeline: a thin 2024–2025, a modest 2026, then a wall.
|
Year
|
VLCCs delivered or scheduled
|
Status
|
|---|---|---|
|
2000–2008
|
19–39 per year
|
Historical
|
|
2009–2011
|
54, 61, 65
|
Post-2008 boom peak
|
|
2019
|
68
|
Cycle high
|
|
2024
|
1
|
Record low
|
|
2025
|
6
|
Still depressed
|
|
2026
|
~28
|
Mix of deliveries and remaining year slots
|
|
2027
|
64
|
Orderbook (BRS has cited ~60)
|
|
2028
|
102
|
Orderbook (BRS has cited ~127)
|
|
2029
|
44
|
Orderbook (BRS: 125 in 2029 and beyond, combined)
|
|
2030
|
6+
|
Incomplete; more will be added
|
MSI warned that about 83 percent of H1 2026 orders are slated for 2028 and 2029, and that H1 contracting more than doubled scheduled 2028 deliveries. BRS’s mid-year schedule — 60 ships in 2027, 127 in 2028, 125 in 2029 and after — is even heavier. Either way, 2028 is the year the steel arrives. 2026 is the year the market is short.
Until then, shuttle operations, Cape rerouting, floating storage, and war-risk delays keep burning extra sea-days per delivered barrel. Arrow and other brokers have described the current freight system as “tonnage-inefficient.” That is why a record orderbook and a spot shortage can exist in the same sentence.
JPMorgan Has Stopped Pretending It Knows the Endgame
JPMorgan’s commodities desk said this week it no longer has a baseline oil outlook — a rare admission from one of the most watched energy teams on Wall Street. Natasha Kaneva wrote that the bank does not know how to model the endgame. The “economic red lines” that were supposed to force a Hormuz reopening — crude above $100, gasoline near $5 a gallon, diesel at record highs, the 10-year yield above 5 percent — have been crossed. The exit ramp is less clear, not more.
JPMorgan put September Brent fair value around $90 against prices near $106. That gap is not a forecast that oil “must” fall. It is the market charging a premium for further losses on top of an estimated 10 million barrels a day already disrupted. Inventories have drawn, but by less than the bank first expected. Demand is running millions of barrels a day below year-ago levels because prices and missing products destroy consumption even as crude looks tight. The bank also flagged Bab el-Mandeb risk, the Saudi pipeline hits, and continued attacks on Russian refining and Ukrainian cities.
That is not a tidy “oil goes down from here” call. It is a confession that the balancing item is political, not a spreadsheet.
Are Analysts Saying Oil Will Fall Because Refineries Are the Real Bottleneck?
Some are saying the shape of the crisis has moved downstream. They are not, as a group, calling for a collapse in crude.
The IEA’s September Oil Market Report is blunt: refinery throughputs peaked at 81.4 million barrels a day in August, still 4.2 million barrels a day below a year earlier. Global runs are forecast down 2.6 million barrels a day in 2026. The jump in crude futures is large. The jump in refined products is larger. US diesel/gasoil has traded at the equivalent of more than $200 a barrel, nearly double pre-war levels. Atlantic Basin refining margins have hit records because the missing barrel is often a molecule of diesel, jet, or naphtha, not just a VLCC of crude sitting off Oman.
That is the refinery bottleneck. Middle East and Russian plants have been damaged or starved of crude. Asian plants have cut runs because AG barrels cannot arrive on the old schedule. Chinese intake has been estimated well below year-ago levels even when crude is offered, because margins, stocks, and weak domestic demand argue against filling every tank. Kpler raised its 12-month North Sea Dated forecast to $81 from $73 on the view that H2 2026 flipped from surplus to deficit — and still argued Chinese refiners are why prices are not higher.
The EIA’s September STEO now sees Brent averaging about $90 in the second half of 2026, then sliding toward $74 in 2027 as shut-in Middle East production returns and inventories rebuild. That is a lower-later path, not a lower-now path. Earlier summer polls that cut 2026 averages toward the mid-$80s assumed a cleaner Hormuz reopening than the market actually got.
So the honest analyst split is this:
Near term: crude stays supported, products stay more supported, and freight can ration long-haul barrels even if headline supply exists.
If Hormuz and Bab el-Mandeb reopen in a hurry: crude can fall fast, because the market will price a glut before the ships and refineries have actually caught up.
If the shuttle-and-cape system becomes the base case through winter: diesel and freight stay the crisis, crude holds a war premium, and VLCC rates remain the binding constraint on who gets oil.
Nobody serious is arguing that a refinery bottleneck automatically means cheaper oil tomorrow. A bottleneck in diesel usually means expensive oil and expensive freight until either demand breaks or the ships and plants come back.
What Rebalancing Actually Looks Like
Rebalancing in this market is not a return to 2025 routes.
It is a new allocation:
Sellers. Gulf producers that can still shuttle to Oman sell, but at a discount to freight and risk. Atlantic producers sell more, farther, and into Asia. National oil companies are buying VLCCs because they no longer trust the spot fleet to enter a war zone. ADNOC, Saudi shipping arms, and other state players have been shopping secondhand tonnage. Control of the ship is becoming part of the export license.
Buyers. Asian refiners take more US, Brazilian, and West African crude, or they run less. European refiners compete for the same Atlantic barrels and for whatever products still leave the Gulf and the Black Sea. The winner is whoever can pay the freight.
Ships. The 2026–2027 fleet cannot be wished into existence. The 2028–2029 fleet may be too large if the war ends and old ships are not scrapped. That is the 2008 rhyme everyone in Piraeus and Singapore is already telling. MSI, Braemar, and Breakwave have all warned that today’s contracting boom can become tomorrow’s glut — after it first fails to relieve this year’s squeeze.
The global oil market is short VLCCs in the only sense that matters: short the ships that will load, insure, and arrive this winter. Until that changes, oil will rebalance the hard way — through freight rates, shuttered refinery units, and a growing queue of supertankers sitting just outside the Strait of Hormuz, waiting for a shuttle that still has to run the gauntlet.
We have some real concerns developing. As the world rebalances oil, we are seeing the number of cyber attacks on tankers increase. As the global shipping fleet becomes more autonomous, cybersecurity becomes a bigger problem.
Making Appendices Great Again
Check out the World’s Greatest Podcast Show Notes at EnergyNewsBeat.co or EnergyNewsBeat.com.
Subscribe to the Energy News Beat Substack: https://theenergynewsbeat.substack.com/
Appendix: Sources and Links
Tanker shortage and freight
- Bloomberg, “World Running Short of Supertankers Threatens Long-Haul Oil Flow,” Sept. 19, 2026: https://www.bloomberg.com/news/articles/2026-09-19/world-running-short-of-supertankers-threatens-long-haul-oil-flow
- Lloyd’s List, “Gulf of Oman VLCC rates up 250% month to date, nearing $900K per day,” Sept. 18, 2026: https://www.lloydslist.com/LL1158479/Gulf-of-Oman-VLCC-rates-up-250-month-to-date-nearing-900K-per-day
- Splash247, “Tanker boom breaks every historical benchmark,” Sept. 15, 2026: https://splash247.com/tanker-boom-breaks-every-historical-benchmark/
- Lloyd’s List, “Tanker boom of 2026, now second-best in history,” Aug. 4, 2026: https://www.lloydslist.com/LL1158100/Tanker-boom-of-2026-now-secondbest-in-history-shows-no-signs-of-abating
Hormuz shuttle / Gulf of Oman STS
- AGBI, “Saudi shuttling oil through Hormuz after pipeline closure,” Sept. 18, 2026: https://www.agbi.com/analysis/oil-and-gas/2026/09/saudi-shuttling-oil-through-hormuz-after-pipeline-closure/
- Seatrade Maritime, “Hormuz shuttle tankers: An evolving trend amid the Iran War,” Sept. 17, 2026: https://www.seatrade-maritime.com/tankers/hormuz-shuttle-tankers-an-evolving-trend-amid-the-iran-war
- OilPrice.com, “Hormuz Tanker Traffic Slumps as Saudi Arabia Scrambles for New Oil Routes,” Sept. 18, 2026: https://oilprice.com/Latest-Energy-News/World-News/Hormuz-Tanker-Traffic-Slumps-as-Saudi-Arabia-Scrambles-for-New-Oil-Routes.html
- Al Jazeera, “Oman oil escape route: How ship-to-ship transfers work,” Sept. 18, 2026: https://www.aljazeera.com/news/2026/09/18/oman-oil-escape-route-how-ship-to-ship-transfers-work-despite-big
- Reuters, “The US is using an Iranian smuggling tactic to sneak oil out of the Gulf,” June 16, 2026: https://www.reuters.com/business/energy/us-is-using-an-iranian-smuggling-tactic-to-sneak-oil-out-of-gulf-2026-06-16/
- News18 explainer on STS transfers, Sept. 18, 2026: https://www.news18.com/explainers/bypassing-strait-of-hormuz-when-dangerous-ship-to-ship-movement-becomes-the-safe-option-for-oil-transfer-ws-eklt-10339067.html
Bab el-Mandeb / Red Sea
- CNN Business, “The Bab al-Mandeb Strait… is in jeopardy,” Sept. 11, 2026: https://www.cnn.com/2026/09/11/business/bab-al-mandeb-strait-houthi-global-economy
- Reuters, “Cutting off Red Sea oil route may be one crisis too many,” July 23, 2026: https://www.reuters.com/commentary/reuters-open-interest/cutting-off-red-sea-oil-route-may-be-one-crisis-too-many-2026-07-23/
- Kpler, “Can Saudi Arabia keep its Red Sea oil exports flowing without Bab el-Mandeb?”: https://www.kpler.com/blog/explainer-can-saudi-arabia-keep-its-red-sea-oil-exports-flowing-without-bab-el-mandeb
- Windward, “The Houthis Take Perim as Saudi’s Petroline Is Hit,” Sept. 17, 2026: https://windward.ai/blog/houthis-take-perim-and-petroline-is-hit-as-freight-rates-soar/
- Middle East Monitor, Bab al-Mandeb traffic halt, Sept. 17, 2026: https://www.middleeastmonitor.com/20260917-bab-al-mandeb-straits-shipping-traffic-comes-to-halt-amid-conflict-in-yemen/
Black Sea
- Al Jazeera, “Russia kills eight people in Ukraine, attacks two vessels in Black Sea,” Sept. 19, 2026: https://www.aljazeera.com/news/2026/09/19/poland-on-high-alert-as-russia-claims-black-sea-vessel-strikes
- Malay Mail / Türkiye safe-passage proposal, Sept. 18, 2026: https://www.malaymail.com/news/world/2026/09/18/turkiye-proposes-russiaukraine-deal-to-curb-black-sea-attacks-eyes-a-revived-safepassage-mechanism-for-civilian-ships/235590
- The Maritime Executive, Black Sea drone attack on shipping, Sept. 17, 2026: https://maritime-executive.com/article/drone-attack-kills-master-injures-three-crewmembers-in-black-sea
- Reuters, Ukraine strikes on shadow-fleet tankers, July 7, 2026: https://www.reuters.com/world/europe/ukraine-strikes-eight-russian-shadow-fleet-tankers-kyiv-says-2026-07-07/
VLCC fleet history, orders, deliveries
- Reuters, “US-Iran conflict helps drive wave of supertanker orders,” Sept. 17, 2026: https://www.reuters.com/business/energy/us-iran-conflict-helps-drive-wave-of-supertanker-orders-2026-09-17/
- Seatrade Maritime, “Record VLCC orders raise fears of 2028 tanker squeeze,” July 15, 2026: https://www.seatrade-maritime.com/tankers/record-vlcc-orders-raise-fears-of-2028-tanker-squeeze
- Splash247, “VLCC orderbook hits record high,” June 9, 2026: https://splash247.com/vlcc-orderbook-hits-record-high/
- Tanker Operator, “177 VLCCs ordered in first half of 2026”: https://www.tankeroperator.com/news/177-vlccs-ordered-in-first-half-of-2026-highest-in-history-by-far/15452.aspx
- Gibson, “Too Much of a Good Thing,” June 12, 2026: https://www.gibsons.co.uk/report/too-much-of-a-good-thing/
- Tankers International, “How crude tanker markets have changed over the past 25 years,” Sept. 23, 2025: https://tankersinternational.com/2025/09/23/how-crude-tanker-markets-have-changed-over-the-past-25-years/
- Splash247, “Close to one in five VLCCs trading today are over 20 years old,” April 25, 2025: https://splash247.com/close-to-one-in-five-vlccs-trading-today-are-over-20-years-old/
- TradeWinds, “VLCC fleet shrinks as crude tanker deliveries hit 36-year low,” Jan. 22, 2025: https://www.tradewindsnews.com/tankers/vlcc-fleet-shrinks-as-crude-tanker-deliveries-hit-36-year-low/2-1-1768036
- Charles R. Weber, tanker fleet growth profile (2010–2020 January 1 counts): https://crweber.com/wp-content/uploads/2021/11/CRW-Fleet-Growth-Profile-10.05.16.pdf
- Clarksons Research world tanker fleet table, March 2026, via listed company 20-F excerpt: https://d18rn0p25nwr6d.cloudfront.net/CIK-0001815779/4a18ad42-bf01-4c33-b624-4677d9011946.pdf
- Scorpio Tankers 20-F fleet tables (Feb. 2025 and Feb. 2026 VLCC counts): https://www.scorpiotankers.com/wp-content/uploads/2025/03/Scorpio-Tankers-2024-Annual-Report.pdf and https://www.scorpiotankers.com/wp-content/uploads/2026/03/STNG-2025-12-31-20F.pdf
- Frontline presentation / Clarksons-Fearnleys delivery-by-build-year series compiled in public research note: https://drive.google.com/uc?export=download&id=1BrSv0KZn7YNmXbjcH5k66elQMNMpCItm
- Okeanis Eco Tankers Q1 2026 presentation (Hormuz shock, orderbook): https://www.okeanisecotankers.com/media/6a0c572c978c4.pdf
- Breakwave Advisors, “Tanker Big Picture: Mideast state fleet boom?” Sept. 14, 2026: https://www.breakwaveadvisors.com/insights/2026/9/13/tanker-big-picture-mideast-state-fleet-boom
- El País, “Wanted: Oil tankers at any cost,” Sept. 13, 2026: https://english.elpais.com/economy-and-business/2026-09-13/wanted-oil-tankers-at-any-cost-as-tensions-in-the-gulf-trigger-a-global-scramble.html
JPMorgan and oil-price / refinery analysis
- Reuters, “JP Morgan says it has no clear oil market endgame as Iran conflict drags on,” Sept. 17, 2026: https://www.reuters.com/business/energy/jp-morgan-says-it-has-no-clear-oil-market-endgame-as-iran-conflict-drags-2026-09-17/
- TipRanks / Kaneva note summary, Sept. 18, 2026: https://www.tipranks.com/news/jpmorgan-chase-jpm-abandons-oil-price-forecast-as-redlines-crossed
- IEA Oil Market Report, September 2026: https://www.iea.org/reports/oil-market-report-september-2026
- EIA Short-Term Energy Outlook, September 2026: https://www.eia.gov/outlooks/steo/pdf/steo_text.pdf
- Reuters poll on 2026 oil forecasts after earlier Hormuz reopening hopes, June 30, 2026: https://www.reuters.com/business/energy/poll-analysts-dial-down-oil-forecasts-hormuz-reopening-eases-supply-concerns-2026-06-30/
- Kpler, “Higher floor, hard ceiling: why we have raised our crude forecast to $81/bbl,” Sept. 17, 2026: https://www.kpler.com/blog/higher-floor-hard-ceiling-why-we-have-raised-our-crude-forecast-to-81-bbl
- ABN AMRO, “Supply shortage keeps oil and product prices firm”: https://www.abnamro.com/research/en/our-research/supply-shortage-keeps-oil-and-product-prices-firm
- TD Economics, “Oil Markets Have Bought Time, Not Insurance”: https://economics.td.com/ca-oil-markets
Charts compiled for Energy News Beat from Clarksons/Fearnleys delivery series via Frontline Q1 2026 materials, Charles R. Weber historical fleet counts, and Clarksons March 2026 world fleet tables. Orderbook totals continued to rise after mid-year snapshots; 2028–2029 delivery estimates differ by broker.